He Sold the Permit With the Boat. Social Security Counted the Last Catch and Ignored the Right to Another One.
When a salmon fisherman sold his boat, gear, and fishing permit in one deal, Social Security split that single transaction into three separate categories and only recognized one of them as earnings. Knowing which piece falls where could protect months…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
One Last Catch
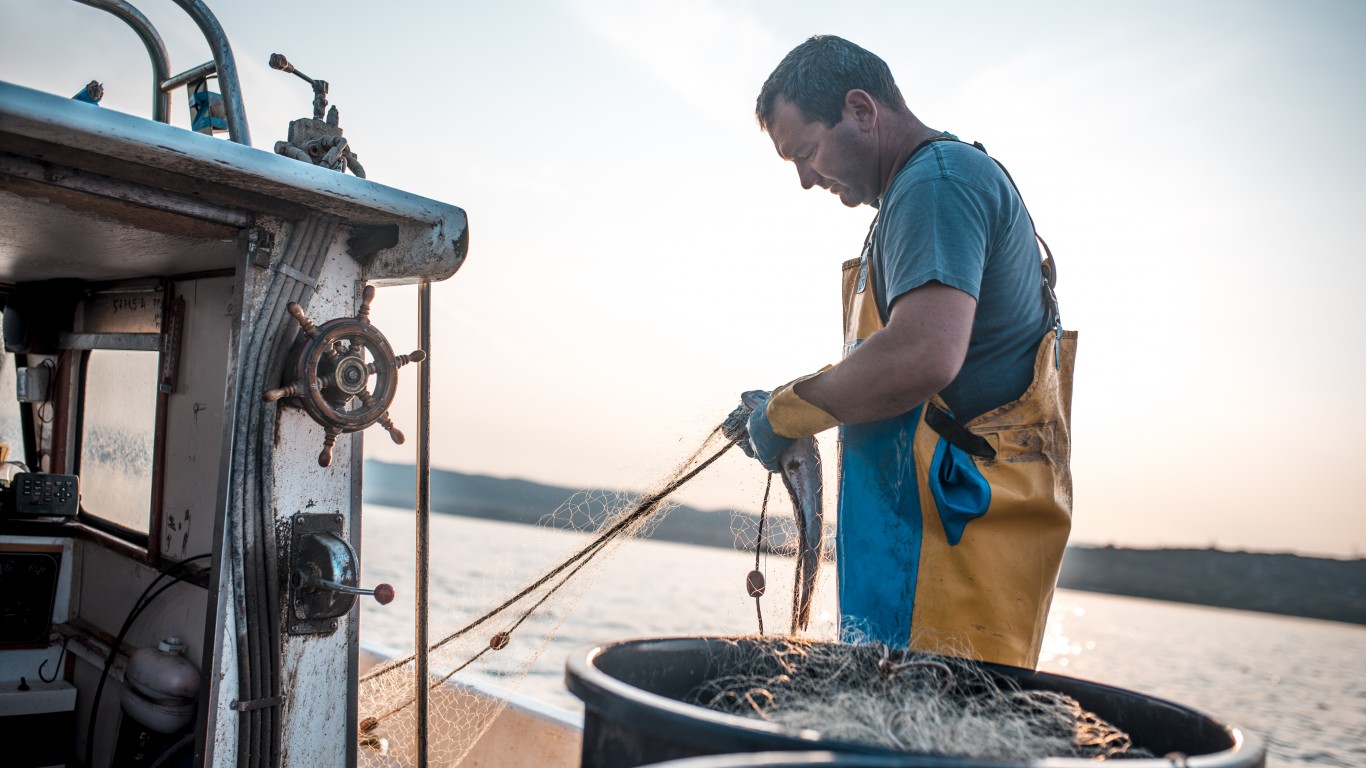
An aging salmon fisherman has spent decades running his own boat. After years of closures and thin seasons, he goes out one final time, sells the catch, and prepares to retire. A younger operator offers to buy the boat, gear, and transferable fishing permit as one package.
The fisherman has already claimed Social Security before reaching full retirement age (FRA). To him, the money arriving that year represents one final payday from the same business. Social Security sees three different things. The fish are income from working. The boat is equipment. The permit is an intangible right. Only one ordinarily enters the retirement earnings test.
The Fish Still Look Like Work
A self-employed commercial fisherman generally reports income and expenses from selling his catch on Schedule C. The resulting net earnings can be subject to self-employment tax and count under Social Security’s earnings test. In 2026, someone below FRA for the entire year can earn $24,480 before Social Security begins withholding $1 in benefits for every $2 above that limit. In the year the worker reaches FRA, a higher threshold applies: $65,160, with only $1 withheld per $3 above it, and only for earnings before the birthday month. Once FRA arrives, the test disappears entirely.
Benefits withheld under the test are not necessarily lost. Social Security recalculates the benefit at full retirement age to credit months when checks were withheld. Still, losing checks during the year a business closes can leave a real hole in the retirement plan, particularly when the fisherman expected a clean exit.
The Permit Does Not
The permit is not inventory and does not represent payment for the fisherman’s labor. It is a business asset that gave him permission to operate in a restricted fishery. Social Security generally excludes gains from selling noninventory business property when calculating net earnings from self-employment. Its own guidance for the year a business is sold says to include proceeds from inventory but exclude income from assets that are not inventory.
The boat and equipment generally sit outside the earnings test for the same reason. Selling the tools of the business is different from earning money by using them. Transferability is the first practical hurdle. Some fishing permits can follow the boat or move to a qualified buyer; others cannot be sold at all, or require approval from the issuing agency. Dock talk does not settle that question.
One Price Needs Several Buckets
If the buyer writes one check for the boat, gear, and permit, that purchase price still has to be divided among those assets. The allocation should reflect reasonable market values, not whichever numbers produce the friendliest tax return. The seller’s basis and ownership history matter considerably. A vessel or equipment that has been heavily depreciated may produce ordinary income through depreciation recapture. A permit purchased and amortized as a Section 197 intangible, which government-issued licenses and permits can qualify as under IRS rules, carries its own recapture and Section 1231 consequences when sold. Other permits may receive different treatment depending on how and when they were obtained.
According to IRS Publication 544, gain on amortizable intangible property held longer than one year can receive Section 1231 treatment after applicable recapture. A net Section 1231 gain can ultimately receive long-term capital-gain treatment, but prior losses and other facts can change the result. That is why the allocation belongs in the purchase agreement, supported by defensible values and reviewed before anyone signs.
Ignored by One Formula, Seen by Another
Falling outside Social Security’s earnings test does not make the permit gain tax-free. Taxable gain raises adjusted gross income and, in turn, the combined-income calculation used to determine how much of his Social Security is taxable. Combined income is adjusted gross income plus any tax-exempt interest plus half of annual Social Security benefits. For single filers, combined income above $34,000 can push up to 85% of benefits into taxable income. For married couples filing jointly, the same ceiling applies above $44,000. That 85% figure is the ceiling on how much of the benefit enters taxable income, not a tax rate on the benefit itself. The monthly check may remain untouched while the tax bill attached to those benefits grows. Those are two separate consequences administered under two separate formulas.
Set the Split Before the Boat Leaves
Three steps can keep the final season from producing an avoidable surprise:
- Confirm with the issuing agency that the permit can be transferred and what approval is required.
- Assign supportable values to the boat, gear, permit, and any inventory in the written agreement.
- Model both the earnings test and the taxation of Social Security before setting the closing date.
The buyer saw one fishing operation changing hands. Social Security saw fish, steel, and a government-granted right, and counted only the part that still smelled like work.
Editor’s note: This update adds the $65,160 FRA-year earnings test threshold and the $1-per-$3 withholding rate that the original omitted, and expands the taxation section to include the $34,000 single / $44,000 joint combined-income thresholds that trigger the 85% benefit-taxation ceiling.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.