Reddit’s Bull Case for Zoom Has Nothing to Do With Video Calls
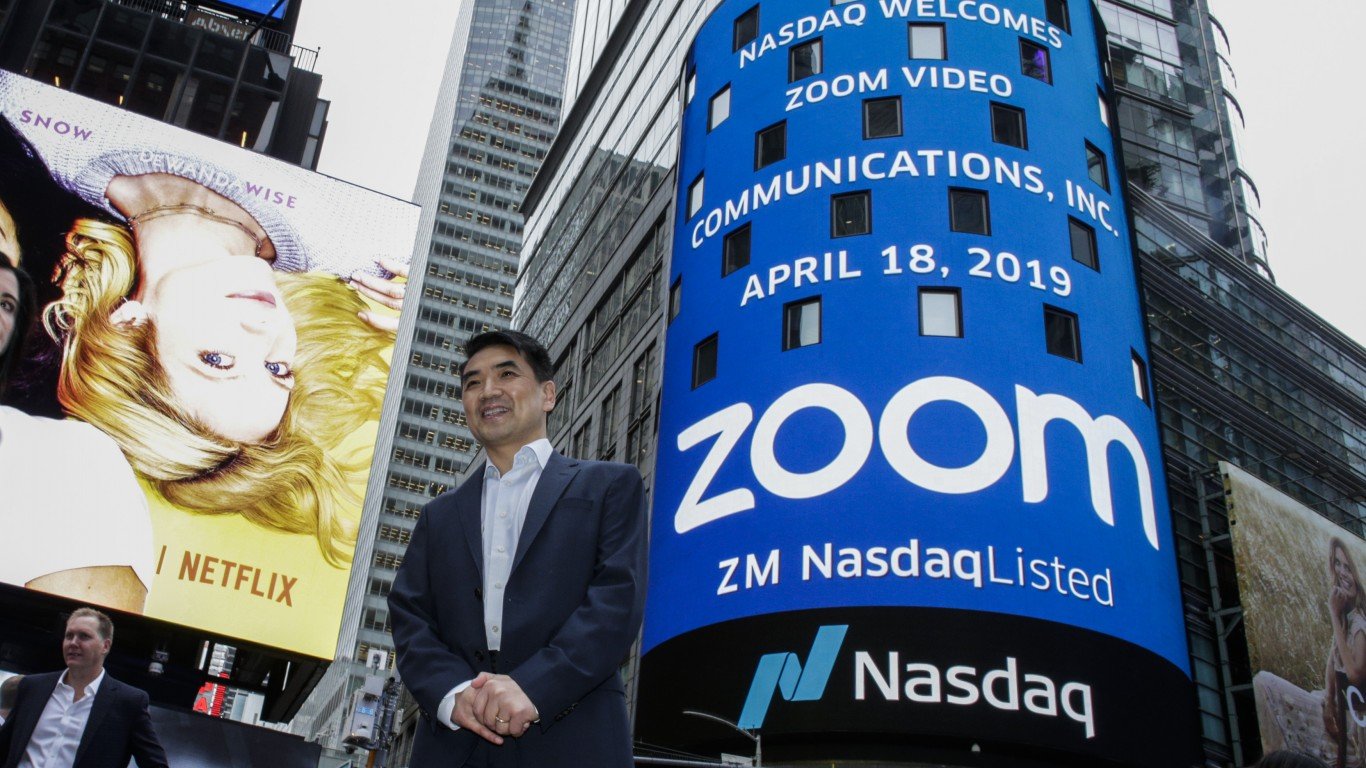
Still one of the most popular video calling tools, Zoom’s Q4 FY2026 earnings handed investors a headline that looked spectacular and a full-year figure that quietly disappointed. Zoom Video Communications (NASDAQ:ZM | ZM Price Prediction) posted $1.247 billion in Q4…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
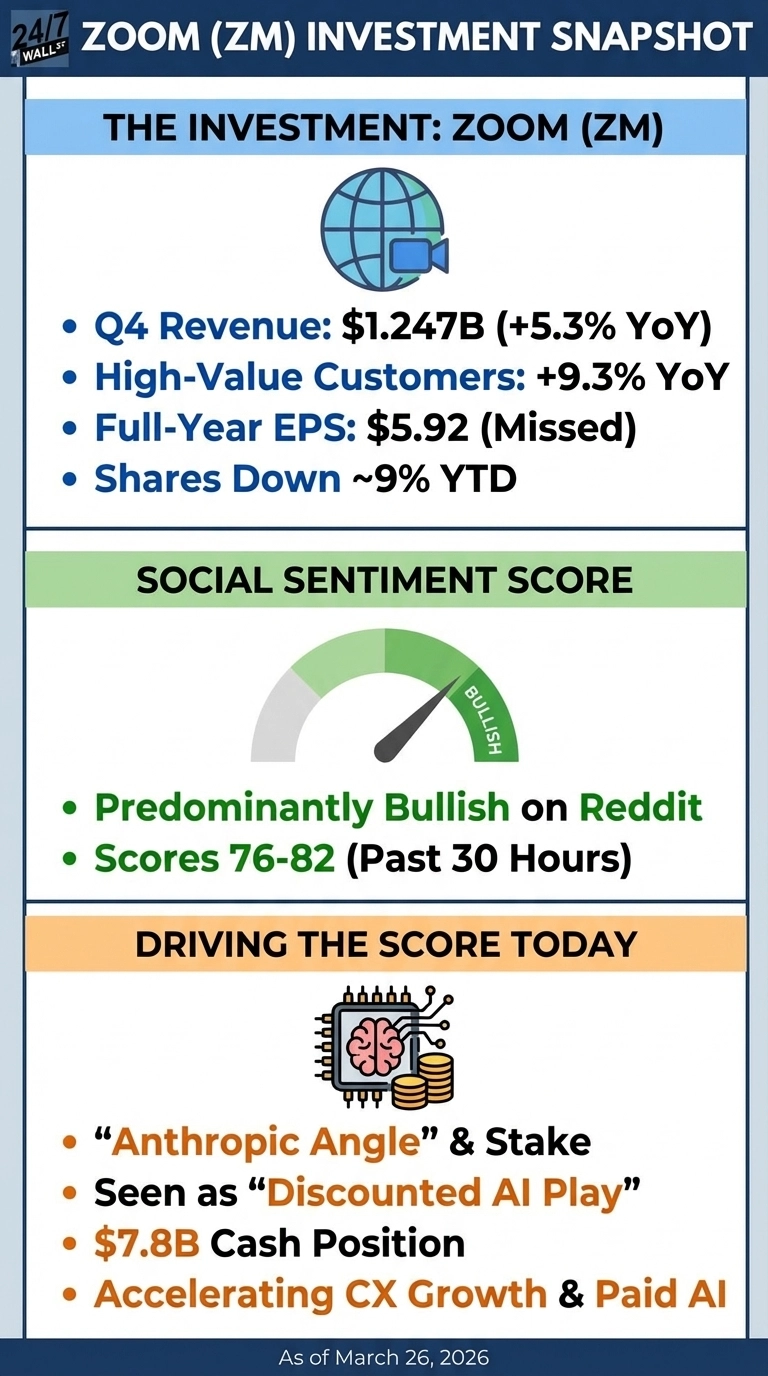
Still one of the most popular video calling tools, Zoom’s Q4 FY2026 earnings handed investors a headline that looked spectacular and a full-year figure that quietly disappointed. Zoom Video Communications (NASDAQ:ZM | ZM Price Prediction) posted $1.247 billion in Q4 revenue, up 5.3% year-over-year, beating estimates by 0.6%. High-value enterprise customers grew 9.3% year-over-year to 4,468 accounts. Yet the full-year non-GAAP EPS of $5.92 missed the $5.9724 estimate, marking Zoom’s first EPS miss in seven quarters. Shares dropped roughly 12% in the session after earnings and remain down about 7.5% year to date.
The Q4 non-GAAP EPS of $1.44, which beat the $0.85 estimate by 69%, was heavily distorted by $532 million in gains on strategic investments. Free cash flow fell nearly 19% year-over-year in Q4; the enterprise net dollar expansion rate was 98%, below the 100% threshold; and online monthly churn ticked up to 2.9% from 2.8%.
The Anthropic Angle Driving Reddit’s Bull Case
Sentiment on r/wallstreetbets has been predominantly bullish over the past 30 hours, with scores ranging from 76 to 82 across six of eight measured windows. The conversation centers on a thread titled “$ZM – Best Anthropic Play, Trades Below Nav.” from u/Stonkgang_, which has accumulated 109 upvotes and 55 comments.
$ZM – Best Anthropic Play, Trades Below Nav.
by u/Stonkgang_ in wallstreetbets
The post argues “$ZM, yes, Zoom Video owns a 1% stake in Anthropic due to its early investment in 2023… it generates 2bn in FCF a year, has a market cap of 22bn, with 7.8bn in cash… its entire core business trades at 5x FCF ($10bn)”, making Zoom the most efficient way to buy Anthropic exposure at a discount. Zoom carries $7.8 billion in cash against a $23 billion market cap, trades at roughly 12x trailing earnings, and guides for $5.065 to $5.075 billion in FY2027 revenue, the first time it would cross the $5 billion milestone. The bull case rests on three pillars:
- Zoom’s Anthropic stake and $7.8 billion cash position create a balance sheet that prices the core video and CX business at a deep discount to intrinsic value.
- Zoom Customer Experience saw accelerating high-double-digit growth in Q4, with paid AI included in each of the top 10 CX deals, pointing to real product expansion beyond legacy video.
- The analyst consensus of 14 buy ratings and a $97 average price target sits well above the current share price near $80, with at least one firm carrying a $115 price target.
Where the Bear Case Still Has Teeth
For investors focused on finances, Zoom’s free cash flow guidance for FY2027 is $1.70 to $1.74 billion, down from the $1.924 billion generated in FY2026. A net dollar expansion rate below 100% means existing enterprise customers are spending less than they did a year ago. Revenue growth is expected to decelerate, with consensus projecting 3.3% growth in the fiscal year after next. Microsoft Teams remains a formidable free alternative for enterprise buyers locked into Microsoft 365, and management explicitly flagged lengthened sales cycles.
At roughly 14x on guided EPS of $5.77 to $5.81 is reasonable for a profitable, cash-generative technology business. The Anthropic stake and agentic AI roadmap are the variables that will determine whether Zoom earns a higher valuation multiple from here.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.