Price Prediction: CoreWeave Has 124% Upside Despite Capex Concerns
CoreWeave's shares have cratered over 40% in the past year while its business is booking record revenue and a backlog nearing $100 billion, and that contradiction creates one of the most contested trades in AI infrastructure right now.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

CoreWeave (NASDAQ:CRWV) has become the poster child for the AI infrastructure gold rush, and also its most polarizing bet. Capital expenditures are set to run $31 billion to $35 billion in 2026 alone, dwarfing revenue and lighting up both the bull and bear thesis. Our model sees meaningful upside from here.
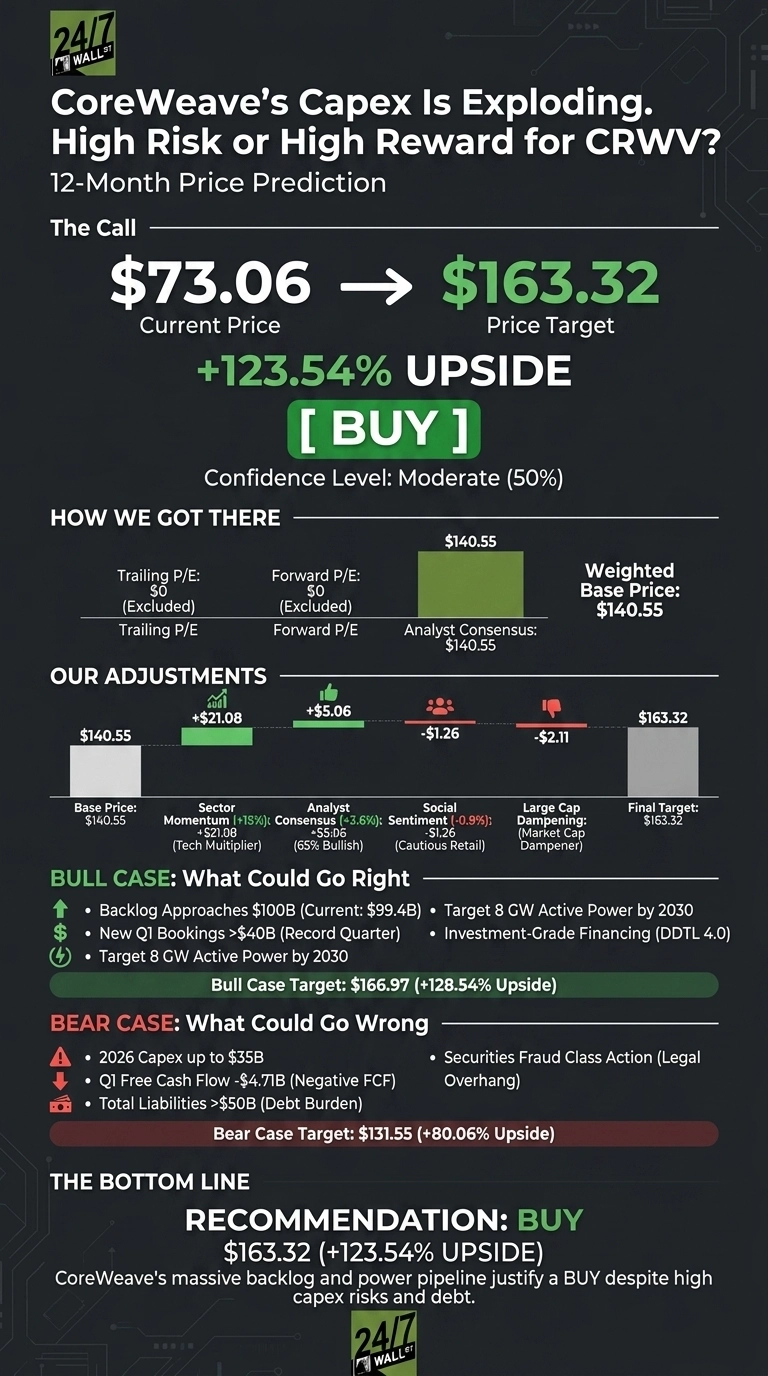
Our 24/7 Wall St. price target on CRWV is $163.32 over the next 12 months, versus a current price of $73.06. That implies 123.54% upside and a buy recommendation. Confidence is moderate at 50%, reflecting the tension between a nearly $100 billion backlog and a balance sheet stretched by breakneck capex.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $73.06 |
| 24/7 Wall St. Price Target | $163.32 |
| Upside | 123.54% |
| Recommendation | BUY |
| Confidence Level | 50% |
A Brutal Month for a Booming Business
CRWV has traded like a stock in crisis. Shares fell 38.06% over the past month and 40.61% over the past year, even as the business booked its strongest quarter yet.
Q1 2026 revenue hit $2.08 billion, up 111.7% year over year, while backlog reached $99.4 billion. A July Meta Compute announcement spooked investors about cannibalization. Debt has climbed to roughly $35 billion, net loss widened to $740 million, and interest expense doubled to $536 million.
The Case for $200 and Higher
Bulls have real ammunition. New Q1 bookings exceeded $40 billion, and management guides to $12 billion to $13 billion in 2026 revenue with low-double-digit adjusted operating margin by Q4. CoreWeave surpassed 1 GW of active power and targets more than 8 GW by 2030.
Investment-grade financing on DDTL 4.0 at sub-6% implied cost is a structural win. Rosenblatt’s John McPeake carries the most aggressive Street call at $250, reiterated after the Meta scare. Our bull-case scenario points to $166.97, roughly 128.54% upside.
What Could Go Wrong
The bear case starts with capex arithmetic. Q1 2026 free cash flow ran negative $4.71 billion, and 2026 capex guidance of up to $35 billion means CoreWeave will keep leaning on capital markets. Total liabilities sit above $50 billion.
A securities fraud class action alleging concealed data center delays adds legal overhang. Customer concentration is real: Meta and OpenAI alone represent tens of billions in commitments.
Management pushed back that gross margin compression to 68% is “predominantly timing-based, not economic” as new deployments ramp. Our bear-case target lands at $131.55, well above today’s price.
How CoreWeave Compares to Nebius and IREN
Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) competes for the same hyperscaler and AI-lab dollars. It achieved positive adjusted EBITDA of $129.5 million and carries a market cap of roughly $40 billion, similar to CRWV’s $39.9 billion. Yet Nebius’s 2026 revenue guide of $3 billion to $3.4 billion is a fraction of CoreWeave’s $12 billion to $13 billion. On a price-to-sales basis, CRWV at 6.41x trailing looks reasonable.
IREN (NASDAQ:IREN) is the smaller, faster-mover comparable. IREN targets $3.7 billion in ARR by end of 2026 with 5 gigawatts of secured power globally and a $3.4 billion NVIDIA cloud contract. At a market cap of roughly $14 billion, IREN trades cheaper on power secured, but CoreWeave has the contracted revenue lead. The peer set makes our $163.32 target reasonable, not aggressive.
CoreWeave Price Prediction 2026-2030
The setup on CRWV looks constructive. The 24/7 Wall St. price target of $163.32 reflects a company whose backlog and power pipeline justify a re-rate once operating margin inflects in the second half of 2026.
Confidence is moderate at 50% because debt and litigation are genuine tail risks. Watch for adjusted operating margin exiting Q4 in the low double digits as guided. The setup weakens if capex creeps above $35 billion without matching backlog conversion.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $101 |
| 2027 | $163 |
| 2028 | $260 |
| 2029 | $420 |
| 2030 | $560 |
These projections assume CoreWeave converts backlog on schedule and reaches its 8 GW power target by 2030. Meaningful upside or downside could come from Nvidia GPU pricing, litigation outcomes, or hyperscaler in-sourcing shifts.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.