Meta Price Prediction: Analysts See 40% Upside Ahead
Meta shed more than 15% this year while its ad engine quietly posted one of its strongest quarters ever, and that contradiction is exactly where the opportunity hides.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
After a punishing July that shaved more than 15% off the stock, Meta Platforms (NASDAQ: META | META Price Prediction) is trading well below where our model says it should.
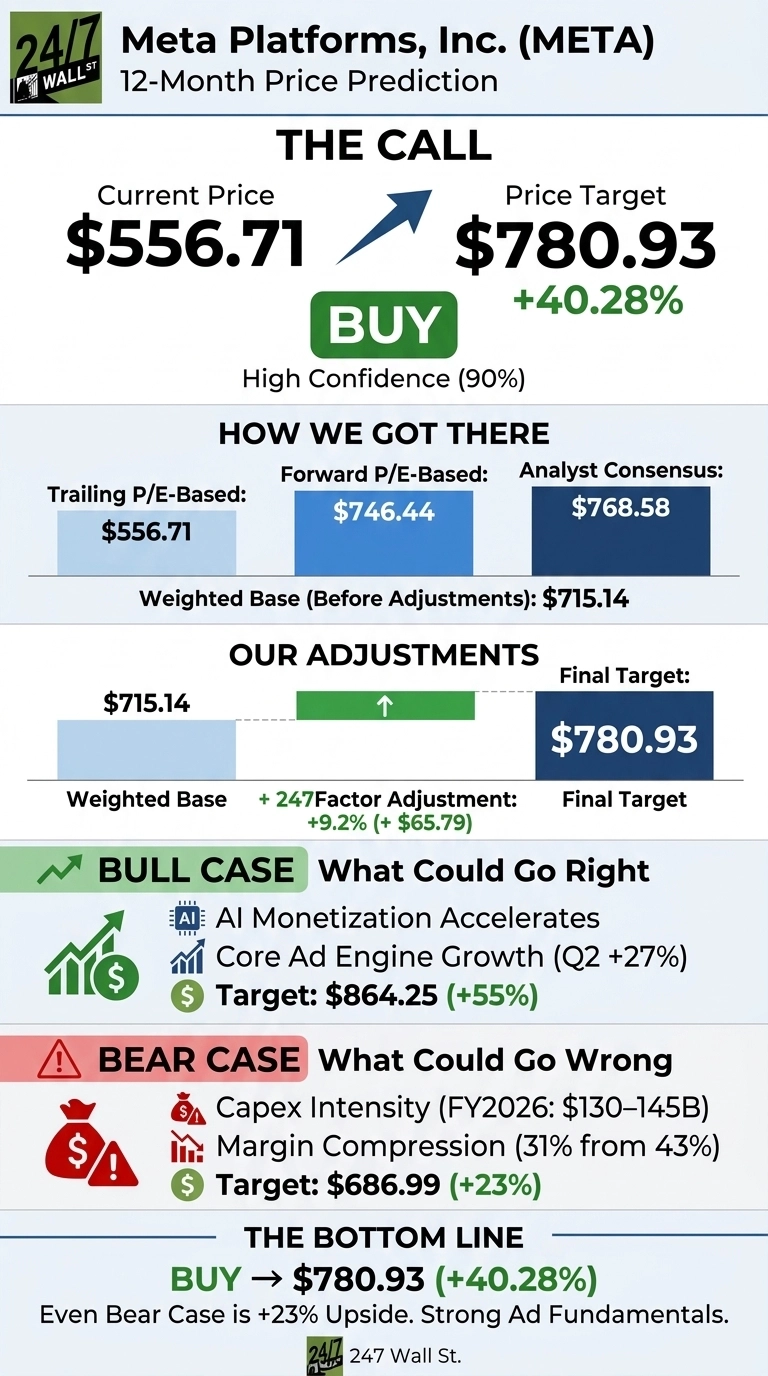
Our 24/7 Wall St. price target for Meta is $780.93, implying 40.28% upside from the current $556.71 quote. That anchors a buy recommendation with a confidence level of 90%. Analyst consensus sits close to our number at $768.58, with 57 buy ratings against zero sells.
| Metric | Value |
|---|---|
| Current Price | $556.71 |
| 24/7 Wall St. Price Target | $780.93 |
| Upside | 40.28% |
| Recommendation | BUY |
| Confidence Level | 90% |
How Meta Ended Up in the Bargain Bin
Meta closed July at $556.71, down 9.17% for the month and 15.52% year to date.
Q2 revenue of $60.80 billion grew 27.96% and topped the Street, but EPS of $6.18 missed expectations of $7.22, snapping a six-quarter beat streak. A $2.40 billion legal charge and $1.18 billion in severance tied to an 8,000-employee reduction drove the miss. Free cash flow collapsed to $784 million, and FY2026 capex guidance narrowed to $130 to $145 billion.

Why Bulls See a Breakout Ahead
The core ad engine is sound. Ad impressions grew 14% and price per ad grew 12% in Q2, with advertising revenue up 27% to $59.36 billion. Family daily active people reached 3.60 billion. Q3 guidance of $61 to $64 billion implies further acceleration.
Morningstar maintains a $850 fair value estimate, arguing the sell-off is an overreaction. Our bull scenario points to $864.25 over 12 months if AI monetization accelerates and the Meta Business Agent launched August 1 gains traction with enterprise advertisers.

What Could Go Wrong
Capex intensity is the real risk. FY2026 spending of $130 to $145 billion nearly doubles the $72.22 billion spent in 2025, and operating margin compressed to 31% from 43% from a year ago. Bears worry Meta is spending without defined returns.
Bulls counter that margin compression reflects one-time legal and severance items totaling $3.58 billion, and BlackRock joint ventures are keeping data center assets off the balance sheet. Our bear case still lands at $686.99, well above today’s price.

How Meta Compares to Alphabet and Pinterest
Alphabet (NASDAQ: GOOGL) is the sharpest comp: same ad model, same AI capex arms race. It trades at a P/E of 16 versus Meta at 20, with Q2 2026 revenue growth of 24.23% and Google Cloud accelerating to 82% growth. Alphabet is rewarded for visible AI monetization while Meta is punished for opacity. That gap looks overdone.
Pinterest (NYSE: PINS) is the pure-play visual-ad counterpoint at a $11.57 billion market cap. Q1 2026 revenue grew 17.8% to $1.01 billion with 631 million monthly users, but carries no AI infrastructure liability or legal overhang. The contrast highlights why Meta’s fear discount is a scale problem tied to capex magnitude rather than fundamental business weakness.
| Company | Trailing P/E | Latest Revenue Growth |
|---|---|---|
| Meta | 20 | 27.96% |
| Alphabet | 16 | 24.23% |
| n/a | 17.84% |
I’d Buy the Pullback
Our 24/7 Wall St. price target of $780.93 stands, buy rating intact, confidence at 90%. Ad fundamentals are accelerating, one-time charges obscured the quarter, and even the bear case sits 23% above today’s price.
The setup favors investors who can stomach capex-driven volatility into 2027. Caution is warranted if Q3 revenue lands below the $61 billion guidance floor, which would signal the ad engine is faltering as spending peaks.
Meta Price Prediction 2026-2030
Here is where our model projects Meta could trade, assuming current growth trajectories and disciplined AI monetization.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $780 |
| 2027 | $900 |
| 2028 | $1,050 |
| 2029 | $1,225 |
| 2030 | $1,431 |
These projections assume Meta executes on its AI-powered ad platform and Reality Labs losses stabilize. Significant upside could come from enterprise AI monetization; the biggest downside risk remains unchecked capex without a visible ROI window.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.