Price Prediction: CoreWeave Will Trade at This Price in 2027
CoreWeave's revenue backlog just hit nearly $100 billion while its stock trades near a 52-week low, and that gap between signal and price is exactly where the opportunity or the trap lives.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
CoreWeave (NASDAQ:CRWV) is the pure-play GPU cloud between hyperscalers and AI models. CEO Michael Intrator called Q1 2026 “the strongest bookings quarter in CoreWeave’s history, with revenue backlog reaching nearly $100 billion.”
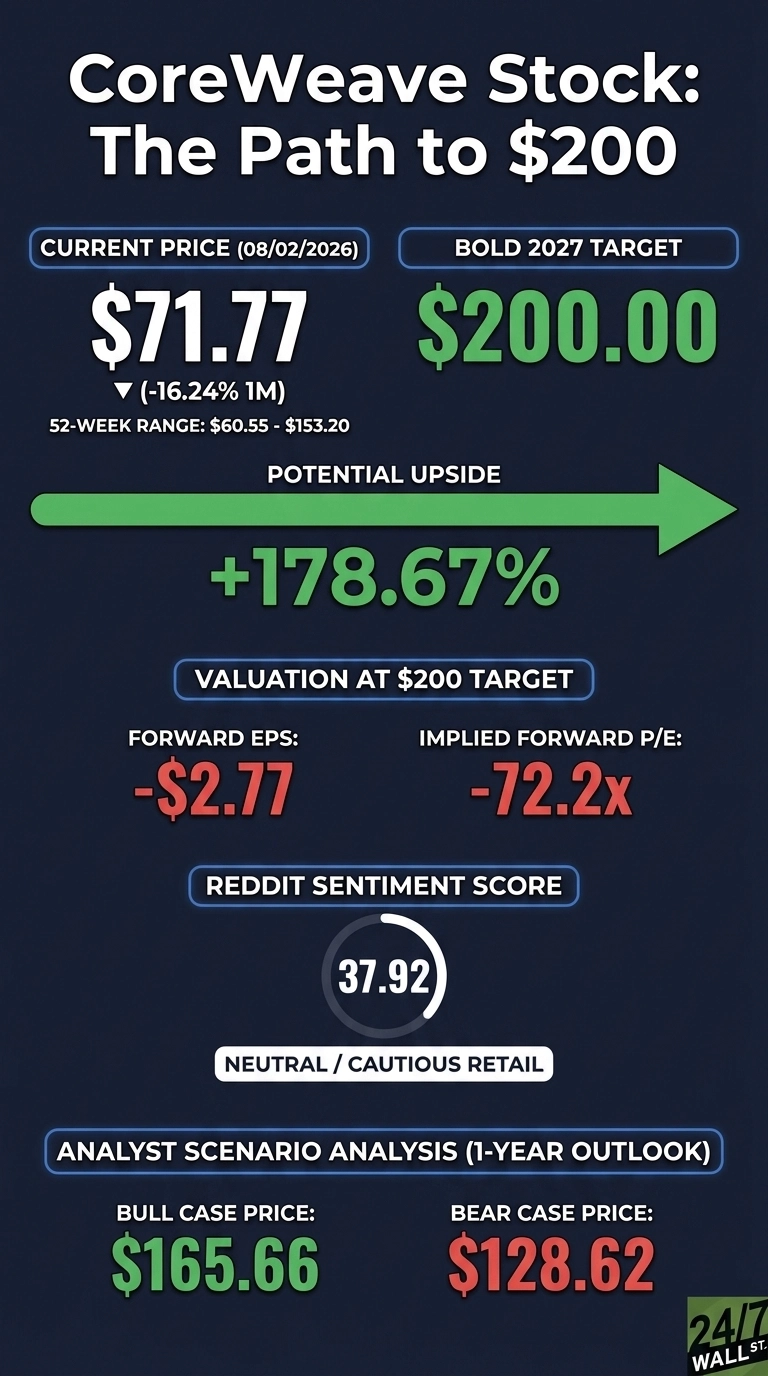
Revenue jumped 111.7% YoY to $2.078 billion. Yet shares trade at $71.77, less than half the 52-week high of $153.20. Can CoreWeave hit $200 by 2027?
What’s Holding CoreWeave Back Right Now
The disconnect between fundamentals and price is real. Shares are flat YTD at +0.22%, down 16.24% over the past month, and off 37.12% over the last year.
The issue is capital intensity. Q1 2026 CapEx hit $7.695 billion against $2.078 billion in revenue, producing negative $4.711 billion in free cash flow. Interest expense doubled to $536 million. EPS came in at -$1.40, missing the -$1.20 estimate.
Total liabilities sit at $50.814 billion against equity of $4.759 billion. A securities fraud class action tied to alleged data center construction delays adds pressure. The stock can’t move higher until profitability arrives.
Wall Street Sees 92% Upside. Our Model Says More
Analyst target price sits at $138.03, with 4 strong buy, 20 buy, 11 hold, 1 sell, and 1 strong sell ratings. Our base case reaches $160.39, implying 123.48% upside, with a bull case at $165.66 and a bear case at $128.62. Confidence is moderate at 0.5.
Analysts are anchored to near-term losses and missing the backlog signal. 65% of ratings are bullish, yet the average target sits below where recovery math points if backlog conversion holds.
The Path to $200 Per Share
Reaching $200 from today’s $71.77 would require a gain of roughly 178%. Forward EPS is -$2.77, meaning a $200 price implies a forward P/E of -72x. With earnings negative, the classic P/E is not the right lens. Revenue and EBITDA multiples do the work.
TTM revenue is $6.227 billion, EBITDA is $3.024 billion, and backlog is $99.4 billion, nearly 48x quarterly revenue. To reach $200, CoreWeave needs backlog conversion to drive Q3 2025’s 61% adjusted EBITDA margin across a larger revenue base, plus 1 GW-plus power scaling toward the 8 GW target by 2030.
Intrator framed the moat: “AI natives and enterprise customers are choosing CoreWeave because we sit between the models and the silicon.” The risk is refinancing. If interest expense keeps doubling, equity gets diluted before the story compounds.
Where CoreWeave Trades Today vs Its Earnings Power
CoreWeave trades at 6.29x price-to-sales and 23.94x EV/EBITDA. For a business growing revenue 111.6% YoY with a nine-figure backlog, that is not expensive.
Shares sit near the low end of the 52-week range of $60.55 to $153.20. The five-year gain since the March 2025 IPO is 79.42%, well off peaks. The valuation case is straightforward: if backlog converts and EBITDA compounds, the multiple compresses fast at today’s price.
Is $200 Realistic? Here’s My Take
Reaching $200 by 2027 requires a roughly 178% gain from $71.77. My verdict: a stretch, but not a fantasy.
Three things need to go right. Backlog needs to convert cleanly (the $21 billion Meta commitment is the tell). EBITDA margins need to hold near 60% as the asset base scales. The balance sheet needs refinancing without heavy dilution. What derails it is another quarter where CapEx and interest expense outrun revenue recovery. We’ve outlined the blueprint for how CoreWeave could reach $200 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.