Amazon Could Soon Surpass Nvidia and Become The World’s Most Profitable Company. 2030 Profits Could Exceed $500 Billion.
UBS just published a profit projection for Amazon that would reshape the entire corporate landscape by 2030, and the number hinges almost entirely on a single segment now growing at its fastest clip in four and a half years.


The Number
$509 billion. That is what UBS projects Amazon (NASDAQ:AMZN | AMZN Price Prediction) will earn in net income by 2030, according to a new estimate from the bank. If Amazon lands anywhere close to that figure, it would clear the current Wall Street consensus for Nvidia (NASDAQ:NVDA) 2030 net profit of roughly $450 billion and hand Amazon the title of the most profitable company on Earth. This is a UBS projection rather than company guidance or a reported figure.

What It Means
UBS is laying out a multi-year ramp. The bank sees Amazon posting roughly $120 billion in net earnings in 2026, around $281 billion by 2028, and approximately $509 billion by 2030. On a per-share basis, UBS pencils out $45.16 in EPS at the end of that curve, which means Amazon is trading at about 6 times the bank’s 2030 profit estimate.
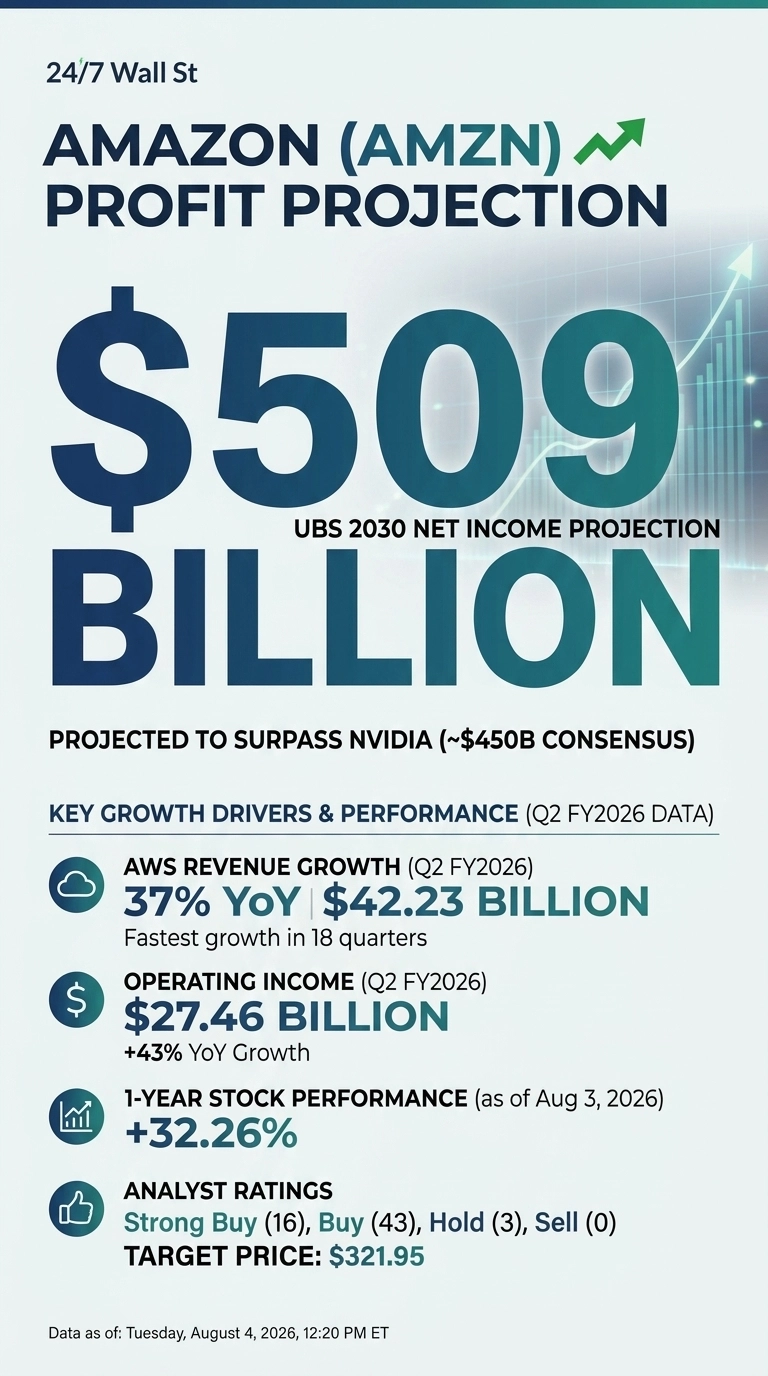
For context on where Amazon starts from: full-year 2025 net income was $77.67 billion on $716.92 billion in revenue. In the most recent quarter (Q2 FY2026), Amazon reported operating income of $27.46 billion, up 43% year over year, and net income of $62.65 billion. The reported net income figure was inflated by $53.4 billion of non-operating pre-tax income tied to the Anthropic investment, a one-time mark that will not repeat every quarter. The operating line is the clean read, and it is expanding at a rate that makes UBS’s ramp look less like fantasy.
The AWS Engine
The math behind UBS’s projection sits inside one segment. AWS grew 37% year over year in Q2 FY2026 to $42.23 billion in revenue, its fastest growth in 18 quarters, at a 39.4% operating margin. Growth has accelerated for four straight quarters: 20% in Q3 2025, 24% in Q4 2025, 28% in Q1 2026, and now 37%.
UBS models AWS growth reaching 48% in 2027 as OpenAI begins running workloads on Amazon’s Trainium chips. That is the swing factor. Amazon’s AI and Chips businesses each eclipsed run rates of more than $25 billion in Q2, both growing at triple-digit rates. OpenAI has already committed to roughly 2 GW of Trainium capacity through AWS beginning in 2027, and Anthropic is on the hook for up to 5 GW of current and future Trainium chips. Layer 48% growth on top of a segment already running at a $169 billion annualized revenue pace, then compound that through the end of the decade, and AWS starts to look like the profit engine capable of dragging total net income into the half-trillion neighborhood.
Amazon is spending to make it happen. CEO Andy Jassy told investors Amazon will invest about $200 billion in capital expenditures across 2026 on AI infrastructure, custom chips, robotics, and satellites. Q2 capex alone hit $54.21 billion, up 68.44% year over year.
Market Reaction
Amazon shares closed at $284.02 on August 3, 2026, with the stock up 23.05% year to date and 32.26% over the past year. In the one week following the Q2 earnings report, the stock ran 22.75%, from $231.39 on July 27 to $284.02 on August 3. On the day of the Q2 report itself, shares moved roughly +4.50%. Amazon carries a market capitalization of roughly $2.92 trillion, while Nvidia sits at about $4.86 trillion.
Bull Case
Long-term holders own a rare setup here: a business already generating $77.67 billion of annual net income and accelerating into its highest-margin, fastest-growing segment right as multi-gigawatt AI compute contracts start turning on. UBS’s $509 billion 2030 profit estimate implies roughly a sixfold ramp from 2025 net income. AWS growth has climbed for four consecutive quarters. Operating income is compounding at 43% year over year. Advertising, another high-margin segment, grew 26% to $19.81 billion in Q2 and TTM ad revenue has crossed $70 billion.
Guidance for the current quarter points to operating income of $22.5 billion to $26.5 billion, versus $17.4 billion in Q3 2025. Analysts have a $321.95 target price on the stock, with 16 Strong Buy, 43 Buy, and 3 Hold ratings and no Sells. If Amazon merely hits UBS’s $120 billion 2026 net income estimate, it will already be earning at a pace that closes the gap against Nvidia’s $120.07 billion in FY2026 net income. From there, UBS is arguing that Trainium-driven AWS acceleration does the rest of the work.
Bottom Line
UBS’s $509 billion 2030 profit projection is a bank estimate rather than a commitment. But it puts a specific dollar value on what has been an abstract narrative: Amazon becoming the largest profit machine on the planet by the start of the next decade. The near-term catalyst is Q3 FY2026 earnings, with Amazon guiding net sales of $197.0 billion to $202.0 billion. For retirement-focused holders, the read is simple: the story hinges on AWS holding its acceleration and Trainium demand from OpenAI, Anthropic, and Meta converting into the profit ramp UBS is modeling. If the cloud engine keeps compounding, the world’s most valuable brand may soon be its most profitable one, too.

Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.