Wall Street Cheers Disney’s Report. Here’s Our New Price Target
Disney just posted its fifth straight earnings beat and sent streaming profits soaring, but the stock still sits nearly 10% in the red for the year. Our model puts a specific number on where shares go from here and why…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Disney’s (NYSE:DIS | DIS Price Prediction) fiscal Q3 report delivered a clean beat and raised outlook. Wall Street responded bullishly, and our model supports the move.
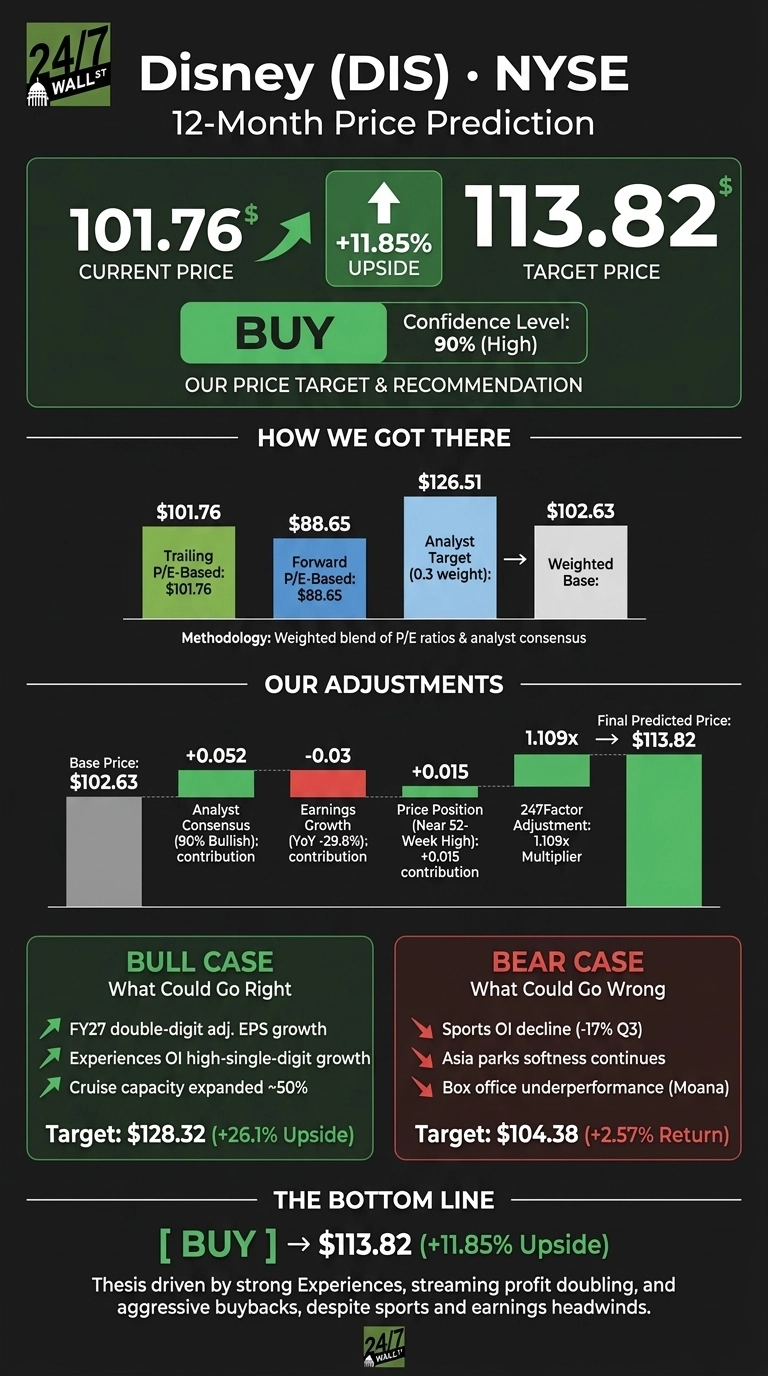
Our 24/7 Wall St. price target for Disney is $113.82 over the next 12 months, implying 11.85% upside from the current $101.76. The recommendation is buy, with a confidence level of 90%. A fifth consecutive earnings beat, doubled streaming profits, and a raised buyback authorization support this thesis.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $101.76 |
| 24/7 Wall St. Price Target | $113.82 |
| Upside | 11.85% |
| Recommendation | BUY |
| Confidence Level | 90% |
What Wall Street Cheered in the Q3 Earnings Report
Disney shares climbed 3.64% on the August 5 earnings report, extending a one-week gain of 3.33% and a one-month move of 4.47%. The stock is down 9.86% year to date and sits 7% below the 52-week high of $118.07, well above the low of $91.49.
Q3 adjusted EPS came in at $2.06 on revenue of $25.248 billion, up 6.76% YoY, marking the fifth consecutive quarter beating consensus. Experiences revenue rose 10% with operating income up 20%, and combined Disney+/Hulu SVOD operating income more than doubled to $712 million.
Toy Story 5 crossed $1 billion globally, lifting Consumer Products to its best growth in 20 quarters. Management raised the FY26 buyback commitment to at least $9 billion and reiterated 12% adjusted EPS growth ex-53rd week.

The Case for $128 and Higher
The bull scenario runs to $128.32, roughly 26.1% upside. Drivers include SVOD margins compounding above management’s double-digit FY26 target, Experiences already guided to high-single-digit growth, and cruise capacity expanded 50% with Disney Destiny and Disney Adventure.
FY27 guidance calls for double-digit adjusted EPS growth. Wall Street’s consensus target of $126.51, with 28 Buy or Strong Buy ratings, sits well above our base case.

What Could Go Wrong
The bear scenario points to $104.38, a return of just 2.57%. Sports operating income declined 17% in Q3 on NBA sweeps and a carriage dispute, Asia parks softness continues into Q4, and Moana’s live-action release underperformed.
Reported net income fell 49.87% YoY. Bulls counter that Q3 free cash flow grew 62.63% to $3.072 billion, operating cash flow rose 32.62%, and total segment OI grew 21%. Net-income optics look worse than the underlying cash engine.
How Disney Compares to Netflix and Comcast
Netflix (NASDAQ:NFLX) is the direct SVOD competitor. Netflix trades at a trailing P/E of 28 with 29.5% operating margins and 2026 revenue guidance of $51 to $51.4 billion. Disney’s 13 forward P/E is roughly half that multiple, making our target conservative given Disney’s diversified cash streams beyond streaming.
Comcast (NASDAQ:CMCSA) is the closest theme-park and studio comparable. Comcast’s Q2 saw Theme Parks EBITDA decline 5.1% and Peacock reach quarterly profitability at $189 million EBITDA, while Disney’s Experiences OI grew 20% and combined SVOD OI more than doubled. On execution across the same categories, Disney outperforms across the same categories, supporting the model’s constructive stance.
| Company | Forward P/E | Recent Segment Signal |
|---|---|---|
| Disney | 13 | Experiences OI +20% |
| Netflix | n/a | Op margin 33%+ |
| Comcast | n/a | Theme Parks EBITDA -5.1% |
Disney Price Prediction 2026-2030
The 24/7 Wall St. price target is $113.82, the recommendation is buy, and confidence is 90%. The operating cash flow of at least $19 billion funding a $9 billion buyback tips the scale.
Key catalysts to watch include whether Sports OI stabilizes into FY27 and whether SVOD margins hold their double-digit path. Risks to monitor include Asia parks weakness spreading to domestic Experiences or sports rights inflation forcing another guidance reset.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $113.82 |
| 2027 | $122 |
| 2028 | $132 |
| 2029 | $141 |
| 2030 | $150.48 |
These projections assume Disney executes on its streaming-plus-Experiences flywheel and delivers FY27 double-digit EPS growth. Meaningful upside or downside could come from sports rights economics, park cycle risk, or Disney+ international scale acceleration.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.