Johnson & Johnson vs AbbVie: Safe Dividend vs Higher Yield
Two healthcare giants, two very different dividend bets: one built on six decades of unbroken raises and a fortress balance sheet, the other dangling a fatter yield while racing to outrun its own blockbuster's collapse. Knowing which risk you are…

Johnson & Johnson (NYSE:JNJ | JNJ Price Prediction) and AbbVie (NYSE:ABBV) both delivered strong quarters, but they tell very different dividend stories.
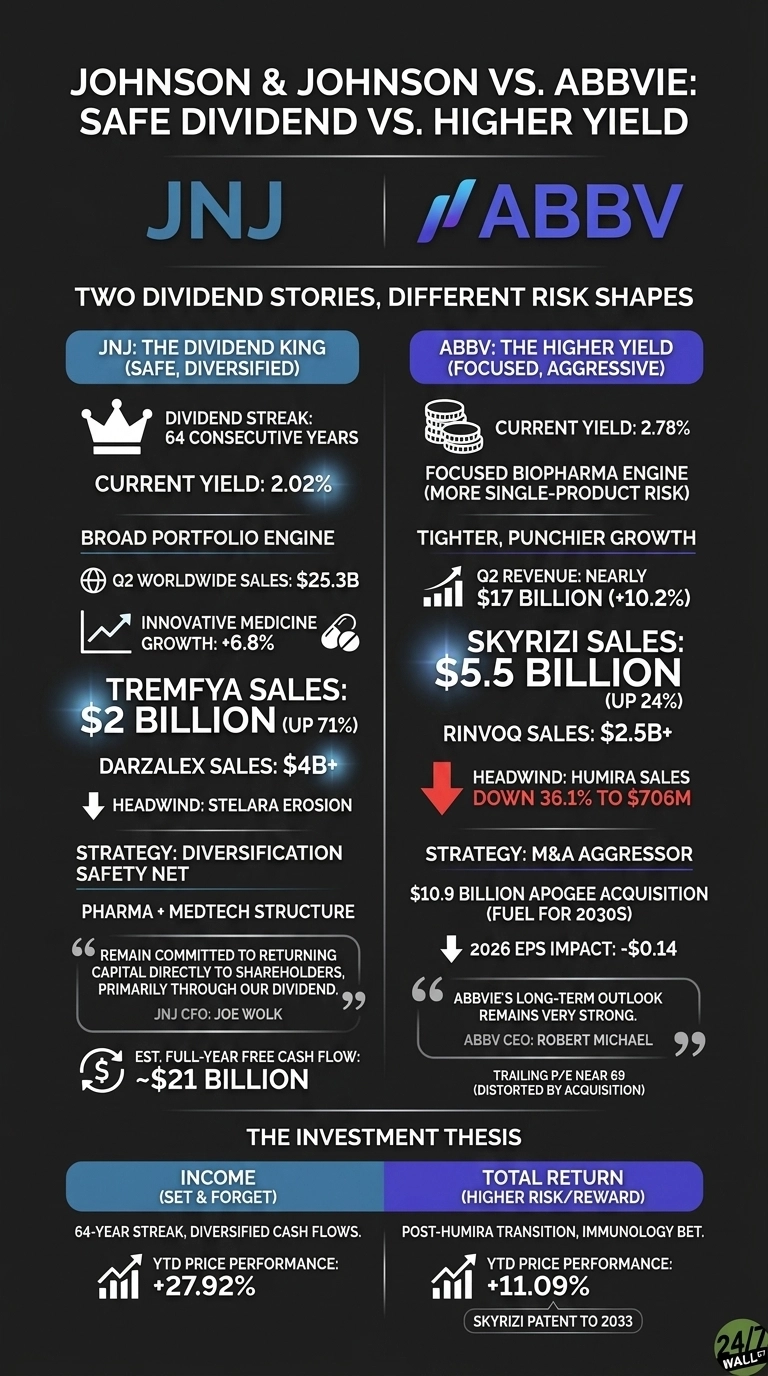
J&J is a Dividend King with 64 consecutive years of raises and a 2.02% yield. AbbVie pays a fatter 2.78%, funded by a narrower biopharma engine that carries more single-product risk.
Two Portfolios, Two Very Different Risk Shapes
J&J’s Q2 earnings report was broad. Worldwide sales hit $25.3 billion, with Innovative Medicine growing 6.8% and TREMFYA crossing $2 billion in a single quarter for the first time, up 71%. DARZALEX pushed past $4 billion. New launches ICOTYDE and INLEXZO are gaining share fast, which matters because STELARA is still bleeding to biosimilars.

AbbVie’s quarter was tighter but punchier. Revenue reached nearly $17 billion, up 10.2%, with Skyrizi at $5.5 billion (up 24%) and Rinvoq above $2.5 billion. Humira, meanwhile, fell 36.1% to $706 million. The math still works, but the concentration in immunology is real.

| Business Driver | JNJ | ABBV |
| Top Growth Product | TREMFYA (up 71%) | Skyrizi (up 24%) |
| Biggest Headwind | STELARA erosion | Humira erosion |
| Diversification | Pharma plus MedTech | Pure-play biopharma |
A Dividend King vs. an M&A Aggressor
J&J CEO Joaquin Duato called the company “one of the most compelling and transparent growth stories in healthcare today,” and he pointed to 28 products and platforms each doing more than $1 billion. That is the diversification safety net income investors pay up for.
CFO Joe Wolk was blunt about capital priorities: “We also remain committed to returning capital directly to shareholders, primarily through our dividend.” Free cash flow is tracking to roughly $21 billion for the year.

AbbVie is playing offense. Management just announced the $10.9 billion Apogee Therapeutics deal, adding long-acting biologics for atopic dermatitis and respiratory disease. That deal alone knocks $0.14 off 2026 EPS.
CEO Robert Michael framed it as fuel for the 2030s: “AbbVie’s long-term outlook remains very strong.” The tradeoff is a book value that is already negative and a trailing P/E near 69, distorted by acquisition accounting.
The Next Test Is Post-Humira Durability
For J&J, I want to see whether ICOTYDE and INLEXZO keep outrunning competitor launches, and whether the mid-2027 DePuy Synthes separation actually lifts the multiple. Cardiovascular growth of 3.1% was soft, so Abiomed needs to stabilize.
For AbbVie, the Skyrizi subcutaneous Crohn’s decision this fall and Tevapadon’s Parkinson’s launch will matter more than the headline yield. Skyrizi’s composition-of-matter patent runs to 2033, so the cliff conversation is not urgent, but it is on the calendar.
Why I Lean Toward J&J for Income, ABBV for Total Return
If I want a dividend I can forget about, J&J wins. The 64-year streak, AAA-rated balance sheet, and diversified cash flows do the heavy lifting. The yield is modest, but so is the risk of a cut. Shares are also up 27.92% year to date, so the safety trade has already paid.
If I want more yield and I am willing to underwrite Skyrizi, Rinvoq, and the Apogee bet, AbbVie is the more interesting name. The 11.09% YTD gain lags J&J, but a successful post-Humira transition could re-rate the stock. I would own it because I believe in the immunology franchise, not for the dividend alone. That is a different bet than J&J, and readers should treat it that way.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.