Price Prediction: Alphabet’s Next Rally Could Take It to $450 on This Date
Alphabet has beaten earnings estimates in every single quarter on record, yet one specific risk nearly derailed its last report despite a triple-digit EPS surprise. Here is why the next earnings date could be the most consequential moment for GOOG…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
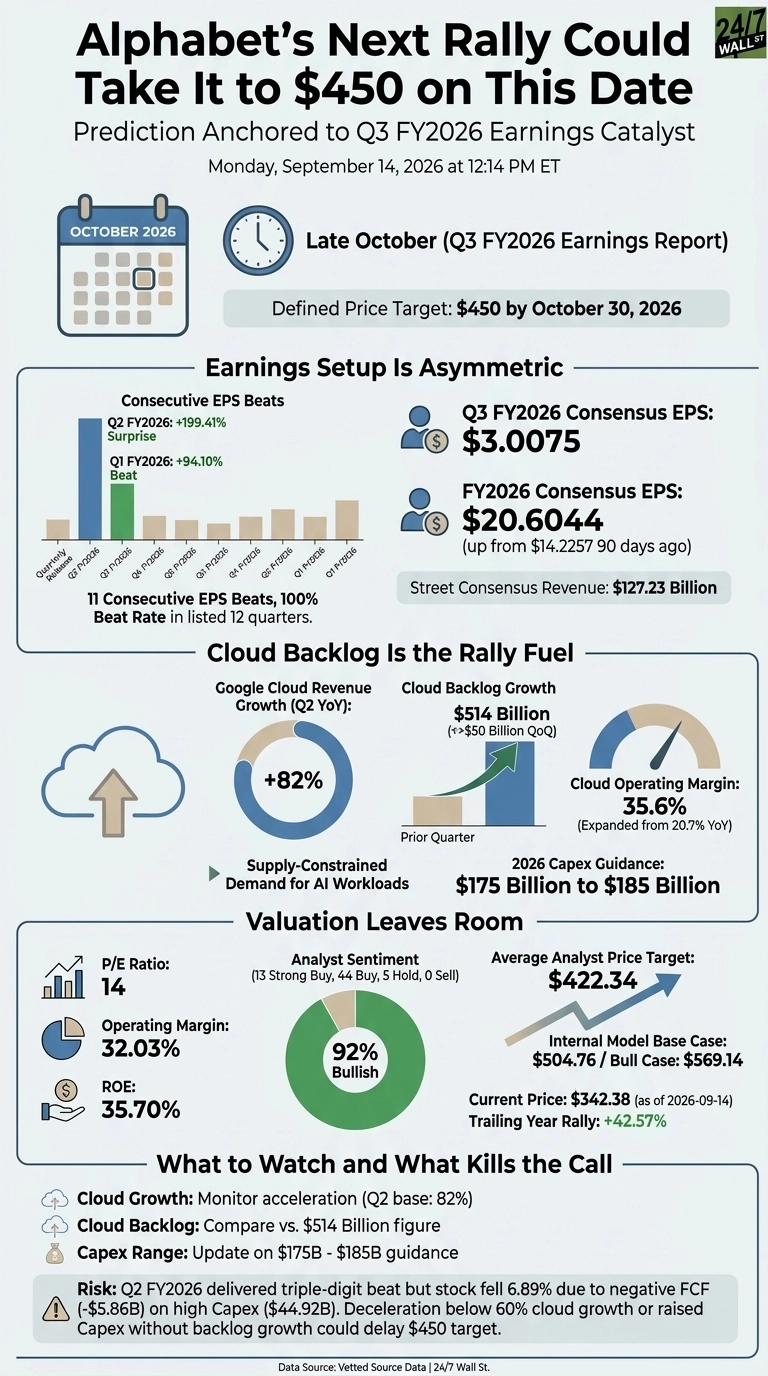
Alphabet (NASDAQ:GOOG | GOOG Price Prediction) will trade at or above $450 by the close on Friday, October 30, 2026, the first full session after its Q3 FY2026 earnings report scheduled for October 28, 2026, after market close.
From today’s $342.38, that is a defined move on a defined date, anchored to the single most consequential binary event on Alphabet’s near-term calendar.
Earnings Setup Is Asymmetric
Alphabet has posted 11 consecutive EPS beats and beat in every one of the 12 listed quarterly releases. Q2 FY2026 delivered EPS of $9.11 versus $3.04 consensus, a 199.41% surprise, and Q1 FY2026 came in at $5.11 versus $2.63, a 94.10% beat.
Street consensus for the September quarter sits at $3.0075 EPS on revenue of $127.23 billion, and estimate revisions are running hot: the FY2026 EPS consensus stands at $20.6044, up from $14.2257 ninety days ago. That is a wholesale re-rating of the earnings power going into a report the market has repeatedly underestimated.

Cloud Backlog Is the Rally Fuel
Google Cloud grew 82% year-over-year to $24.77 billion in Q2, with backlog reaching $514 billion, a sequential increase of more than $50 billion. Cloud operating margin expanded to 35.6% from 20.7% a year earlier, and management has stated it remains supply-constrained across external and internal AI workloads.
TPU systems began generating recognized revenue in Q2 and are set to ramp as Alphabet exits 2026. Alphabet has already guided 2026 capex to $175 billion to $185 billion, and the Q3 earnings report is the first look at how that spend converts into billable capacity.
All of that hyperscaler spend has to be powered, cooled, and networked by someone, and we profiled seven of the suppliers riding that same wave in a free report on the AI infrastructure buildout.

Valuation Leaves Room
GOOG trades at a P/E of 14 against 32.03% operating margins and 35.70% ROE. Analyst coverage skews decisively bullish: 13 strong buy, 44 buy, 5 hold, zero sell, with sentiment at 92% bullish and an average target of $422.34.

The internal weighted model prints a one-year base case of $504.76 and a bull case of $569.14. A $450 close in six weeks sits below both, and the stock has already rallied 42.57% over the trailing year. The Q3 25 report produced a 12.1% thirty-day gain; a similar reaction off this base clears the target.

What to Watch and What Kills the Call
Investors should key on three lines in the October release: Google Cloud year-over-year growth (the accelerating 82% base is the anchor), the Cloud backlog figure versus $514 billion, and any update to the $175 billion to $185 billion capex range.
The risk is real: Q2 FY2026 delivered a triple-digit beat and the stock still closed down 6.89% on the day as free cash flow ran to negative $5.86 billion on $44.92 billion of quarterly capex. If Cloud growth decelerates below 60% or capex guidance is raised without a matched backlog figure, $450 slips into 2027. Weighing the setup, the estimate momentum, and the backlog, the call stands: $450 by October 30.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.