The Biggest Catalyst for Alphabet Stock May Not Be Search
Alphabet's Search dominance built the empire, but a fast-moving segment now dwarfs it in growth rate and commands a backlog larger than the company's entire annual revenue. Here is what that shift means for where the stock goes next.

Alphabet’s second-quarter results made one thing clear: Google Cloud is no longer the sidekick to Search. Cloud revenue grew 82% to $24.8 billion, and backlog jumped more than $50 billion sequentially to $514 billion.
That backlog alone is larger than Alphabet’s entire fiscal 2025 revenue base. If you are hunting for the next leg of upside in Google (NASDAQ:GOOG | GOOG Price Prediction), Search is the foundation, but Cloud and enterprise AI look like the real accelerant.
Our 24/7 Wall St. price target for Alphabet is $504.76, implying 50.47% upside from a current price of $335.45. The recommendation is buy, with a model confidence of 90%. Below, I walk through how we got there and what could push the stock even higher, or pull it back.
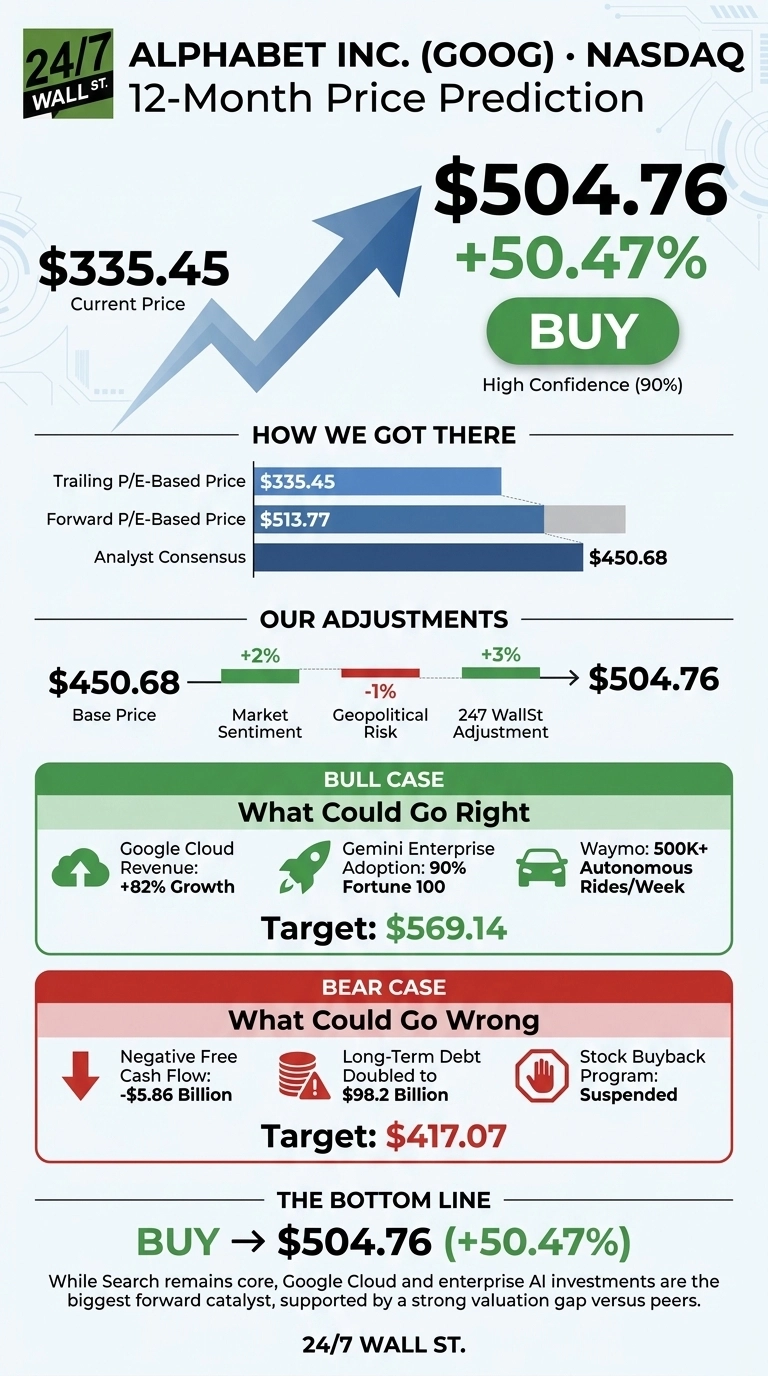
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $335.45 |
| 24/7 Wall St. Price Target | $504.76 |
| Upside | 50.47% |
| Recommendation | BUY |
| Confidence Level | 90% |

Cloud Acceleration Is Rewriting the Alphabet Story
GOOG is up 42.62% over the past year and 9.36% year to date, with shares recently changing hands near $342.50.
Q2 2026 was the anchor: EPS of $9.11 blew past the $3.04 consensus, revenue hit $119.8 billion, up 24.23% year over year, and operating margin expanded to 34%. Cloud growth accelerated from 48% in Q4 2025 to 63% in Q1 2026 and 82% in Q2 2026.
Barron’s noted this week that Google and Meta are emerging as winners from the latest round of AI concerns, thanks in part to their internal model economics.

Bull Case: $569 and Beyond
The bull scenario in our model points to $569.14, and it hinges on Cloud. Nearly 90% of the Fortune 100 use Gemini Enterprise, Gemini App has 950 million monthly active users, and model APIs process 22 billion tokens per minute, up from 16 billion a quarter ago.
Alphabet expects to recognize just over 50% of the $514 billion backlog within 24 months, and TPU system revenue is expected to ramp largely in 2027. Add Waymo scaling to 500,000+ autonomous rides per week and a YouTube run rate above $60 billion, and the non-Search catalysts stack up quickly.

What Could Go Wrong
The bear scenario lands at $417.07, still above today’s price. The risks are real: Q2 capex of $44.9 billion doubled year over year, free cash flow swung negative to -$5.86 billion, long-term debt roughly doubled from $46.5 billion to $98.2 billion, and buybacks are suspended.
It should be noted, however, that bulls would argue the capex surge reflects supply-constrained demand rather than misallocation (all that spending flows to the power, cooling, and networking companies we profiled in a free AI infrastructure report).
Management is still describing itself as supply constrained, and cloud operating income more than tripled to $8.8 billion with margins climbing to 35.6%.
How Alphabet Compares to Microsoft and Amazon
Microsoft (NASDAQ:MSFT) is the natural cloud-and-AI comp. Azure just surpassed $100 billion in annual revenue, Azure grew 43% in fiscal Q4 2026, and commercial RPO reached $678 billion. Yet MSFT trades at a P/E of 28 versus GOOG’s 14. Google Cloud is growing faster (82% vs. 43%) at roughly half the multiple, which is precisely why our target looks conservative rather than aggressive.
Amazon (NASDAQ:AMZN) is the other AI infrastructure spender. AWS grew 37% to $42.2 billion in Q2 2026 with a 39.4% operating margin, and Andy Jassy guided to roughly $200 billion in 2026 capex. AMZN trades at a P/E of 36.
Google Cloud is now growing more than twice as fast as AWS while GOOG trades at less than half the earnings multiple. That valuation gap is the single strongest support for our 24/7 Wall St. price target.
| Company | P/E | Cloud Growth (latest Q) |
|---|---|---|
| Alphabet | 14 | 82% |
| Microsoft | 28 | 43% |
| Amazon | 36 | 37% |
Why I’d Own It Here
My take: the 24/7 Wall St. price target of $504.76 with 90% confidence is a buy, and the tipping factor is the valuation gap versus MSFT and AMZN despite superior cloud growth. The setup strengthens if free cash flow stabilizes as 2027 TPU revenue ramps.
The thesis weakens if capex keeps climbing without margin follow-through in Cloud. Prediction markets are more cautious, pricing a 0.815 probability that shares hit $350 in September, but the 12-month setup is materially more constructive.
Looking further out, our model projects the following trajectory, assuming Cloud growth normalizes gradually and Search remains resilient.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $377.79 |
| 2027 | $514.71 |
| 2028 | $653.64 |
| 2029 | $817.33 |
| 2030 | $940.70 |
These projections assume Alphabet keeps executing on its full-stack AI strategy. Significant upside or downside could come from Gemini 4, TPU monetization in 2027, or an adverse regulatory outcome tied to Search.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.