Boeing’s $36.2 Billion Korean Air Deal Won’t Help Earnings Until the 2030s
Korean Air just signed a $36.2 billion Boeing commitment stretching well into the next decade, but a record backlog and blockbuster headline numbers tell only part of the story for a manufacturer still racing to prove it can actually deliver.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
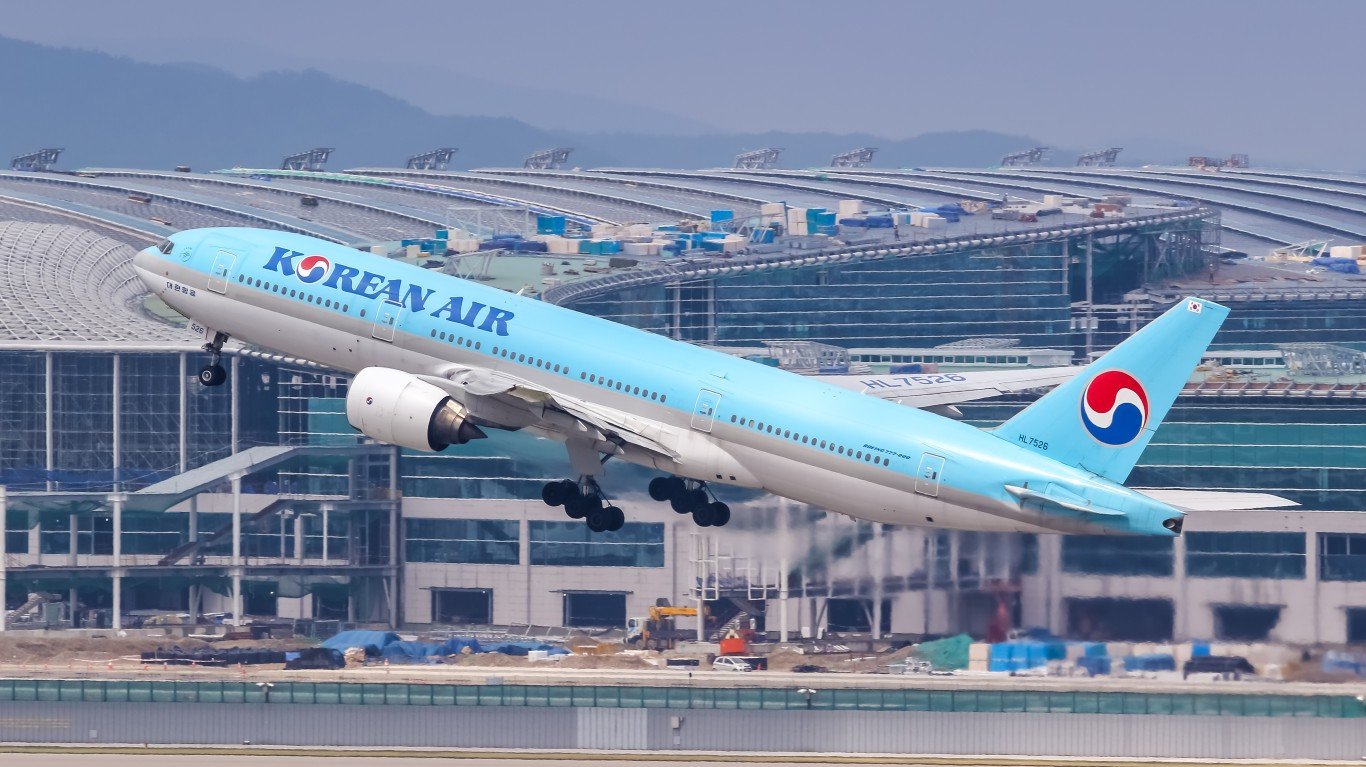
Boeing (NYSE:BA | BA Price Prediction) confirmed a firm Korean Air order for the stretched 737 MAX, 787-10, and 777X in passenger and freighter variants, valued at $36.2 billion. Deliveries begin in the early 2030s.
These aircraft were previously logged as unidentified orders from a commitment announced last summer, so this is existing backlog getting a customer name rather than fresh demand.
Boeing’s commercial backlog already exceeds 6,200 aircraft valued at a record $597 billion, within a total company backlog of $715 billion. The stock is down 11.66% over the past month and 9.24% year to date, sliding after CEO Kelly Ortberg conceded this week that stabilizing 737 MAX output is taking longer than expected.

When the Cash Actually Moves
Order deposits and progress payments trickle in during the build cycle, with the largest chunk landing at delivery. That timing is why a headline order value takes years to show up in reported results.
Boeing’s Q2 2026 free cash flow of $631 million was tied to delivering 171 airplanes. CFO Jay Malabe calls “$10 billion” of annual free cash flow “very attainable” as the backlog converts.
Recognized revenue was $24.56 billion in the quarter, with a core loss per share of $0.76 against a $0.34 consensus loss. Deliveries close that gap.

What Could Slip the Schedule
Three variables decide whether the early-2030s window holds: certification of the 737-10, entry into service for the 777X, and factory output. The 737-10 is targeted for certification in 2026 with first deliveries in 2027. The 777X is expected to make its first delivery in 2027 after a $4.9 billion pre-tax charge in Q3 2025.
The 737 line is transitioning to 47 per month before a planned break to 52. Ortberg says he sees “a solid plan through 57 and more work to do after that.”
Airbus, running its own multi-year backlog on the A320neo and A350, is why Korean Air cannot simply defect if Boeing misses. Lockheed Martin (NYSE:LMT) has kept posting steady profits while Boeing burns cash lifting rates, a reminder that scale alone does not print earnings.
Korean Air is locking a flag carrier to Boeing metal for a decade and adding freighter demand, which shores up 777X credibility even though it will not touch 2026 results. The commitment also validates Boeing’s widebody roadmap at a moment when execution credibility is fragile.
Bull and Bear Case for BA Stock

Bulls see a duopoly participant with a record backlog and improving cash generation. If 737 rates climb and the 777X enters service in 2027, the path to double-digit-billion free cash flow becomes concrete.
Bears point to a market cap near $155.74 billion resting on execution Boeing has repeatedly missed, with quarterly interest expense of $600 million and fresh VC-25B charges of $280 million weighing on GAAP results. The 737 ramp and 777X certification will decide the outcome.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.