“Delayed Isn’t as Good”: Why Boeing’s $10 Billion Cash Flow Target Just Got More Expensive
Boeing's CEO admitted MAX production stabilization is running behind schedule, and the market punished shares instantly. But the more brutal math has nothing to do with the factory floor and everything to do with what a delay now costs investors…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Boeing (NYSE:BA | BA Price Prediction) shares fell about 3.64% on Wednesday after CEO Kelly Ortberg told a Morgan Stanley Laguna Conference audience that stabilizing 737 MAX production is taking “a little bit longer” than planned, while reiterating that output rises next year. The modest admission produced an outsized reaction, and the gap between the two is the story.
Boeing has given back roughly 10.58% over the trailing month and closed near $202.05, well below its 200-day moving average of $220.89. Management still guides to $1 to $3 billion of free cash flow for 2026 and calls the long-term $10 billion free cash flow figure “very attainable”. What changed is the discount rate applied to that trajectory. With the 10-year Treasury at 5.00%, a payoff that arrives later is worth measurably less in present-value terms, and the market repriced accordingly.

What Ortberg Actually Told Investors
Ortberg said stabilizing MAX rates is taking longer than planned, though Boeing expects to increase plane output next year. Rate stabilization matters because aircraft margins depend on absorbing fixed costs and converting older, worse-priced backlog into deliveries.
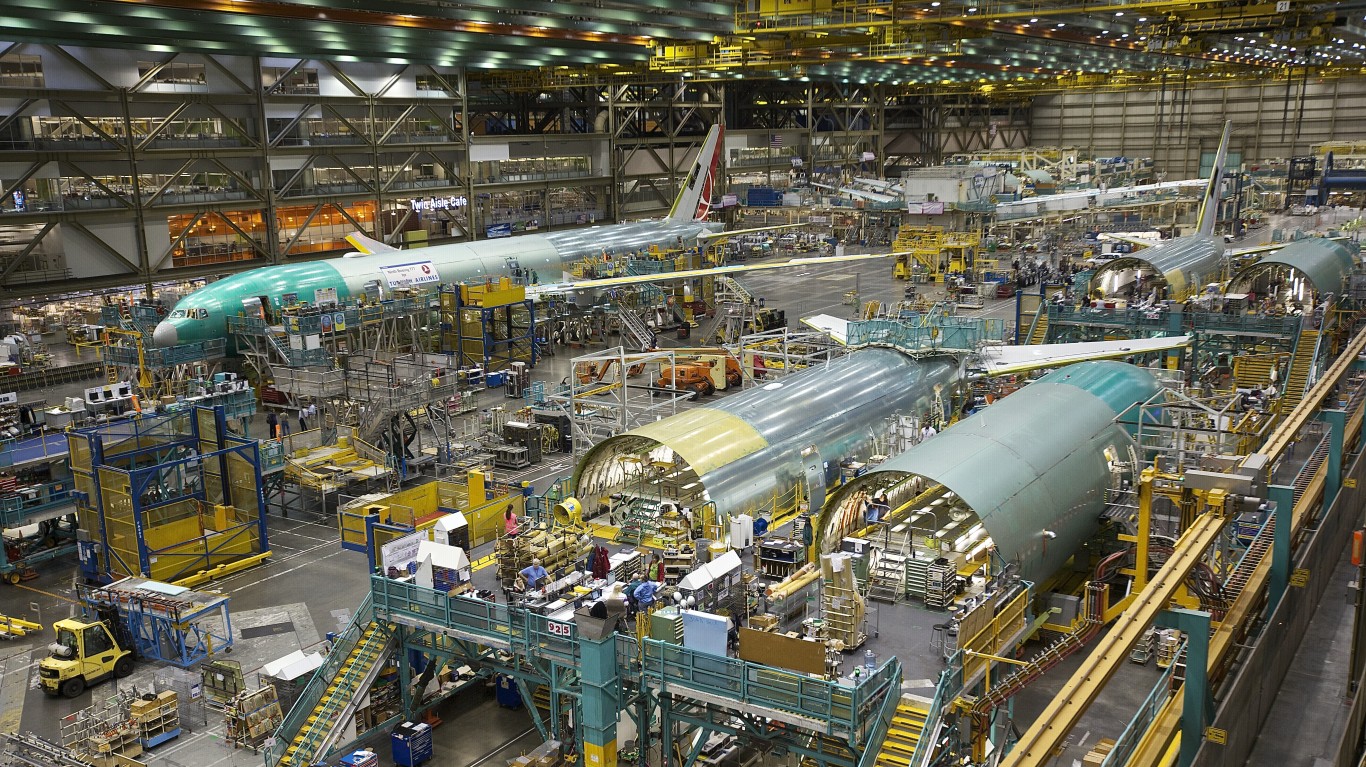
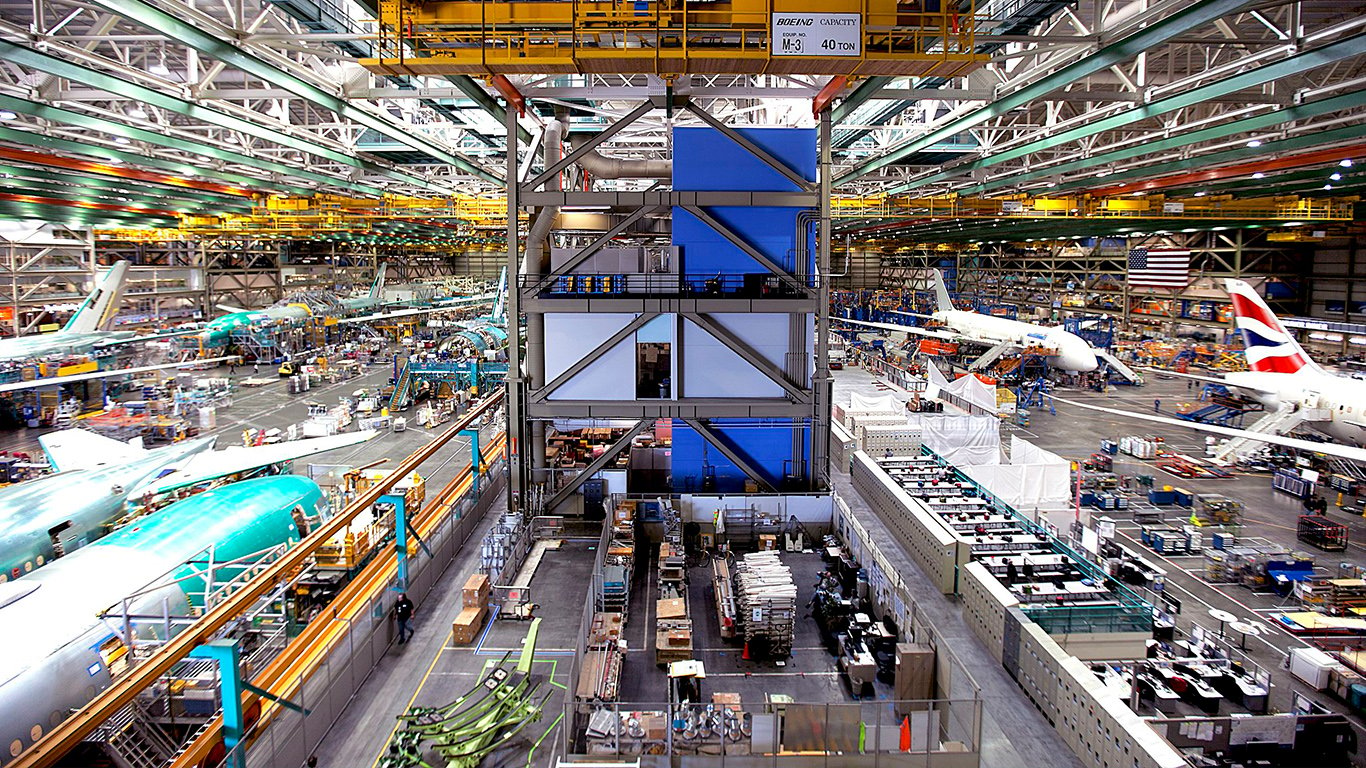
Boeing is ramping to 47 airplanes per month on the 737, with a rate break to 52 in view. The FAA controls the pace, so a slip signals the production system’s capability.
The 787 line is already stabilized at eight airplanes per month, which is the model for what management wants the MAX line to achieve. Until the MAX gets there, the cash conversion engine runs at half speed.
Why Delays Carry Real Cost
The bull case has always been free cash flow conversion once deliveries normalize. Q2 2026 delivered positive free cash flow of $631 million, the first meaningful proof point, on the highest quarterly delivery total since 2018.

On CNBC’s Fast Money Wednesday, trader Karen Finerman said the situation is “delayed. So I don’t think it’ll be denied. But delayed isn’t as good.” That framing captures the market’s read on the delay.
With the 10-year yield at a 99.6 percentile rank over the past year, discounting billions of dollars of cash flow from 2028 or 2029 back to today is materially harsher than when Boeing first laid out the plan. The destination is unchanged. The route is longer, and patience has gotten more expensive.
Backlog is still the real asset.
Boeing ended Q2 with a record total backlog of $715 billion, including a commercial backlog of over 6,200 aircraft valued at $597 billion. The quarter added 246 net commercial orders from major carriers and lessors, and management pointed to a market outlook of nearly 44,000 new aircraft over the next 20 years.
Frustrated demand does not migrate cleanly to Airbus, because the duopoly’s other half is also capacity constrained. The stock trades in a range rather than freefall because the backlog is real and buyers still line up for slots Boeing cannot yet build.
Bull and Bear Case for BA Stock
The bull case is straightforward. A committed multi-year backlog, a duopoly market structure, and a first genuine positive free cash flow print give Ortberg a credible path to the $10 billion figure, and analyst consensus reflects that with a target price of $274.85.

The bear case is the pattern. The 777X first delivery has moved to 2027, the VC-25B took another $280 million charge and slips to 2028, and MAX rate stabilization has been extended again. Boeing missed Q2 consensus by $0.42 per share, and the forward multiple of 52x already prices in much of the recovery that keeps arriving late.

The deciding variable is whether the next stabilization target holds. Investors can verify the reported cash flow trajectory in Boeing’s Q2 2026 8-K exhibit, but the FAA sets the ramp, and that is the one input the CEO cannot promise.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.