Price Prediction: Seagate Stock Will Trade at $900 on This Date
Seagate's next earnings date is circled on the calendar for a reason, and the setup behind this price call is harder to dismiss than most. One specific catalyst makes the timing anything but arbitrary.


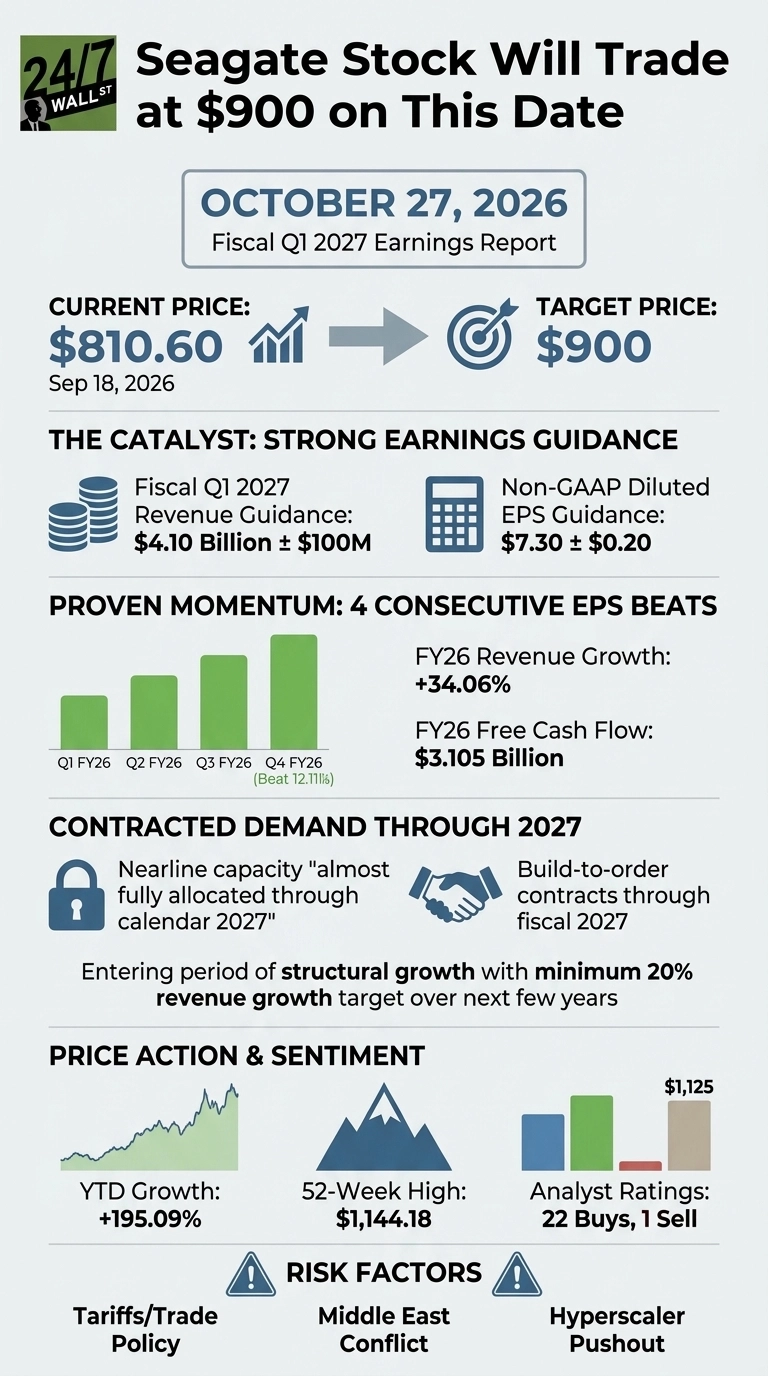
Seagate Technology (NASDAQ:STX | STX Price Prediction) will trade at $900 per share on October 27, 2026, the day the company is scheduled to release fiscal Q1 2027 earnings after the close. From a last print of $810.60, that is roughly an 11% move over five weeks, anchored to a catalyst the company has effectively pre-announced.

Guidance Sets a Floor Under Earnings
Management guided fiscal Q1 2027 revenue to $4.10 billion, plus or minus $100 million, with non-GAAP diluted EPS of $7.30, plus or minus $0.20.
Seagate has now delivered four consecutive quarters of EPS beats, most recently posting $5.71 against a $5.09 consensus in Q4 FY26. The company also grew fiscal 2026 revenue 34.06% and generated $3.105 billion in free cash flow. A fifth straight beat against a raised bar is the base case.

Demand Is Contracted Through 2027
On the April 28, 2026 call, management said nearline capacity is “almost fully allocated through calendar 2027” and that build-to-order contracts are being finalized “through the end of fiscal 2027” with defined configuration and pricing.
Mosaic 4 shipped for revenue in late March and is expected to represent a majority of HAMR exabyte shipments exiting calendar 2026. CEO Dave Mosley told investors Seagate is “now entering a period of structural growth” and raised the multi-year revenue growth target to “a minimum of 20% over the next few years.”
That is contracted exabyte demand from hyperscalers (Seagate is one of several non-chip suppliers cashing in on the AI data-center buildout, a group we profiled in a free report on seven AI infrastructure names).

Price Action Has Already Kissed the Target
STX traded at $903.68 on August 18, 2026, before pulling back 10.3% over the past month. Year to date, shares are up 195.09%. The 52-week high sits at $1,144.18, and the Street carries 22 buys against one sell with an analyst target of $1,125.
Composite sentiment reads 64.98, bullish with medium confidence. An earnings report in line with guidance reclaims the August highs; a beat on the $7.30 EPS midpoint takes shares through $900.

Risk Check
If tariffs, the Middle East conflict, or a hyperscaler pushout breaks the four-quarter beat streak, $900 breaks with it, and shares retest the August low. Management flagged those exact risks in guidance assuming minimal tariff and Middle East conflict impact.
Even so, with nearline capacity already sold through calendar 2027 and a $7.30 EPS anchor from management itself, Seagate prints $900 on October 27, 2026.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.