What Will $5,000 Invested in Nvidia Stock Be Worth in 5 Years?
Nvidia sits at the center of the AI infrastructure boom, but a five-year hold on a modest stake could end up anywhere from a modest gain to a life-changing return depending on which forces win out.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) sits at the center of every serious AI infrastructure conversation, and a five-year hold naturally raises the question of what a modest stake could compound into.
With shares changing hands at $218.29 and the modeled five-year path anchored to a base target of $532.58, a $5,000 investment made today has a defined range of outcomes worth walking through. Treat the figures as a modeled projection for research purposes only.
Base Case: What $5,000 Could Become by 2031
Lead with the number that matters. Under the base case, a $5,000 stake in NVDA could be worth about $12,199 by 2031-09-12, a total return of 143.98% over the window.
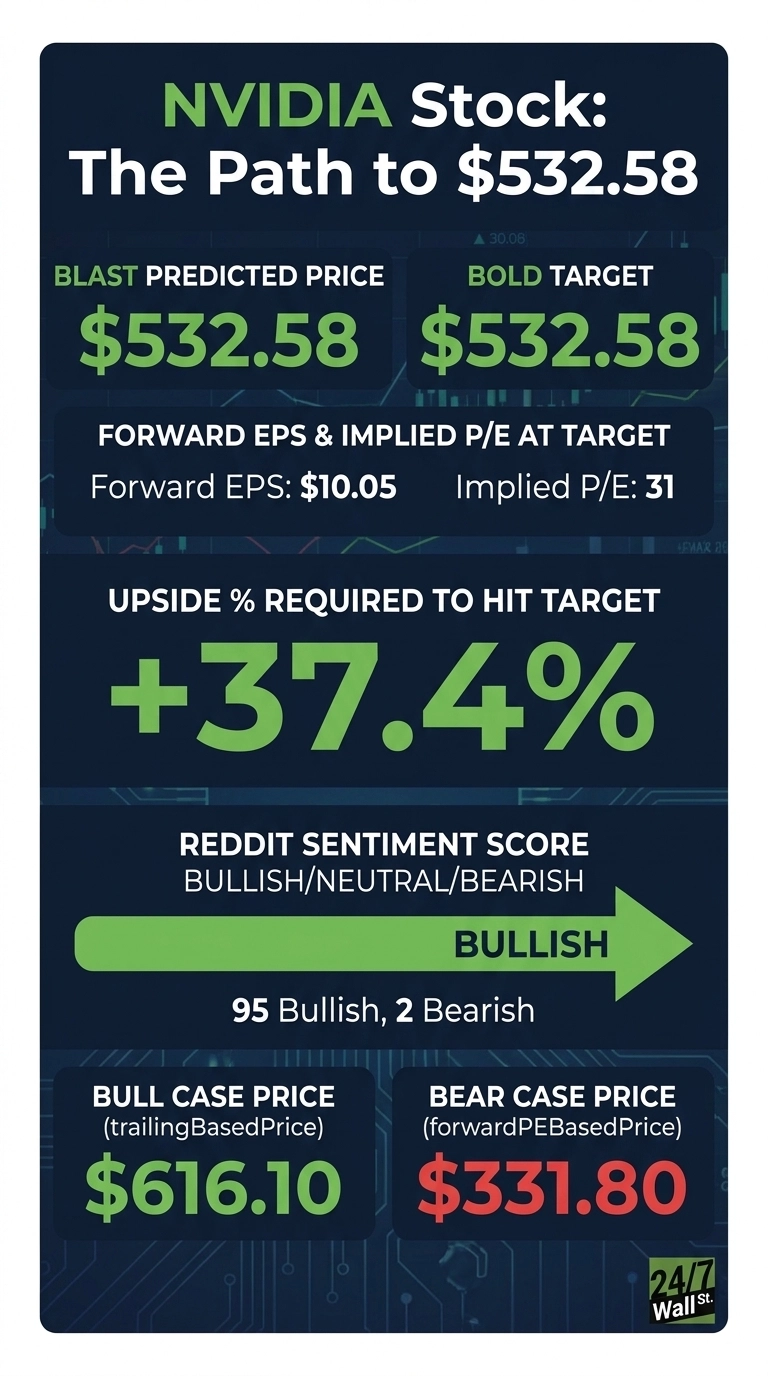
That figure is anchored to a per-share target of $532.58, implying an annualized return of 19.53%. The model rates confidence on the setup at 0.9, with a buy recommendation reflecting 37.4% upside to the one-year base target.
Five-Year Scenario Table for a $5,000 Stake
| Scenario | Target Price (2031) | Total Return | Ending Value of $5,000 |
|---|---|---|---|
| Bull | $616.10 | 182.24% | $14,112 |
| Base | $532.58 | 143.98% | $12,199 |
| Bear | $331.80 | 52% | $7,600 |
For context on the Street’s near-term view, the analyst consensus target is $327.65, drawn from 9 Strong Buy, 48 Buy, 2 Hold and 1 Sell ratings. Analyst bullish sentiment sits at 95 versus bearish sentiment of 2.

Why the Targets Land Where They Do
The base target reflects a weighted blend of trailing P/E, forward P/E and the analyst consensus, adjusted by a proprietary 247Factor that layers in sector momentum, earnings acceleration and social sentiment. Forward EPS in the model is $10.05, with an implied forward multiple of roughly 31.

The fundamental backdrop is unusually strong for a company this size. Q2 FY27 revenue came in at $96.22B, up 105.8% YoY, and Data Center revenue reached $89.02B, up 117% YoY.
Q3 revenue is guided to $108B ±2%, and management expects revenue to grow by approximately 70% in fiscal 2028, characterizing the outlook as “a supply-constrained outlook.”
Three drivers reinforce the multi-year setup:
- Vera Rubin economics. The revenue opportunity per gigawatt has scaled from $18 billion with Hopper to $25 billion with Blackwell to $40 billion with Vera Rubin, which management expects to be the fastest product ramp in company history.
- Hyperscaler capex trajectory. Top-five hyperscaler capex is expected to reach nearly $800 billion in 2026 and $1.3 trillion in 2027, against a cloud-industry backlog described as greater than $2 trillion.
- Ecosystem financing flywheel. Partnerships with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR are expected to mobilize over $500B for AI infrastructure, alongside OpenAI’s roughly 12 gigawatts of NVIDIA compute committed through 2030.
CEO Jensen Huang framed the moment plainly on the last earnings call: “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue.”
The buildout also lifts a wider set of suppliers, from power to cooling to networking, that sit alongside the GPU maker itself (we profiled seven of them in a free report you can grab here).
What Could Sink the Projection
The bear path to $331.80 assumes a materially slower AI capex cycle. Real risks include export-control overhang (management stated “there is no China data center compute revenue in our forward outlook”), dependence on TSMC and third parties for packaging, and $279B in supply commitments plus $108.5B in guarantee obligations that could bite if AI demand cools.
Custom silicon from cloud customers, extreme memory pricing (Q4 gross margin is guided to bottom in the 71% to 72% range) and NVDA’s beta of 2.217 all argue for a wide outcome band.
Historical results are not predictive either way: NVDA is up 875.38% over the trailing five years, and repeating that would require a very different starting valuation.
Bottom Line on the $5,000 Question
Anchored to the modeled five-year horizon ending 2031-09-12, a $5,000 NVDA stake sits within a projected range of roughly $7,600 in the bear case to $14,112 in the bull case, with a base outcome near $12,199.
Those numbers rest on continued AI infrastructure buildout, successful Vera Rubin execution and a supply chain that can catch up to demand. Treat this as a scenario framework with no guaranteed outcome; the wide gap between the bull and bear paths reflects how much still depends on the next few product cycles.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.