SoFi Technologies Bombed by More Than 40% in 1 Year: A Wall Street Pro Just Reiterated His Belief That Shares Will Double in 12 Months
SoFi's stock sits just above a 52-week low while one Citigroup analyst refuses to budge from a target that would nearly double your money, even as half of Wall Street rates the digital bank a Hold.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
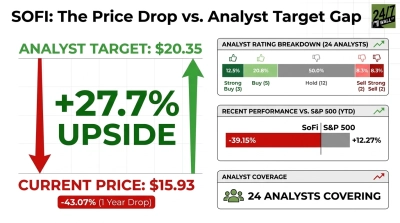
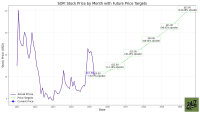
SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) currently trades at $15.93. The average analyst price target is $20.35, which implies 27.7% upside.
SoFi is a nationally chartered digital bank offering personal, student and home loans, checking, investing, credit cards and crypto through one app, plus the Galileo technology platform. Membership reached 15.8 million, up 35% year over year. Yet the stock has fallen 43.07% over the past year.
The gap matters because one bull has stayed put. Citigroup (NYSE:C) analyst Peter Christiansen maintained a Buy rating with a $30.00 target. That target implies 88.3% upside, so it sits close to a double.
Profit Guidance Stalled as Rate Cuts Turned Into Rate Hikes
Earnings power stalled as revenue sped up. SoFi raised full-year adjusted net revenue guidance to $4.75 to $4.85 billion but held adjusted EPS at roughly 60 cents. The tax rate came in at 22%, roughly 700 basis points above plan, and management reinvested gains instead of lifting EBITDA guidance. Management also models one to two hikes in 2026. The original plan assumed two cuts, which hurts a lender whose loan fair values move with benchmark rates.
Shares traded at $29.505 around Q3 2025, $22.94 at Q4, $18.47 at Q1 and $16.75 at Q2. Technology Platform revenue fell 23% after a large client left. Estimates for full-year 2026 EPS drew five cuts against two increases over 30 days. With a beta of 2.208, SoFi moves far more than the market in both directions.
Citi’s $30 Thesis Rests on Deposits and Cross-Selling
The bull case rests on three pillars: network effects lowering customer acquisition costs, Galileo and Technisys adding high-margin fee revenue, and cheap deposit funding widening margins. Deposits grew to $45.5 billion, saving an estimated $712.6 million annually versus warehouse funding. Net interest margin reached 5.98%, and loan originations hit a record $14.80 billion.
EPS of $0.12 beat the $0.11 estimate for the fifth straight beat. Revenue of $1.22B also exceeded expectations. Existing members opened 51% of new products, indicating cross-selling momentum. The CEO targeted 1 million SoFi Plus members generating $120 million annual revenue within 12 months.
Estimates are moving in the right direction too. The 2027 EPS consensus rose to $0.8240 from $0.8115 90 days ago, and the forward P/E is about 21. Still, Citi’s target is an outlier, since the consensus sits roughly $10 below it.
Upstart Fell Further, While Affirm Barely Slipped
Upstart (NASDAQ:UPST) has dropped 59.84% over the past year. At $23.03 against a $40 target, it implies 73.7% upside. Ratings break down to eight Buy or Strong Buy, six Hold and one Strong Sell, stronger than SoFi.
Affirm (NASDAQ:AFRM) is down only 11.6% over the year. At $67.21 against a $99.09 target, it implies 47.4% upside. Of 33 analysts, 24 rate it Buy or Strong Buy, and none rate it Sell.
On consensus targets, Upstart has the largest expected upside and SoFi the lowest. Only Citi’s $30 call puts SoFi near the top of the group.
A 39% Loss This Year While the S&P 500 Gained
SoFi trades at $15.93, compared with a $20.35 consensus target and expected upside of 27.7%. It sits just above its 52-week low of $14.88 and far below its high of $32.73. Shares have fallen 39.15% year to date and 11.79% over the past month. Over the same periods, the S&P 500 rose 12.27% year to date and 15.68% over the past year.
Here is how the 24 covering analysts rate the stock:
- Strong Buy: 3
- Buy: 5
- Hold: 12
- Sell: 2
- Strong Sell: 2
Half the coverage has a Hold rating, so Wall Street as a whole is far more cautious than Citi.
SoFi Looks Cheap, but Rates Will Decide the Rebound
SoFi looks cheap if deposit growth keeps net interest margin above management’s 5% floor, SoFi Plus moves toward 1 million members and the tax rate normalizes. If that happens, 2027 earnings power would make $30 reachable. But the risk grows if rate hikes hit loan valuations, credit losses rise or Technology Platform shrinks further. In that case, the Hold-heavy consensus would prove right.
The bull case looks more compelling. A company raising revenue guidance while trading just above its 52-week low offers a real margin of safety. Even so, the realistic target is the $20.35 consensus, and Citi’s near double is a periods goal.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.