5 Solid Dividend Stocks to Buy Now
Five dividend payers across four sectors promise to keep raising payouts through the next downturn, but one of them carries a GAAP payout ratio above 100% and a negative book value that would alarm most income investors at first glance.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

An income portfolio built inside one sector carries one set of risks. This basket spreads five dividend payers across four sectors: consumer staples with Coca-Cola (NYSE:KO | KO Price Prediction) and PepsiCo (NASDAQ:PEP), financials with JPMorgan Chase (NYSE:JPM), real estate with Realty Income (NYSE:O) and healthcare with AbbVie (NYSE:ABBV). The sections run by sector because the goal is diversity in a single basket, and each name is judged on the payout measure that fits its business. What ties them together is cash flow that keeps funding raises, and the latest proof arrived when JPMorgan declared a quarterly dividend of $1.65, up from $1.50, on September 15, 2026.
| Company | Sector | Dividend Yield | Forward Annual Dividend | Coverage Metric Used |
|---|---|---|---|---|
| Coca-Cola | Consumer Staples | 2.34% | $2.12 | Free cash flow |
| PepsiCo | Consumer Staples | 4.35% | $5.92 | Free cash flow conversion |
| JPMorgan Chase | Financials | 1.77% | $6.6 | Earnings and capital |
| Realty Income | Real Estate | 5.58% | $3.258 | AFFO |
| AbbVie | Healthcare | 2.58% | $6.92 | Adjusted (cash) earnings |
Coca-Cola: Consumer Staples Quality Anchor
Coca-Cola yields 2.34%, the second-lowest payout in this group. Its job in the basket is stability, and the cash math supports it. Management raised its 2026 free cash flow guidance to about $12.4 billion from $12.2 billion, built on roughly $14.6 billion of operating cash flow less about $2.2 billion of capital spending. The forward dividend of $2.12 per share falls well inside trailing EPS of $3.33.
The quarterly dividend rose to $0.53 in 2026 from $0.51 in 2025. The verified payment record shows a higher quarterly amount in every year from $0.28 in 2013 through today, with regular quarterly payments running back to 1999. Coca-Cola’s longer streak is part of its reputation, but the exact consecutive-year count falls outside the history verified for this piece, so the 13-plus years of documented raises is the claim that holds up here. Cash of $12.9 billion and a debt-to-equity ratio of 1.47 add buffer.
Bull case: Coca-Cola is compounding faster than a mature staple should. Second-quarter revenue rose 6.7% to $13.38 billion, adjusted EPS of $0.97 beat the $0.93 estimate, and global unit case volume grew 5% with Coca-Cola Zero Sugar up 16%. Management guides comparable EPS growth of 9-10% for 2026, and FIFA World Cup activation across 180+ markets gives volume another boost. Investors have noticed: shares are up 27.14% year to date at $87.18, against an analyst target of $94.7.
Risk: Valuation. At 26 times trailing earnings, investors pay a premium for a yield near 2%. If volume growth cools after the World Cup lift, the multiple has room to compress, and Asia Pacific price/mix already fell 9%. The fourth quarter also carries six fewer days than a year ago, along with the pending African bottler sale and ongoing IRS tax litigation.
PepsiCo: Staples Yield With a Verified Dividend King Streak
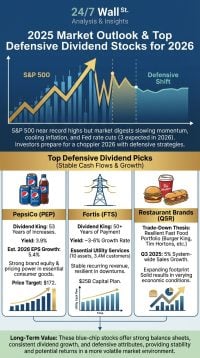
PepsiCo is the high-yield staple of the pair at 4.35%. The 4% hike that took effect with the June 2026 payment was, in management’s words, the 54th consecutive annual increase, which puts PepsiCo in Dividend King territory. The payment record supports the pattern: the quarterly dividend moved from $1.355 to $1.4225 to $1.48 over the last three raises, and it climbed from $0.13 in 1999 along the way.
Coverage is lower than Coca-Cola’s but still intact. The forward dividend of $5.92 compares with trailing EPS of $7.63. PepsiCo targets free cash flow conversion of at least 80% of net income with capex below 5% of net revenue, and it plans about $8.9 billion in 2026 cash returns, roughly $7.9 billion in dividends and $1.0 billion in buybacks. Leverage is the heavier of the two staples at a debt-to-equity ratio of 2.45, offset by $10.25 billion in cash.
Bull case: Shares are priced for disappointment while the business grinds higher. Shares are down 7.74% year to date and 7.93% over the past month at $128.5, trading at 15 times forward earnings. Meanwhile second-quarter revenue rose 6.4% to $24.18 billion, LatAm Foods grew 15% and EMEA grew 10%. Full-year guidance for 2-4% organic revenue growth and 4-6% core constant-currency EPS growth was confirmed. If North American snacks stabilize, the analyst target of $153.86 becomes a realistic re-rating path, and investors collect a 4%-plus yield while waiting.
Risk: Pricing pushback. PepsiCo plans to raise prices on sodas, chips and dip, and Wall Street is worried about the volume response. Frito-Lay North America revenue already fell 2% on weaker pricing and core operating margin contracted 40 bps. If shoppers trade down again, earnings growth slows and the dividend raise pace could shrink toward token increases.
JPMorgan Chase: Financials Payer With the Most Room to Raise
JPMorgan yields 1.77%, the lowest here, and that is the point. A low payout relative to earnings is what funds fast raises. Trailing dividends of $6 per share are a small portion of trailing EPS of $23.33. The newly declared $1.65 quarterly payment goes ex-dividend on October 6 and pays on October 31. The quarterly dividend stood at $1.05 in early 2024, so the bank has made five increases in under three years.
Capital is fortress-grade. The CET1 ratio stands at 14.3%, supports by $1.5 trillion in cash and marketable securities and a latest $50 billion buyback authorization effective July 1, 2026. One caveat on track record: JPMorgan cut its dividend during the 2009 financial crisis, so it carries no Aristocrat label. The growth rate since then is the income story.
Bull case: JPMorgan posted record revenue across every line of business in the second quarter. EPS of $7.70 beat the $5.80 consensus, and even stripping out a one-time equity-stake gain and other equity gains, adjusted EPS of $6.14 rose 13% with ROTCE of 23%. Investment banking fees rose 30%, loans grew 10% and deposits grew 7%. The asset management arm added a $20 billion strategic partnership with QIA on September 21. At 15 times trailing earnings and $336.75 per share, the stock trades below the $375.43 analyst target after a 4.39% slide over the past week.
Risk: Credit and cost creep. Card net charge-offs run at 3.33%, the total allowance for credit losses rose 12% to $31.4 billion, and noninterest expense climbed 15%. Dimon has flagged sticky inflation, geopolitical tensions and high asset prices. If a downturn hits trading and credit at the same time, buybacks slow first, and the dividend raise pace likely follows.
Realty Income: Real Estate Monthly Payer Judged on AFFO
Realty Income yields 5.58%, the highest payout in the basket and clearly high-yield, though still below a 6% threshold. Dividends arrive monthly. On September 8, it declared its 136th monthly dividend increase, lifting the monthly payment to $0.2715 from $0.271. That follows 115 consecutive quarterly increases and 670 consecutive monthly dividends as of its first-quarter report.
Earnings payout ratios mislead for REITs because depreciation on buildings drags GAAP net income well below the cash a landlord actually collects. That is why the trailing P/E of 41 looks extended. AFFO adds back that noncash depreciation and deducts recurring capital needs, making it the right yardstick. Realty Income raised 2026 AFFO guidance to $4.44-$4.45 per share, well clear of the forward annualized dividend of $3.258. Second-quarter AFFO of $1.09 rose 3.8%, and Fitch assigned an “A” issuer default rating, marking the outlook stable.
Bull case: A recent selloff made the income cheaper without breaking the business. Shares fell 10.3% over the past month to $55.36, well below the $67.26 analyst target, while occupancy holds at 98.8% and re-leased properties recapture 102.7% of prior rent. Management lifted 2026 investment guidance to $10 billion at a 7.3% initial cash yield, formed a $6 billion hyperscale data-center joint venture, and on September 14 announced a euro-denominated joint venture to grow its private capital platform. Investment spreads that wide keep AFFO rising, and rising AFFO keeps the monthly raises coming.
Risk: Leverage and tenant quality. Net debt to adjusted EBITDAre rose to 5.4x from 5.2x, and 65.7% of annualized base rent is tied to tenants below investment grade. If rates stay high, refinancing costs eat into those investment spreads and the stock stays rate-sensitive. Second-quarter GAAP EPS of $0.37 also missed expectations of $0.42 on impairments. Shares go ex-dividend on September 30, with payment on October 15.
AbbVie: Healthcare Cash Machine Behind a Misleading GAAP Number
AbbVie yields 2.58%. It declared its next quarterly dividend of $1.73 on September 10, payable November 16. The quarterly payout climbed from $1.55 in 2024 to $1.64 in 2025 to $1.73 in 2026, and from $0.40 in 2013, its first year as a standalone company.
Here is where GAAP and cash split. Trailing GAAP EPS is just $3.55, below trailing dividends of $6.83, and the trailing P/E reads 74. Read literally, that looks like a dividend in danger. GAAP earnings include large noncash charges, mainly amortization of acquired drug intangibles plus acquired R&D write-offs such as the $744 million IPR&D charge that cost $0.41 of first-quarter EPS. None of that reduces the cash available for dividends. The cash-based view is what counts: 2026 adjusted EPS guidance of $13.87-$14.07 falls far above the forward dividend of $6.92, and forward P/E drops to 16. Second-quarter operating income rose 31% to $6.43 billion.
Bull case: The transition past Humira is working. Skyrizi revenue rose 24.4% to $5.51 billion and Rinvoq rose 24.5% to $2.53 billion, while neuroscience grew 20.3% to $3.23 billion. Total second-quarter revenue rose 10.2% to $16.99 billion. The pipeline keeps delivering: the FDA approved JUVMO for Parkinson’s disease on September 28, and the $10.9 billion Apogee acquisition closed on September 3. Shares are up 19.29% year to date at $266.47, with an analyst target of $278.61.
Risk: Patent erosion and deal costs. Humira sales fell 35.9% and Imbruvica fell 29.4% in the second quarter. The Apogee deal carries $0.14 of near-term EPS dilution, and AbbVie runs with a negative book value of -3.359 per share. If drug-pricing or tariff policy tightens while Skyrizi and Rinvoq growth slows, the raise pace would narrow toward the low single digits.
One Basket, Four Sectors, One Common Thread
Each of these five names covers its dividend on the metric that matters for its business: free cash flow for the staples, earnings and capital for JPMorgan, AFFO for Realty Income and cash earnings for AbbVie. Spreading income across staples, banking, real estate and pharma means a shock to one sector leaves most of the paycheck intact. PepsiCo and Realty Income carry the yield, JPMorgan and AbbVie carry the dividend growth, and Coca-Cola supports the whole basket. That mix is built to keep raising payouts through whatever the next cycle brings (if you want to go deeper on the longest-running raisers, we ranked ten of them by today’s valuations in a free Dividend Kings report).
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.