Here’s Why I’m Buying Broadcom Even As Concerns About Circular Financing With Anthropic Mount
Circular financing fears just sent Broadcom shares sliding, but one investor sees the selloff as a gift. Here is why the very risk spooking the market is the same reason he keeps adding to his position.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
I keep adding to my Broadcom (NASDAQ:AVGO | AVGO Price Prediction) position, and the growing worry about circular financing with Anthropic just gave me another chance to do it. Every quarter I look for a reason to stop. Every quarter this company gives me a new reason to keep going.
Why I Keep Coming Back
Broadcom co-designs custom AI chips with the few companies building frontier models, then sells them the networking that ties those chips together. That model locks in relationships that run across several chip generations. Management described a long-term Google agreement that could involve “multi-tens of billions of dollars of TPUs annually over the next several years.” That stickiness is what I pay for.
Three Numbers That Keep My Buy Button Active
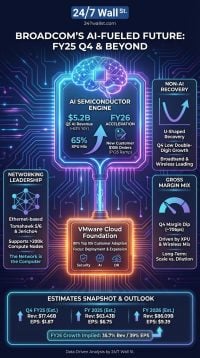
First, growth. Fiscal Q3 revenue hit $29.59 billion, up 85.5% year over year, and AI semiconductor revenue reached $16.70 billion, up 221%. Q4 guidance calls for $34.80 billion in revenue and $21.70 billion in AI revenue. Management projects AI semiconductor revenue of about $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
Second, cash. Free cash flow reached $13.67 billion, equal to 46% of revenue. In that same quarter, Broadcom paid $3.1 billion in dividends and retired $5.6 billion of debt due beyond a year. The $0.65 quarterly dividend got its 15th consecutive annual increase in December 2025. At $362.51, the yield stands near 0.72%. My reason for holding is the growth of that payout, and the starting yield matters less to me.
Third, valuation. Management says Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.” At today’s price, that works out to about 12x fiscal 2028 earnings. The shares rose just 7.93% over the past year while revenue nearly doubled, and over ten years they rose 2574.14%.
Why My Money Goes Here Instead of NVIDIA
Most readers reach for NVIDIA (NASDAQ:NVDA) first, and its fiscal Q2 revenue of $96.22 billion explains why. Still, NVIDIA trades near 48x trailing earnings. Its quarterly dividend only rose from $0.01 to $0.25 in May 2026, while Broadcom has raised its payout every year since fiscal 2011. NVIDIA also lists guarantee obligations capped at $108.5 billion for AI cloud and data center partners. Switching to NVIDIA would leave me with financing exposure too, at a higher price.
Risk I Refuse to Ignore
The financing concern is real. Broadcom built the AI XPV platform with Apollo and Blackstone to enable more than 20 gigawatts of computing capacity for OpenAI and Anthropic by the end of 2028. The first $35 billion tranche closed in June for Anthropic. Broadcom may provide “modest residual value guarantees,” and management confirmed an analyst’s figure of about $29 billion tied to that first tranche. Management also expects Anthropic to become its largest XPU customer in 2027. If Anthropic stumbles, I feel it twice.
I keep buying because third-party institutions underwrite and fund the assets, and Broadcom supplies no direct financing. Cash rose to $23.98 billion while total liabilities fell 4.21% year over year. Google, Meta and OpenAI also give Broadcom other large customers to lean on.
What Keeps Me Buying From Here
Management said “our demand actually exceeds this outlook” and that it has secured supply for fiscal 2027 and 2028. I will keep an eye on the December 9, 2026 earnings report for any new guarantees. The traits that showed up in the earliest stages of the last monster AI chip winner are the same ones we cataloged in a free playbook here. As Hock Tan put it, “Q3 demand was simply hot and we’re just getting started,”, and I plan to continue buying shares in a business still early in its run.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.