Thesis check
intact$24.00 -5.3% today
“Signed AI leases convert into durable recurring rent faster than Applied Digital burns cash”
Bull case
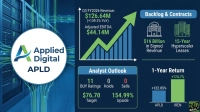
- Roughly $36 billion in signed lease revenue standing behind the build-out
- 175 MW now live at Polaris Forge 1, the first real test of recurring base rent
- Operating cash flow positive at $133 million in Q2 FY2026
Bear case
- Gross margin swung from 42.5% in Q1 FY2026 to 15.7%, leaving lease economics unproven at scale
- Street still models a loss of $0.3023 per share on $124.57 million in revenue
- Revenue expected to land below last quarter's fit-out-heavy total
The key assumptions for Applied Digital's Bull Case still hold: the backlog is signed and the first 175 MW is energized. The swing factor is the recurring base rent line we flagged this afternoon. A clean step-up in lease revenue with margin recovering toward prior-year levels strengthens the thesis, while another quarter carried by fit-out revenue at a compressed margin would be bearish.