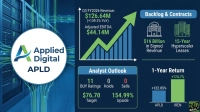
Valuation · as of Oct 7
$23.81-6.0%Target $66.43 · +179.0%
52-wk low $19.0052-wk high $50.73
- Price/Sales
- 12.1×
- EV/EBITDA
- -7.4×
- Price/Book
- 4.5×
At $23.81, Applied Digital sits within a few dollars of its 52-week low of $19 and less than half its $50.73 high, even with revenue up 406.6% year over year and 12x sales. No earnings multiple exists yet, with EV/EBITDA at -7.4, and the $66.43 consensus target from 13 buy ratings against 2 holds is nearly triple the price.