Wall Street Says $429 for Alphabet. Our Model Sees $500+
Alphabet's cloud backlog just hit half a trillion dollars while the stock sits 15% below its highs and trades at a fraction of what rivals command. Something in that math does not add up, and our model puts a number…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
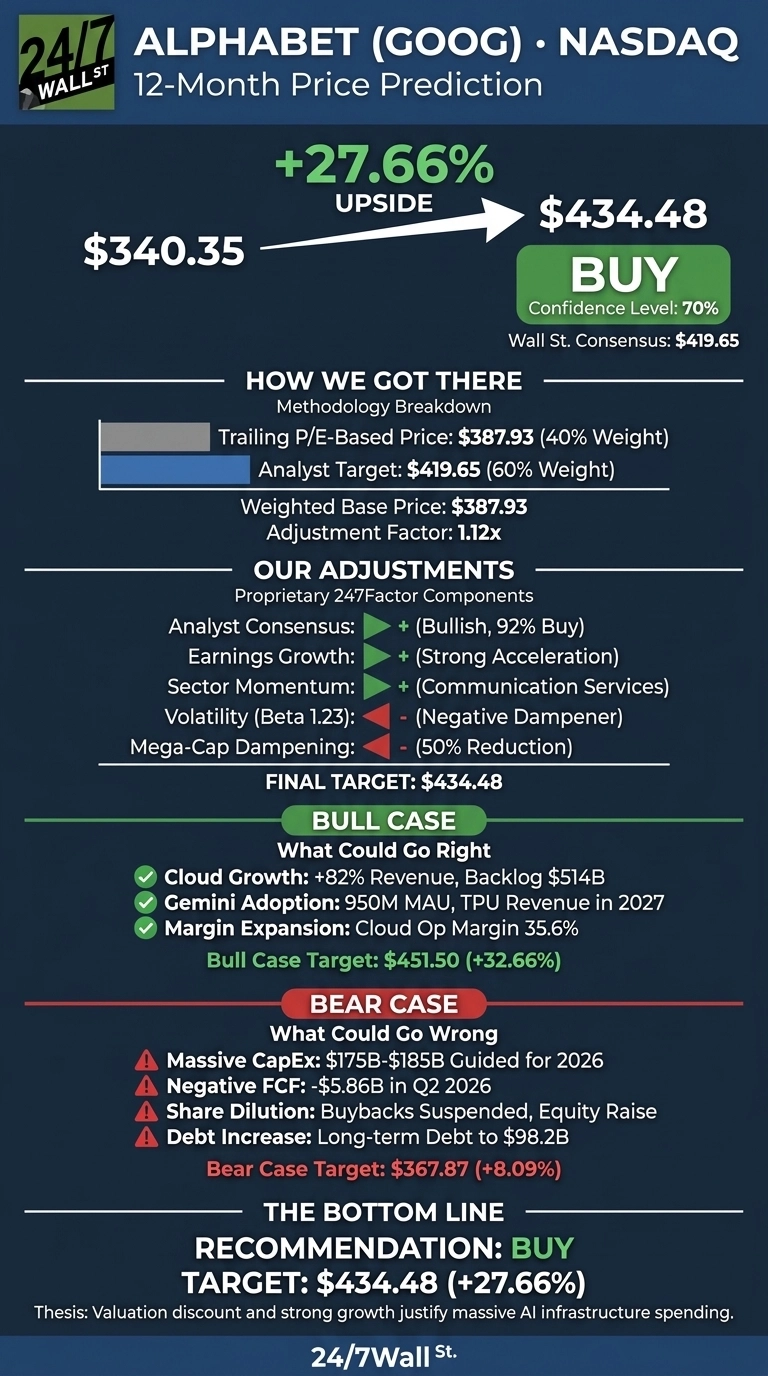
Our 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG | GOOG Price Prediction) is $434.48 over the next 12 months. That is 27.66% above the latest $340.35 close and ahead of the Wall Street consensus target of $419.65. Our model’s longer-term path moves past $500 by 2028.
| Metric | Value |
|---|---|
| Current Price | $340.35 |
| Price Target from 24/7 Wall St. | $434.48 |
| Upside/Downside | 27.66% |
| Recommendation | BUY |
| Confidence Level | 70% |
Alphabet is growing faster than it has in years. Revenue rose 24.2% in Q2 and Google Cloud grew 82%, yet the stock trades at about 14x trailing earnings. Analysts largely agree, with 55 buy ratings and 5 holds and no sells. I have moderate-to-high confidence in this call.

Alphabet Stock Stalls While Cloud Growth Hits 82%
Over the past year the stock is up 37.99%. Momentum has cooled since then: shares are down 0.57% over the past week, up 1.68% over the past month and up 8.29% year to date. GOOG sits 15.7% below its 52-week high of $403.96.
In Q2, EPS came in at $9.11 against a $3.04 estimate, and revenue of $119.80B exceeded expectations. A $99.03B unrealized equity gain inflated that EPS figure. The stronger signal is the cloud backlog, which reached $514 billion.

Why Bulls See Gemini and Cloud Driving $451 or Higher
The bull case reaches $451.50. Alphabet expects to recognize just over 50% of its backlog as revenue within 24 months. Most TPU system revenue lands in 2027.
Cloud operating margin rose from 20.7% to 35.6%, and the Gemini App has 950 million monthly users. Chief executive Sundar Pichai said “over the past year, we’ve gotten more bullish on the opportunities ahead.”

What Could Go Wrong With Alphabet’s Massive Capex Plan
Alphabet guides 2026 capex to $175B-$185B. That drove Q2 free cash flow to -$5.86B. The company also suspended buybacks, raised $49.6B in equity and set up a $40B at-the-market program. Long-term debt rose from $46.5B to $98.2B. The bear case sits at $367.87, which is still 8.09% above today’s price.
Trailing 12-month free cash flow is still $53.3 billion, and the capex is going somewhere, mostly into the power, cooling and networking that AI data centers run on (we covered seven suppliers riding that same expansion in a free report here). Alphabet’s CFO said “our goal is to invest as long as we see an attractive return on that investment.”
Alphabet Trades at a Steep Discount to Its Big Tech Peers
| Company | Trailing P/E | Operating Margin |
|---|---|---|
| Alphabet | 14 | 32.1% |
| Microsoft (NASDAQ:MSFT) | 29 | 46.8% |
| Meta Platforms (NASDAQ:META) | 27 | 41.4% |
| Amazon (NASDAQ:AMZN) | 35 | 11.2% |
Microsoft is the most direct cloud rival. Azure grew 43%, which is slower than Google Cloud, yet Microsoft trades at a far higher multiple.
Amazon runs AWS, the largest cloud platform. AWS revenue of $42.23B grew 37%, while Amazon’s company-wide margins are much thinner than Alphabet’s.
Meta Platforms is Alphabet’s closest advertising peer. Its ad revenue grew 27%, but Q2 EPS missed estimates by 14.42%.
Compared with this peer group, our target looks conservative.
Our Model Points Higher, and the Cloud Backlog Backs It Up
The 24/7 Wall St. price target of $434.48 has a buy rating at 70% confidence. The deciding factor is valuation: Alphabet trades at a discount to its peers while growing faster.
The bull case improves if cloud backlog keeps turning into revenue on schedule. The thesis weakens if dilution speeds up while cloud growth stalls. For now, the growth justifies the spending.
Our model’s base-case path shows where Alphabet could trade if current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $360.46 |
| 2027 | $434.48 |
| 2028 | $525.02 |
| 2029 | $571.83 |
| 2030 | $635.79 |
These projections assume Alphabet keeps executing its current strategy. The result could swing sharply in either direction depending on the Gemini 4 launch and whether capex returns hold up.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.