Meta’s Muse Is Getting Blocked at the Door. The Target Still Says $900+
Amazon just slammed the door on Meta's Muse agent, yet Wall Street is not flinching. Here is why one major bank sees the block as a footnote to a much bigger story unfolding inside Meta's ad engine.

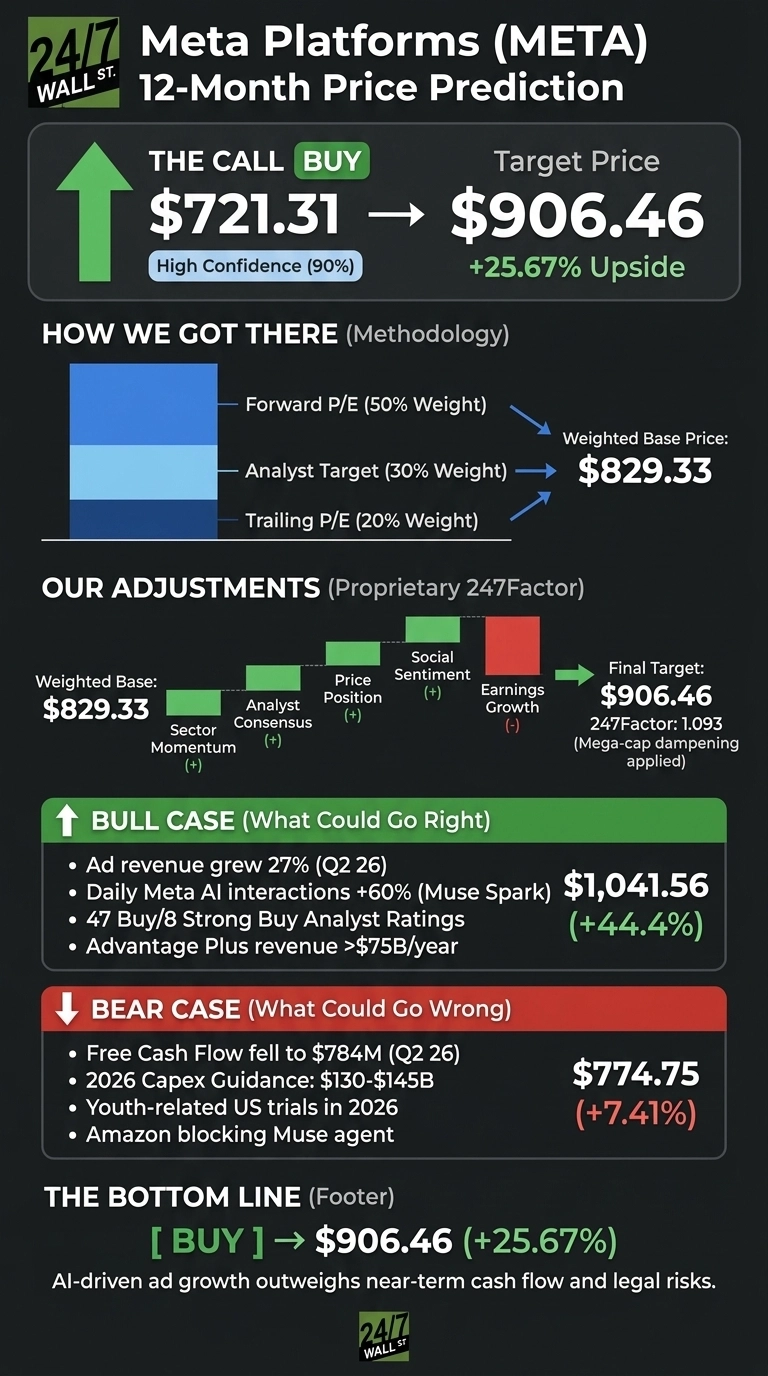
The 24/7 Wall St. price target for Meta Platforms (NASDAQ:META | META Price Prediction) is $906.46. From the current price of $721.31, that implies 25.67% upside. We rate the stock a buy, and our model’s confidence is high.
| Metric | Value |
|---|---|
| Current Price | $721.31 |
| Price Target from 24/7 Wall St. | $906.46 |
| Upside/Downside | 25.67% |
| Recommendation | BUY |
| Confidence Level | 90% |
Meta’s Muse agent was cut off from shopping on Amazon.com by Amazon (NASDAQ:AMZN), which warned that “continued access by an unauthorized AI agent violates Amazon’s Conditions of Use”. Our model still points higher because Muse’s value today shows up mostly inside Meta’s own apps and ad engine.

Shares Rally Despite Amazon Shutting Out Muse
Meta is down 0.71% over the past week but up 16.82% over the past month and 9.34% year to date. Shares sit about 7.5% below the 52-week high of $779.82 and roughly 38.9% above the low of $519.37.
In Q2, revenue of $60.80 billion rose 27.96% and beat estimates. EPS of $6.18 missed the $7.2214 consensus, weighed down by $2.40 billion in legal charges and $1.18 billion in severance.
The stock fell 7.95% on earnings day, then gained 9.44% over the following week. This week, Wells Fargo argued Muse has been a boon for Meta and can soar much higher.

Why Bulls See $1,041 Ahead
Our bull case reaches $1,041.56, a 44.4% gain. Ad revenue grew 27%. Advantage Plus is running above $75 billion a year, and more than 1 million businesses use Meta’s business agents every week.
Daily interactions with Meta AI rose 60% after Muse Spark was integrated. Wall Street mostly agrees: 8 strong-buy ratings and 47 buy ratings, with a consensus target of $794.96.

Cash Burn and Courtrooms Could Cap the Upside
The bear case is $774.75, which still remains above today’s price. Q2 free cash flow fell to $784 million as 2026 capex guidance moved up to $130 to $145 billion. Meta also noted youth-related U.S. trials that may result in material losses.
Traders give Meta only a 4.9% chance of hitting $900 in October. Excluding the legal and severance charges, operating income would have increased 9%, and operating cash flow rose 24.65%.
Meta Trades Between Alphabet and Amazon
| Company | Trailing P/E | Operating Margin |
|---|---|---|
| Meta | 26 | 41.44% |
| Alphabet | 16 | 32.06% |
| Amazon | 36 | 11.16% |
Alphabet (NASDAQ:GOOGL) is Meta’s most direct rival for ad dollars and frontier AI models. It looks cheaper, but a $99.03 billion equity gain inflated its earnings. Its Q2 revenue growth of 24.23% trailed Meta’s.
Amazon is the company that blocked Muse. The company’s ad business grew 26%, and it trades at a higher multiple despite thinner margins. Against these two, a 23x forward multiple for Meta looks reasonable.
Meta Earns Its Buy Rating at $906
I stand by our 24/7 Wall St. price target of $906.46, our buy rating and our 90% confidence. AI-driven ad growth is what tips the scale. My conviction would rise if free cash flow recovers while revenue keeps growing above 25%.
I would turn conservative if the youth trials creates large losses or capex climbs past guidance. For now, Muse’s trouble at Amazon looks like a side issue next to Meta’s core ad business.
Looking further ahead, the 24/7 Wall St. price target model projects Meta’s trading path, assuming current growth trends hold.
| Checkpoint | Base | Bull | Bear |
|---|---|---|---|
| 2026 target (Oct. 2027) | $906.46 | $1,041.56 | $774.75 |
| Oct. 2028 | $1,040.53 | $1,189.77 | $811.92 |
| Oct. 2029 | $1,210.60 | $1,414.62 | $840.76 |
| Oct. 2030 | $1,335.01 | $1,585.20 | $900.16 |
These projections assume Meta keeps executing on its existing plan. The biggest swing factors are whether its AI infrastructure spending earns a return and how the youth-safety litigation is resolved.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.