Apple Stock Price Prediction: Wall Street’s Next Big Surprise Could Be Closer Than You Think
Wall Street's consensus target sits below where Apple trades right now, yet nine straight quarters of earnings beats tell a completely different story. Something has to give, and the next catalyst may already be in motion.

Our 24/7 Wall St. price target for Apple (NASDAQ:AAPL | AAPL Price Prediction) is $391.86 over the next 12 months. That is 16.34% above the $336.83 reference price. The model rates the stock a buy with high confidence.
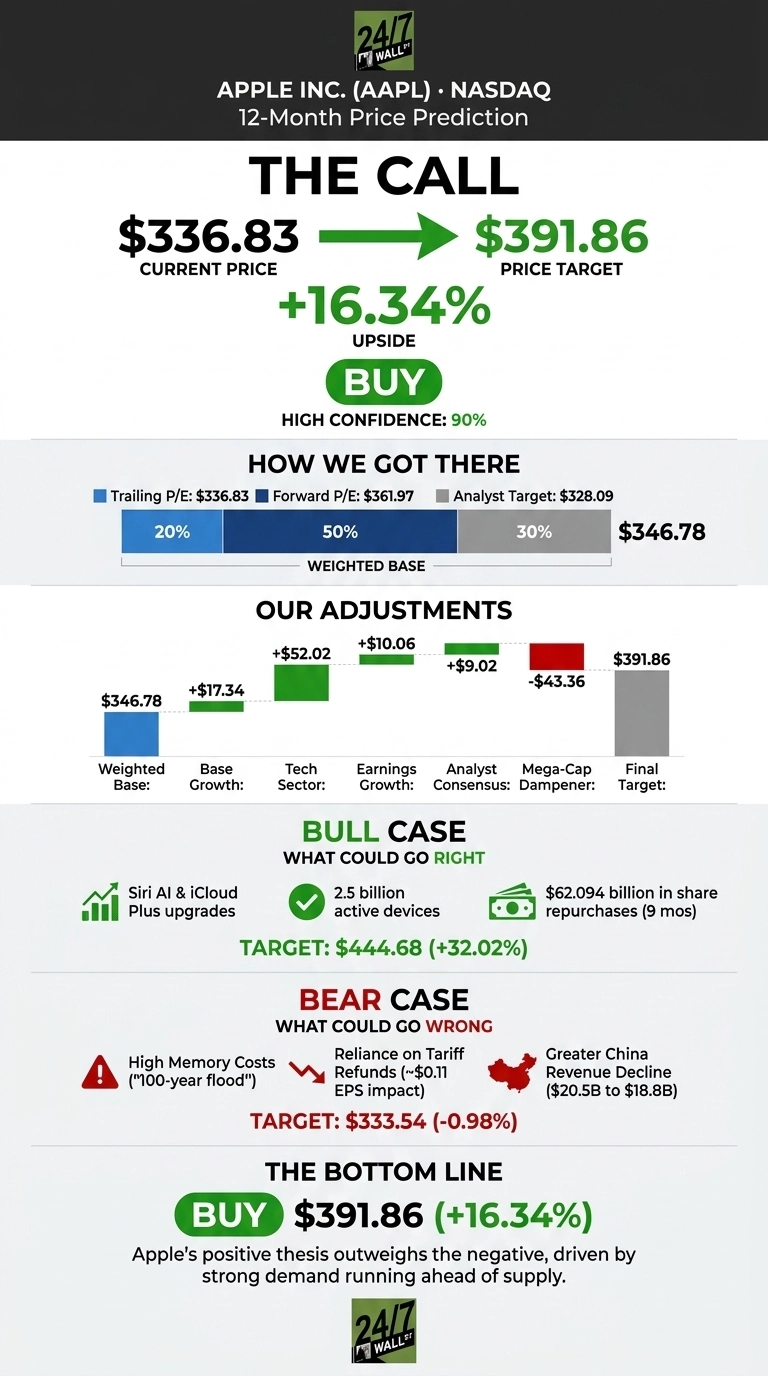
| Metric | Value |
|---|---|
| Current Price | $336.83 |
| Price Target from 24/7 Wall St. | $391.86 |
| Upside/Downside | 16.34% |
| Recommendation | BUY |
| Confidence Level | 90% |
Wall Street’s consensus target of $328.09 sits below the share price, even though Apple has beat EPS estimates for nine consecutive quarters.
Our model weights forward earnings more heavily than slower-moving analyst targets. If analysts raise numbers to match the iPhone 17 cycle, the Street could converge on our view.

iPhone 17 Demand Lifts Apple to Within 5% of Its High
Over the past week, Apple shares rose 1.78%. They gained 5.93% over the past month and 25.02% year to date. The stock trades about 5% below its 52-week high of $345.34.
Apple’s fiscal Q3 report recorded revenue of $109.42 billion, up 16.4%. EPS came in at $2.02, ahead of the $1.89 consensus. iPhone revenue grew to $54.25 billion from $44.58 billion.
Management expects September-quarter revenue growth of 9% to 11%, held back by supply limits. CEO Tim Cook said “the iPhone and the Mac are both doing remarkably better than we thought they would do.”

Why Bulls See $444 Within Reach
Upside targets land at $444.68, a 32.02% gain. Three things drive it:
- Siri AI. Apple introduced new Siri at WWDC26 with paid iCloud Plus upgrades built around it.
- User base. Apple counts more than 2.5 billion active devices.
- Buybacks. Apple bought back $62.094 billion of stock over nine months.
Among analysts, 25 rate Apple a buy or strong buy.

Memory Costs Could Squeeze the Margin Story
Downside targets land at $333.54. Cook called memory pricing a “100-year flood”. One-time tariff refunds added about $0.11 to EPS.
Greater China revenue fell from $20.497 billion to $18.816 billion from the prior quarter. Without tariff refunds, gross margin still hit guidance midpoint. R&D spending rose to $11.73 billion, showing AI investment.

Apple Trades Above Its Mega-Cap Peers
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Apple | 44 | 16.4% |
| Microsoft (NASDAQ:MSFT) | 29 | 17.75% |
| Alphabet (NASDAQ:GOOGL) | 16 | 24.23% |
Microsoft grows slightly faster at a lower multiple and spent $115.95 billion on capital projects in fiscal 2026. Apple’s leaner spending helps explain its premium.
Alphabet competes through Android with a low P/E flattered by $99 billion of unrealized gains. Free cash flow was -$5.855 billion last quarter, and Alphabet suspended buybacks. Apple’s premium showing cash returned to shareholders.
Supply and Margins Will Decide Apple’s Next Move
My 24/7 Wall St. price target is $391.86. The rating is buy with 90% confidence. The key factor is demand that keeps running ahead of supply.
Apple’s upside improves if iPhone and Mac supply catches up with orders. Memory costs drove gross margin below guidance would add downside weight. For now, Apple’s positive thesis outweighs the negative one.
The 24/7 Wall St. price target model projects Apple could trade at these levels if current trends hold:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $343.01 |
| 2027 | $395.40 |
| 2028 | $434.24 |
| 2029 | $474.34 |
| 2030 | $517.73 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.