Joby Just Dropped 20% in a Month: Is It Time to Sell?
Joby Aviation has shed a fifth of its value in a single month while the broader market climbed, and the reasons point to something bigger than one company's bad stretch. Here is what the numbers reveal about whether holders should…

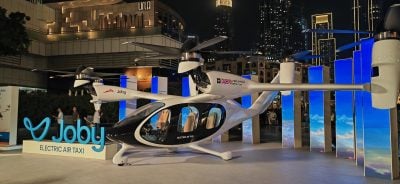
Joby Aviation (NYSE:JOBY | JOBY Price Prediction) stock is down 20% over the past month to $5.14. This drop leaves shareholders mulling whether to stay with the electric air taxi developer.
Meanwhile, Archer Aviation (NYSE:ACHR) stock is down 16% over the past month to $4.61, representing a smaller decline than Joby stock’s. Additionally, EHang Holdings (NASDAQ:EH) stock is down 12% over the past month to $4.03, a lighter drop than Joby’s as well.
For a broader read, the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is up 2% over the past month to $777.80. The ARK Autonomous Technology & Robotics ETF (BATS:ARKQ), which holds both Joby and Archer Aviation, is down 0.2% over the same stretch to $121.80. That split frames the question for Joby holders: the selling has concentrated in one narrow industry group while the broad market climbed.

Air Taxi Names Fell Together
All three electric air taxi stocks fell over the past month while the S&P 500 fund rose, a pattern that points to selling across one group of companies. Joby has issued no announcement in the past month that explains the decline. Its most recent major update came on its August 5 call covering the second quarter of 2026, when CFO Rodrigo Brumana reported revenue of $39 million, drawn primarily from the Blade passenger helicopter business, as the company raised its full-year sales guidance.
On the same call, Brumana said Joby ended the quarter with approximately $2.3 billion in cash, cash equivalents and short-term investments. Brumana also reported a net loss of $245 million under generally accepted accounting principles and guided to second-half cash use of $385 million to $415 million. Those results precede the past-month window, so they frame Joby’s finances without accounting for the recent selling.
What the Peer Group Says About Joby
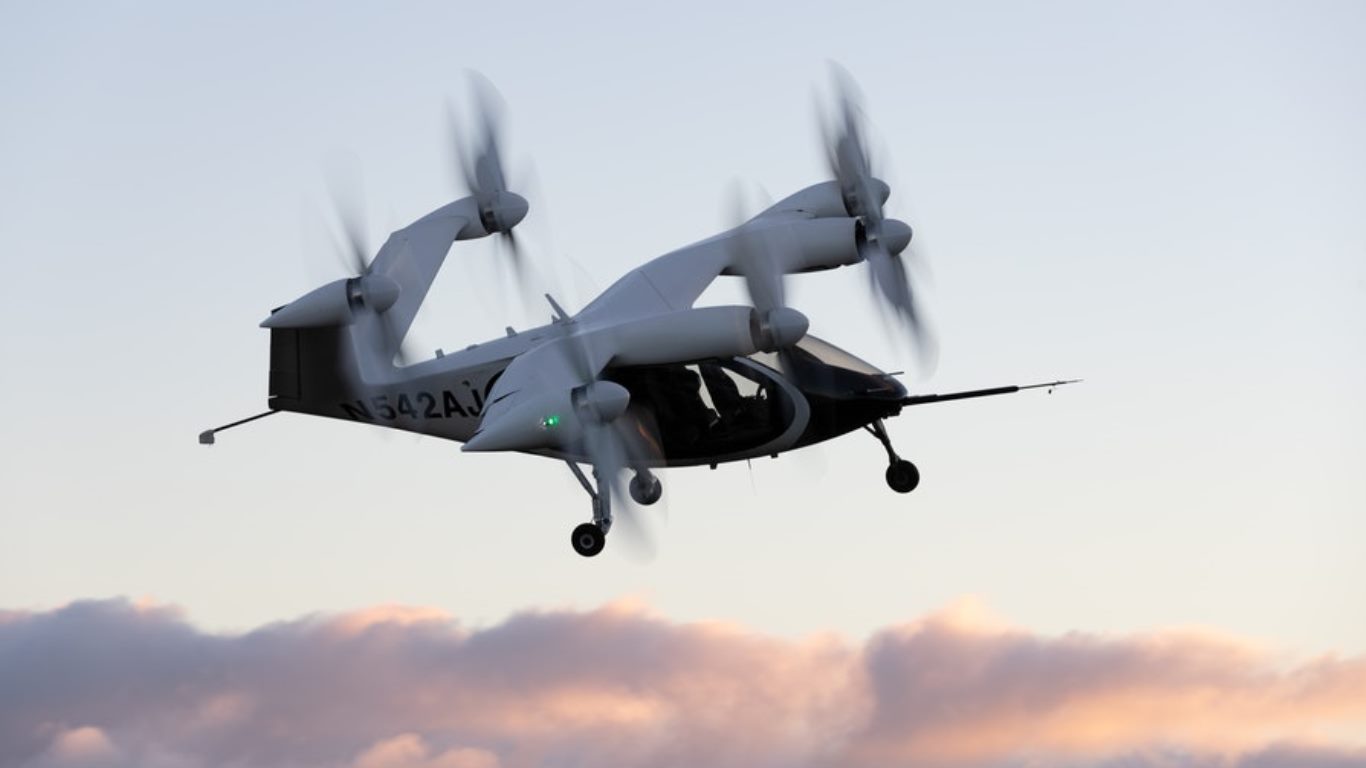
Joby is building an electric aircraft that takes off vertically, and it needs regulatory certification before it can carry paying passengers, but until then, almost all of Joby’s current revenue comes from Blade, the conventional helicopter business it acquired.
Skeptics start with the spending guidance, which points to heavy outlays through the rest of the year while the revenue that matters still sits ahead of certification. A company funding a long timeline is exposed every time risk appetite contracts. JoeBen Bevirt, Joby’s founder and chief executive at the time of the call, acknowledged the execution challenge, stating, “As we’ve said before, manufacturing is hard.”
Supporters of Joby stock point to a cash position that’s large relative to the company’s size, and they also note that the helicopter business already produces revenue while the aircraft moves through certification. Brumana added that Joby can “stage a portion of that spend to match our progress, keeping our usual capital discipline.”

What to Watch Next
Joby’s next test is whether certification milestones arrive on the timetable management has described. Traders may want to check for whether second-half cash use lands inside the guided range. Either result could reset how the market prices Joby’s long timeline.
A stock tied to a certification calendar can swing sharply in both directions, and Joby’s past month shows the downside of that profile in plain terms. It makes sense to keep one’s positions modest enough that further volatility in the air taxi group wouldn’t force a rushed decision (we wrote a free guide on sizing speculative positions with rules that keep them from hurting, here: Small Stakes, Big Swings).
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk.His work has appeared in The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, TalkMarkets, Finmasters, 24/7 Wall St., and others.With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.