J&J Beat and Raised. The Stock Fell Anyway. Here’s What the Target Says
Johnson and Johnson crushed earnings, raised guidance, and still watched its stock crater nearly 6% in a single session. Understanding what spooked investors reveals whether Tuesday's selloff is a trap or a warning.

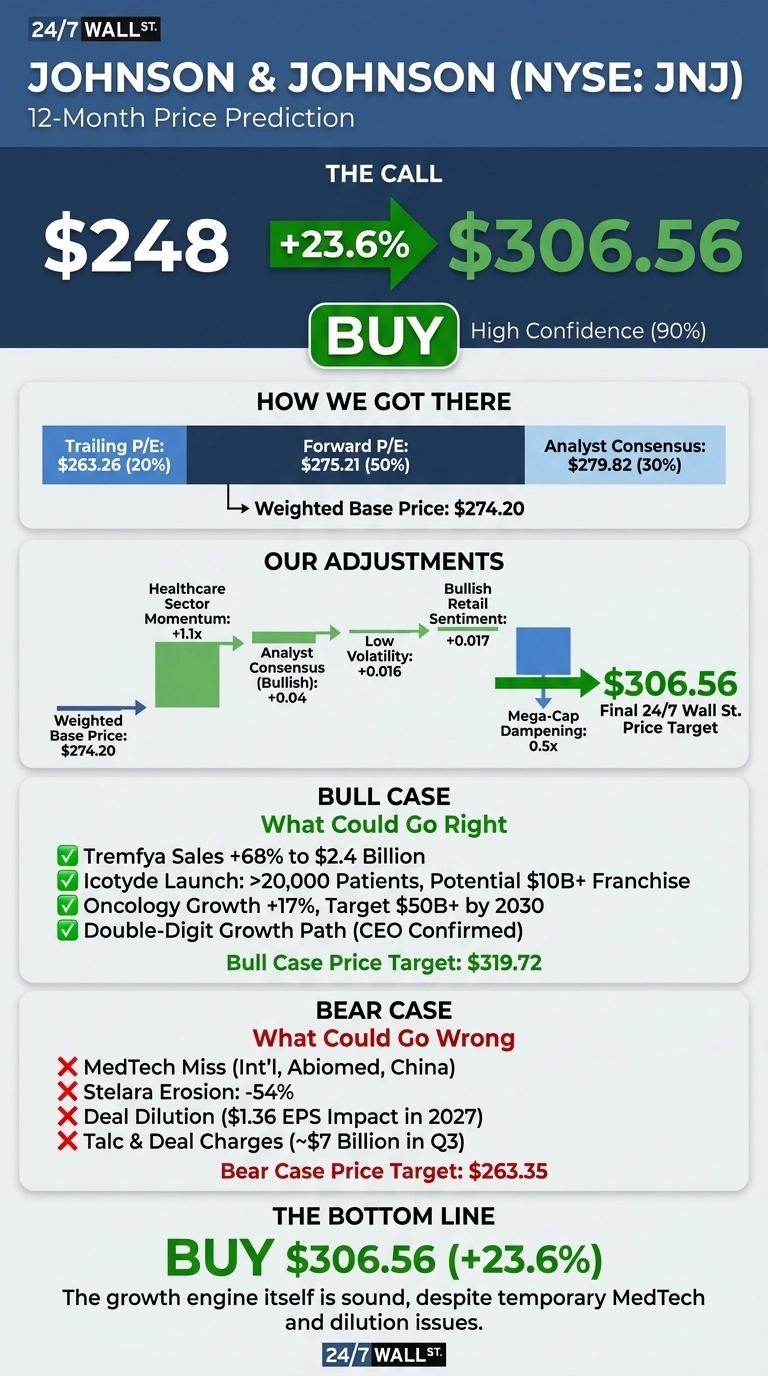
The 24/7 Wall St. price target for Johnson & Johnson (NYSE:JNJ | JNJ Price Prediction) is $306.56 over the next 12 months. Our rating is buy.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $248 |
| Price Target from 24/7 Wall St. | $306.56 |
| Upside/Downside | 23.6% |
| Recommendation | BUY |
| Confidence Level | 90% |
J&J traded at $248 noon Tuesday, down 5.96% on the session after its third-quarter report. From here, our target means 23.6% upside.
Our model gives this call high confidence: strong analyst support, low volatility and accelerating pharmaceutical brands offset a soft MedTech quarter. I read the selloff as a reaction to deal dilution and one weak segment, while the growth engine itself is sound.

A MedTech Miss and Deal Dilution Overshadowed the Q3 Beat
Third-quarter sales rose 6% to $25.4 billion, and adjusted EPS came in at $2.59. J&J raised its full-year sales forecast to about $101.2 billion at the midpoint from $101.1 billion, and lifted its adjusted EPS midpoint to $11.10 from $11.04, according to CNBC.
The weak spot was MedTech. Sales there grew 2.5% to $8.6 billion, missing estimates of $8.71 billion. Adjusted EPS also fell 7.5% year over year as J&J paid for the Firefly Bio and SAIL Biomedicines deals.
Shares are down 6.62% over the past month but still up 21.76% year to date. They sit 11.8% below the 52-week high of $281.07.
Why Bulls See $319 and Beyond
Tremfya sales rose 68% to $2.4 billion, ahead of estimates near $2.2 billion. The new psoriasis drug Icotyde already has more than 20,000 patients on therapy, and management sees it becoming a $10 billion plus franchise.
Oncology grew about 17%, and J&J is aiming for more than $50 billion in cancer sales by 2030. CEO Joaquin Duato said reaching double-digit growth “does not assume any inorganic additions at this moment in time.”
Analysts lean bullish, with 5 Strong Buy and 11 Buy ratings against 6 Holds and 1 Sell. The December 8 Enterprise Business Review is the next catalyst. The bull case stands at $319.72.

MedTech Drag and Talc Charges Are the Risks Worth Watching
The MedTech segment grew just 0.1% outside the U.S., and Abiomed declined 1.5%. Middle East conflict and China pricing added pressure. MedTech chief Tim Schmid called the results “below the standard we have set internally.” Guggenheim’s Vamil Divan expects investors “will be disappointed in some of the details.” Stelara also fell 54%.
Reported EPS of $0.09 looks alarming, but most of that comes from about $7 billion in charges linked to the talc settlement and recent deals.
Strip out the $0.64 Firefly and SAIL impact, and EPS growth would approach 9%. The $1.36 per share of expected 2027 dilution is a real cost. The bear case stands at $263.35.

Is J&J Cheaper Than Pfizer and Eli Lilly?
| Company | Forward P/E | Quarterly Revenue Growth |
|---|---|---|
| Johnson & Johnson | 21x | 6.6% |
| Pfizer | 10x | 2.6% |
| Eli Lilly | 24x | 47.7% |
Pfizer (NYSE:PFE) is the value contrast. It yields 6.18%, but quarterly earnings fell 10.1%. J&J’s premium comes from faster growth with less patent risk.
Eli Lilly (NYSE:LLY) is the growth benchmark. Its multiple stands only a few turns above J&J’s despite much faster sales growth. Taken together, the peer group makes our target look reasonable.
What Could Drive J&J Toward $306.56
The 24/7 Wall St. price target of $306.56 has a buy rating with 90% confidence. What decides it for me is the pharmaceutical growth that keeps absorbing Stelara losses.
Bullish momentum builds if Tremfya and Icotyde keep beating estimates. The thesis weakens if MedTech misses again in the fourth quarter. Tuesday’s selloff comes from the MedTech miss and deal dilution.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $273.26 |
| 2027 | $307.12 |
| 2028 | $343.25 |
| 2029 | $373.43 |
| 2030 | $401.66 |
J&J would need to keep executing on its current strategy for these projections to hold. The DePuy Synthes spinoff, talc resolution and Icotyde launch could each move results significantly in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.