Truist Says $1,000 for Meta. Our Bull Case Goes Higher
Truist just slapped a $1,000 price target on Meta, but our proprietary model pushes the bull case even further while flagging a bear scenario that could leave the stock with almost no upside from here.

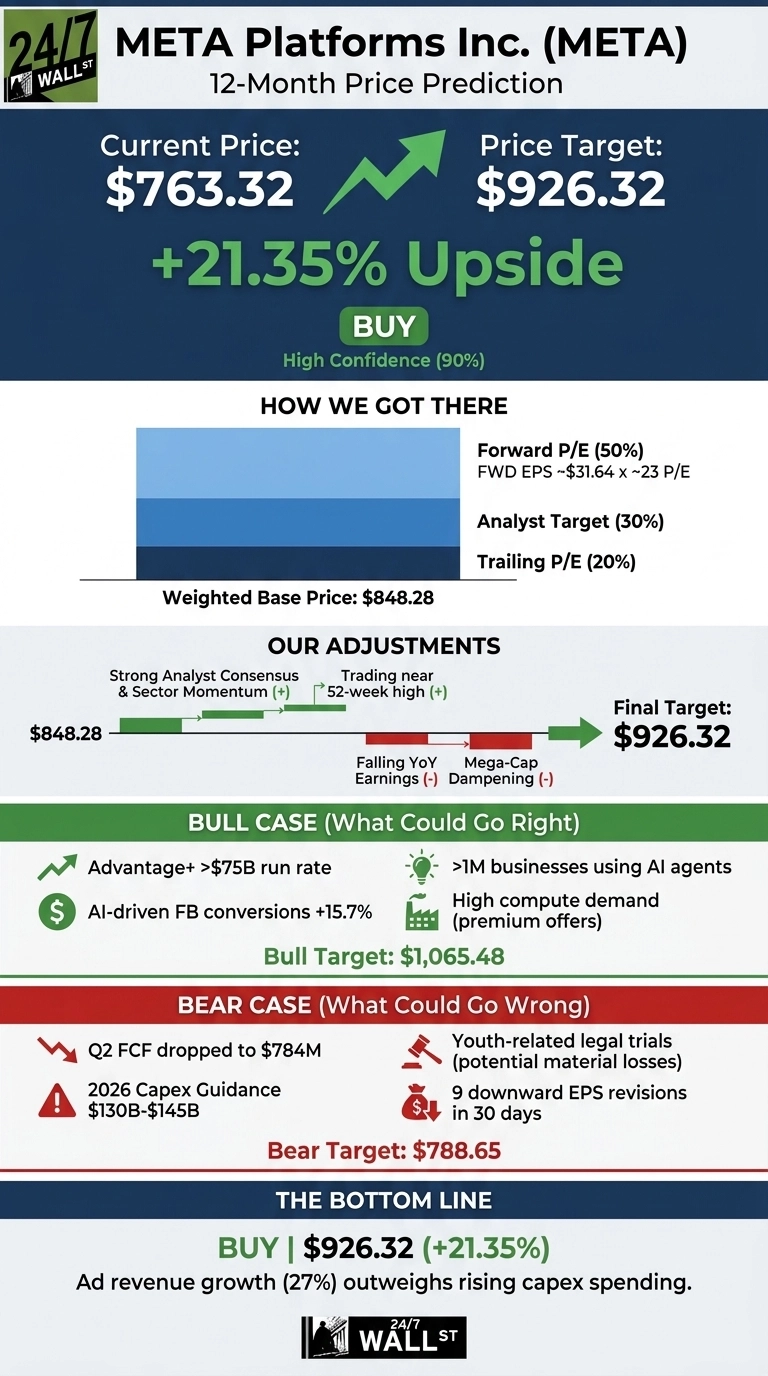
Meta Platforms (NASDAQ:META | META Price Prediction) traded at $763.32 midday Tuesday. Our proprietary model puts the 24/7 Wall St. price target at $926.32 over the next 12 months, which works out to 21.35% upside.
The model rates Meta a buy with high confidence. Truist’s $1,000 call sits above our base case, but our bull scenario goes higher still.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $763.32 |
| Price Target from 24/7 Wall St. | $926.32 |
| Upside | 21.35% |
| Recommendation | BUY |
| Confidence Level | 90% |

Wall Street mostly agrees. Analysts split 8 Strong Buy, 47 Buy, 7 Hold and 1 Sell, but the consensus target of $799 is close to where the stock already trades. That leaves Truist and our model as the more aggressive calls.

Muse Wonder Launch Extends a Sharp Rally
Shares rose 2.74% today after Meta revealed its new Muse Wonder AI models. The stock is up 2.89% over the past week, 17.87% over the past month and 15.92% year to date. It sits 2.12% below its 52-week high of $779.82 and 46.97% above its low of $519.37.
The rebound followed a mixed Q2. Revenue rose 27.96% to $60.80 billion, beating estimates. EPS of $6.18 missed the $7.2214 consensus, weighed down by $2.40 billion in legal charges and $1.18 billion in severance.

Why Our Bull Case Clears $1,065
Our bull scenario hits $1,065.48, above Truist’s figure. Advantage+ has passed a $75 billion annual revenue run rate. Meta’s ad-ranking models raised Facebook conversions 15.7%, and more than 1 million businesses now use business agents every week.
Zuckerberg said Meta gets offers for its compute at a “significant premium” over what it paid. The highest 2027 EPS estimate of $40.3149 shows how far the upside could go.

Capex and Courtrooms Could Cap the Upside
Free cash flow fell to $784 million in Q2, and 2026 capex guidance is $130 to $145 billion. Several youth-related U.S. trials may result in material losses. Over the past 30 days, analysts made 9 downward revisions to 2026 EPS estimates.
The bear case lands at $788.65. Looking at the positives, operating income would have risen 9% without the one-time charges, and management says Meta is demand-constrained, with plenty of high-return uses for new computing power.
Meta Outgrows Alphabet but Costs More
Alphabet (NASDAQ:GOOGL) is the largest digital-ad rival and faces the same capex question. At about 16x earnings, it compares with Meta’s 27x. However, its Q2 earnings got a lift from $99 billion in equity gains, and its free cash flow was negative.
Pinterest (NYSE:PINS) is a smaller pure social-ad business. Its revenue grew 18.17%, and it guides Q3 growth to 13%-15%. Meta grows faster than both at far larger scale, which makes our target look reasonable.
| Company | Q2 Revenue Growth | Q2 Free Cash Flow |
|---|---|---|
| Meta | 27.96% | $784M |
| Alphabet | 24.23% | -$5.86B |
| 18.17% | $269.9M |
Meta Price Prediction 2026-2030
Our 24/7 Wall St. price target is $926.32, with a buy rating and 90% confidence. What tips the scale for me is ad revenue growing 27% while spending rises.
The bull case improves if Q3 revenue lands in the $61 to $64 billion guidance range and free cash flow rebounds. It weakens if the youth trials bring large losses. On balance, the numbers favor the bulls.
The model projects Meta could trade at the following levels over the next few years if current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $752.94 |
| 2027 | $930.27 |
| 2028 | $1,093.17 |
| 2029 | $1,200.83 |
| 2030 | $1,333.86 |
The projections rest on Meta continuing to execute on its current strategy. New AI revenue from agents could add significant upside, while capex overruns could drag the numbers lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.