Adobe Stock Has Been Under Pressure. Here’s What Could Spark a Turnaround
Adobe keeps beating earnings estimates while the stock keeps sliding, and that contradiction has split Wall Street into two very different camps with very different price targets.

The 24/7 Wall St. price target for Adobe (NASDAQ:ADBE | ADBE Price Prediction) is $298.13 over the next 12 months. That means 16.4% upside from the current $256.13. The stock earns a buy rating with high confidence.
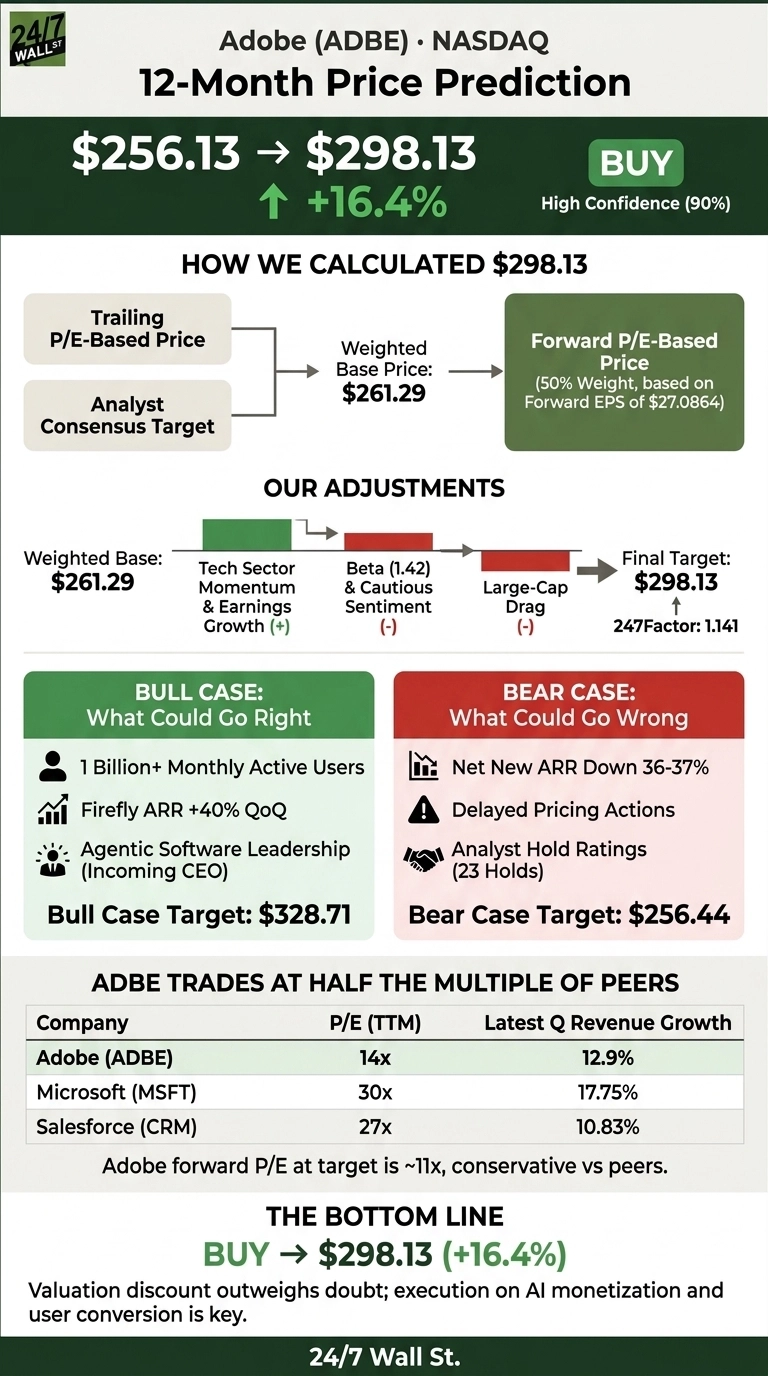
| Metric | Value |
|---|---|
| Current Price | $256.13 |
| Price Target from 24/7 Wall St. | $298.13 |
| Upside/Downside | 16.4% |
| Recommendation | BUY |
| Confidence Level | 90% |

Adobe keeps beating estimates while the stock keeps falling, and that gap defines the valuation debate. Shares trade at a forward P/E of 9, which looks cheap for a business that just raised guidance.
Several turnaround catalysts are already on the calendar: a new CEO takes over December 1, Adobe MAX arrives in November, and AI-first ARR is growing more than 150%.
Record Quarters Have Not Stopped the Slide
Adobe is down 26.75% year to date and sits well below its 52-week high of $363.70, though it has climbed off the $190.12 low. Momentum has turned recently, with shares up 8.51% over the past week and 3% over the past month.
In fiscal Q3, revenue came in at $6.76 billion, up 12.9% and ahead of the $6.70 billion consensus. Non-GAAP EPS of $6.13 topped the $6.09 estimate, making it the fifth beat in a row.
Jim Cramer summed up the problem in June: the stock traded at “just 8.5 times” earnings as concerns grew that AI will replace software.
Why Bulls See $328 and Beyond
Adobe now has more than 1 billion monthly active users, and Firefly ending ARR grew 40% quarter over quarter. The pending Topaz Labs deal adds AI video enhancement.
Buybacks also help, with about $24.55 billion left on the current authorization. Incoming CEO Anil Chakravarthy sees “a massive opportunity for us to be the agentic software leader.” In our bull case, shares reach $328.71.

What Could Keep Adobe Stuck
Investors remain wary. Of the analysts covering Adobe, 23 rate it a hold, and the consensus target is $272.31. Analysts on the Q3 call noted that net new ARR fell 36% to 37%. Management’s explanation is that it deliberately sent users into the freemium model and delayed price increases.
The trade-off is reasonable, but it needs to start showing up as revenue. A CFO exit and the CEO transition add execution risk. In our bear case, the stock sits flat at $256.44.

Adobe Trades at Half the Multiple of Microsoft and Salesforce
Microsoft (NASDAQ:MSFT) competes with Acrobat and Express through Copilot. Shares trade at 30 times earnings, supported by 43% Azure growth.
Salesforce (NYSE:CRM) competes with Adobe’s Experience Cloud and is growing more slowly, yet it still trades at 27 times earnings.
| Company | P/E (TTM) | Latest Quarterly Revenue Growth |
|---|---|---|
| Adobe | 14 | 12.9% |
| Microsoft | 30 | 17.75% |
| Salesforce | 27 | 10.83% |
Even at our target, Adobe would trade at about 11 times forward earnings. Compared with these peers, the 24/7 Wall St. price target looks conservative.
Discount Outweighs Doubt
The 24/7 Wall St. price target of $298.13 comes with a buy rating and high confidence.
Valuation is the key factor: double-digit growth at a single-digit forward multiple. The case gets stronger if MAX and the CEO transition show freemium users turning into paying ARR. It weakens if net new ARR keeps contracting into 2027.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $264.13 |
| 2027 | $298.13 |
| 2028 | $333.05 |
| 2029 | $370.90 |
| 2030 | $388.35 |
Adobe is expected to keep executing on its current strategy. Faster AI monetization could push the stock higher, while AI tools from competitors could cut into these numbers.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.