Wall Street Has Its Eyes on Adobe. Here’s Where the Stock Could Be Headed.
Adobe is down nearly 28% this year yet still beating earnings estimates and raising guidance, which raises an uncomfortable question about whether the market has gotten the AI disruption story completely wrong.


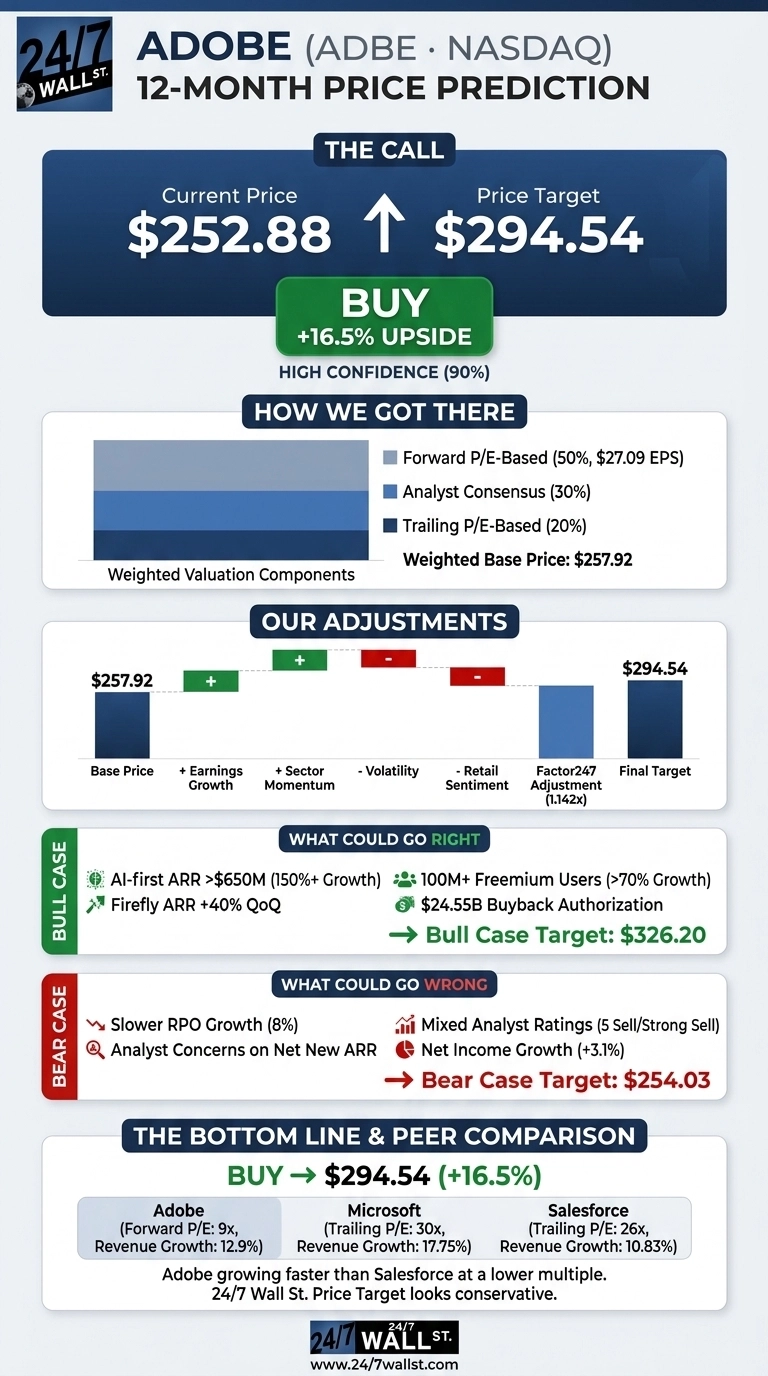
The 24/7 Wall St. price target for Adobe (NASDAQ:ADBE | ADBE Price Prediction) is $294.54 over the next 12 months. With shares trading at $252.88, that works out to 16.5% upside. The stock gets a buy rating with high confidence.
| Metric | Value |
|---|---|
| Current Price | $252.88 |
| Price Target from 24/7 Wall St. | $294.54 |
| Upside/Downside | 16.5% |
| Recommendation | BUY |
| Confidence Level | 90% |

Adobe’s growth is holding up and guidance keeps rising, yet the stock is priced as if its business is shrinking. That gap drives the call. At a forward P/E of about 9x, the market has already priced in a lot of fear about AI disruption.
The open question is whether Adobe can turn rapid AI adoption into a clear acceleration in annual recurring revenue (ARR). We think the current price leaves enough room for that to work.
Rebound Week Follows a Bruising 2026
Shares gained 5.07% today and 8.64% over the past week. Shares remain down 4.79% over the past month and 27.75% year to date. The stock sits 30.5% below its 52-week high of $363.70 and 33% above its low of $190.12. The bounce came right after a widely read Barron’s report on a downgrade to Sell over growth concerns.
The latest results were solid. Fiscal Q3 revenue rose 12.9% to $6.76 billion, ahead of the $6.70 billion consensus. Non-GAAP EPS of $6.13 beat the $6.09 estimate. Management also raised full-year non-GAAP EPS guidance to $24.45 to $24.50. Leadership is changing too: Anil Chakravarthy becomes CEO on December 1, and Shantanu Narayen stays on as executive chair.

Why Bulls See $326 Within Reach
Adobe’s AI-first ARR now exceeds $650 million and is growing more than 150% a year. Firefly ARR rose 40% quarter over quarter. Creative freemium users passed 100 million, up more than 70%. Adobe has also held off on pricing actions to build its user base first, which gives it room to raise prices later.
Capital returns add support: Adobe bought back 9.5 million shares last quarter and has $24.55 billion left under its authorization. Of the analysts covering the stock, 11 rate it Buy or Strong Buy, and the consensus target is $272.31. The bull case is $326.20.

Cracks Bears Say Are Already Showing
Remaining performance obligations grew just 8%, and analysts pressed management on net new ARR. Five analysts rate the stock Sell or Strong Sell. Net income rose only 3.1%.
On the other side of the ledger, free cash flow grew 14.68%, and much of the profit lag reflects planned investment in freemium growth. The bear case is at $254.03.

Adobe Trades at a Steep Discount to Microsoft and Salesforce
The benchmark for AI monetization at scale is Microsoft (NASDAQ:MSFT). It has more than 30 million paid Copilot seats and grew quarterly revenue 17.75% while trading at about 30x trailing earnings.
Adobe Experience Cloud faces direct competition from Salesforce (NYSE:CRM). It grew revenue a slower 10.83% yet trades at 26x trailing earnings.
| Company | P/E | Latest Quarterly Revenue Growth |
|---|---|---|
| Adobe (forward) | 9x | 12.9% |
| Microsoft (trailing) | 30x | 17.75% |
| Salesforce (trailing) | 26x | 10.83% |
Adobe is growing faster than Salesforce at a far lower multiple. Next to that peer group, our 24/7 Wall St. price target looks conservative.
What Could Make or Break Adobe From Here
The 24/7 Wall St. price target remains at $294.54, with a buy rating and 90% confidence. Valuation is the deciding factor.
Shares could outperform if AI-first ARR keeps growing at triple digits and the new CEO starts turning freemium users into paying ones. The bear case gains weight if net new ARR keeps slowing into fiscal 2027.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $261.36 |
| 2027 | $294.54 |
| 2028 | $335.35 |
| 2029 | $360.13 |
| 2030 | $396.73 |
Adobe would need to keep executing on its current strategy for these projections to hold. Generative AI competitors could drive results well below this path, while faster monetization of its user base could drive them well above it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.