The AI Power Bill Comes Due: Will GE Vernova’s Q3 Earnings Oct. 28 Prove Its $176B Backlog Is Real?
GE Vernova heads into its October 28 earnings report with a $176 billion backlog and freshly raised guidance, yet the stock just shed more than 14% in a month as Wall Street grows uneasy about how AI spending gets financed.…

GE Vernova (NYSE:GEV | GEV Price Prediction) reports third-quarter results before the open on Oct. 28. The stock fell 11.53% last week on fears about how AI spending will be financed. This report needs to show that the record backlog is still turning into revenue and cash.
Record Backlog Meets a Nervous Market
Last quarter, revenue of $11.10B rose 21.8% year over year and beat the $10.77B consensus. Orders jumped 88% organically to $24.20B, which lifted backlog to a record $176 billion. That was up $13 billion from the prior quarter. Free cash flow of $5.10B was more than the company generated in all of 2025.
In July, management raised its 2026 revenue guidance to $45.5B-$46.5B. It also lifted the free cash flow target to $11.5B-$12.5B from $6.5B-$7.5B. CEO Scott Strazik expects at least 125 GW of gas equipment under contract by year-end, up from 116 gigawatts at the end of Q2.
Since then, the mood has turned. Shares closed Friday at $814.58, down 14.37% over the past month. Barron’s linked the drop to Meta Platforms (NASDAQ:META), mentioning AI financing fears triggered by Meta. The stock is still up 24.93% year to date.

Analysts Expect About 20% Revenue Growth
| Metric | Consensus | Year-Ago Actual | Implied YoY Growth |
|---|---|---|---|
| Q3 2026 EPS | $4.0219 | N/A | N/A |
| Q3 2026 Revenue | $11.997B | $10.00B | 20.0% |
| FY2026 EPS | $30.4293 | N/A | N/A |
| FY2026 Revenue | $46.32B | $38.10B | 21.6% |
Analysts have trimmed the Q3 EPS estimate from $4.3269 90 days ago to $4.0219 now.

Turbine Output, Pricing and Data Center Orders Take Center Stage
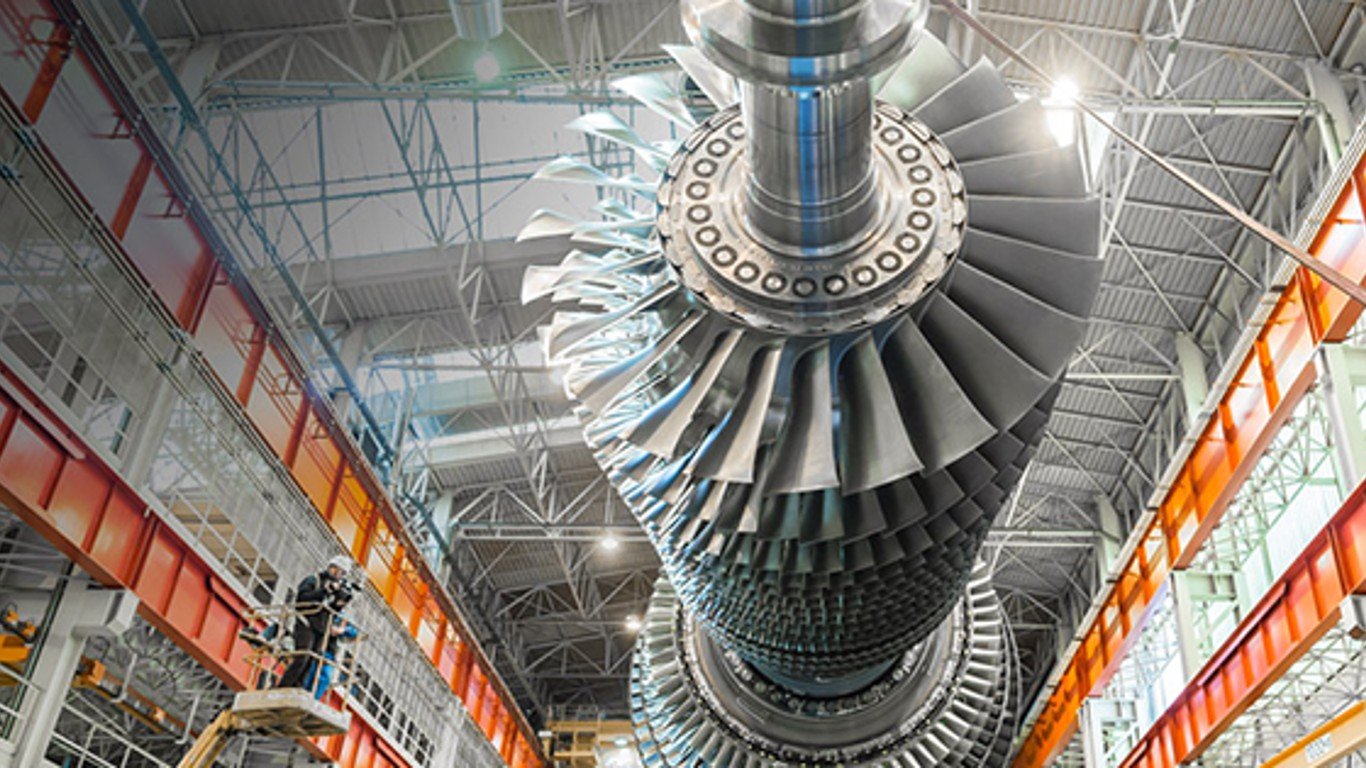
Gas Power comes first on my watch list. Management said quarterly output rises from about three gigawatts to five gigawatts starting in Q3. It expects Power revenue to grow 17%-19% with margins of about 17%-18%. Equipment orders in the first half were priced more than 20% above Q4 2025 levels.
You should also look at what makes up the backlog. Slot reservations made up 63 gigawatts of the gas pipeline, while firm Gas Power backlog was at 53 gigawatts. How quickly reservations become firm orders shows how durable that demand is.
In Electrification, data center orders exceeded $5 billion in the first half, more than double the total for all of 2025. The segment’s margin rose 700 basis points to 18.4%, and Prolec GE added nearly $900 million in revenue. Management expects Q3 Electrification revenue of $3.8 billion to $4 billion.
Wind is still a drag. After a $275 million EBITDA loss in Q2, management expects Q3 to come in near break-even. It is counting on firmer onshore service profits and lower offshore costs. Positive free cash flow is also expected in Q3, though first-half cash flow should run well ahead of the second half.
Cash Conversion Will Show Whether the AI Selloff Sticks
GE Vernova’s growth story depends on how much power AI data centers will need. The Department of Energy projects data centers will use up to 12% of U.S. electrical demand by 2028. The recent selloff raises the question of how hyperscalers will pay for that expansion (GE Vernova is one of seven power, cooling, and networking suppliers we profiled in a free report on the AI infrastructure buildout). A larger backlog, firm turbine pricing and cash flow on pace with July’s raised targets would show that customers are sticking with their commitments.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.