One Big Reason Meta Stock Could Be a Winner Through 2030
Meta's ad pricing power keeps climbing even as a massive legal charge, ballooning capex, and a surprise stock offering sent shares tumbling. Whether those headwinds mask a rare buying window or signal deeper trouble depends on one force quietly reshaping…


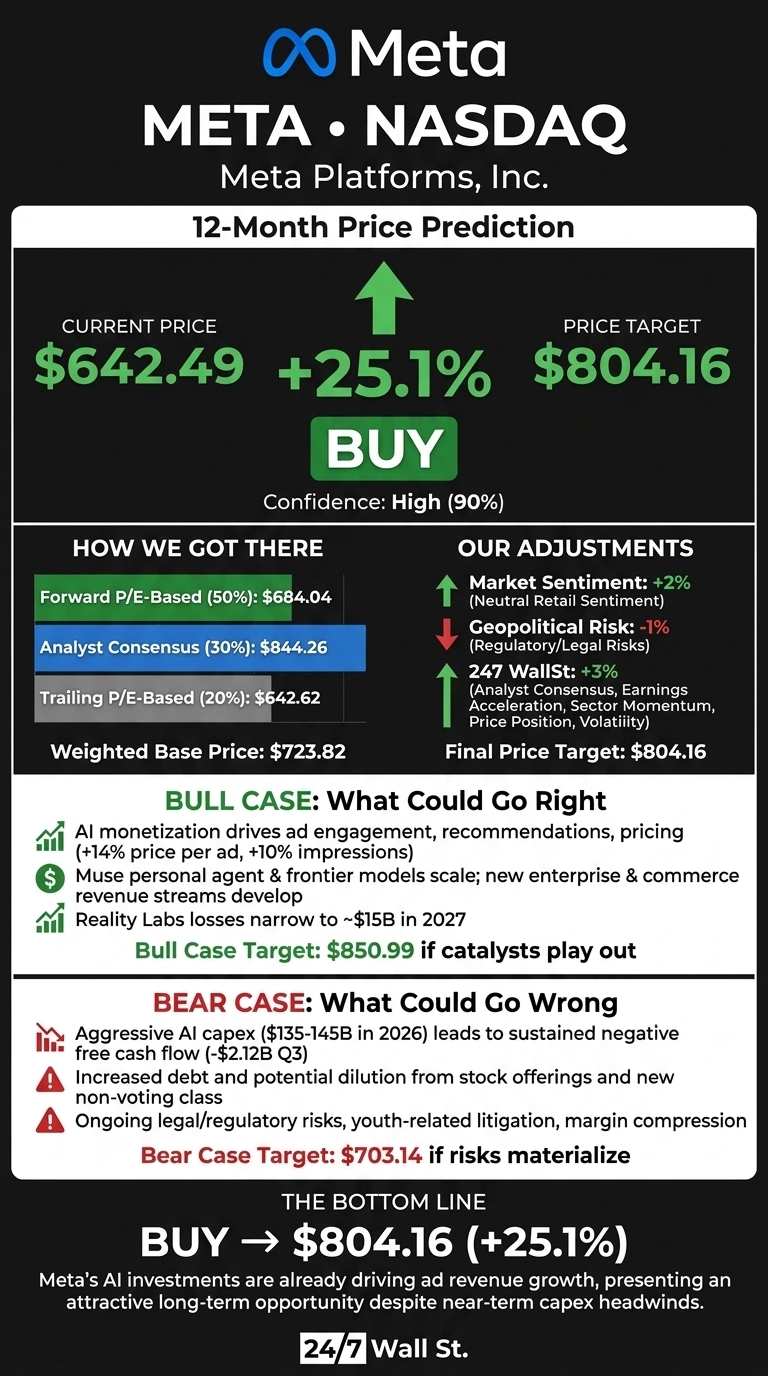
Meta Platforms (NASDAQ:META | META Price Prediction) trades at $642.49. Our 24/7 Wall St. price target is $804.16 over the next 12 months, which means 25.14% upside. Our model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $642.49 |
| Price Target from 24/7 Wall St. | $804.16 |
| Upside/Downside | 25.14% |
| Recommendation | BUY |
| Confidence Level | 90% |

The one big reason I like Meta through 2030 is simple: AI is already making its ad business more valuable.
In Q3, average price per ad rose 14% and ad impressions grew 10%. That pricing power funds everything else Meta is building. Right now, attention on spending, legal costs, and dilution has opened up a gap between price and value.
A Legal Charge and a Stock Offering Hide a Clean Revenue Beat
Shares fell 9.42% over the past week and 13.66% over the past month, leaving them down 2.43% year to date. The stock sits 17.6% below its 52-week high of $779.82.
Q3 revenue came in at $64.601 billion, up 26.07% and ahead of the $63.389 billion consensus. GAAP EPS of $3.83 missed expectations because of a $9.89 billion charge from the settlement with state attorneys general.
EPS would have been $7.40 without that charge. Free cash flow turned negative, which sent shares lower the next day as AI spending weighed on the stock. On Monday, Meta announced a large stock offering to fund its AI expansion.
Why Bulls See $850 and Beyond
The upside goes beyond ads. More than 10 million people in the U.S. and Canada set up the Muse personal agent within six weeks, and about 25% of them use it on any given day. Management plans to earn commerce fees, subscriptions, and enterprise revenue from Muse. It can also sell to the 500 million businesses that already use Meta’s products.
Reality Labs losses are expected to narrow to about $15 billion in 2027, and Q4 revenue guidance is $73 billion to $76 billion. Wall Street largely agrees: 8 analysts rate the stock a Strong Buy and 47 rate it a Buy. Our bull case hits $850.99.

What Could Derail the AI Payoff
Capex guidance for 2026 is $135 billion to $145 billion, and debt stands at $83.7 billion. Somebody has to power and cool that expansion, and we rounded up seven suppliers quietly benefiting from it in a free AI infrastructure report.
The new offering and the planned non-voting share class both raise the risk of dilution. More youth-related trials are also coming. Q3 operating margin fell to 20% from 40%, although operating income would have grown 11% without the legal charge. Our bear case is $703.14.

How Meta Compares to Alphabet and Pinterest
Alphabet (NASDAQ:GOOGL) is Meta’s main rival in digital advertising and is spending heavily on AI too. Its Q2 free cash flow was -$5.855 billion. Alphabet trades near 14x earnings, but its 32% operating margin trails Meta’s 41.44%, which helps justify Meta’s higher multiple.
Pinterest (NYSE:PINS) is a pure social-ad comparison. It posted a GAAP operating loss of $55.2 million in Q2 and grew more slowly than Meta, even though Meta is far larger.
| Company | Trailing P/E | Latest Quarterly Revenue Growth |
|---|---|---|
| Meta | 23 | 26.07% |
| Alphabet | 14 | 24.23% |
| N/M (GAAP loss) | 18.17% |
Against these peers, our target looks reasonable and grounded in comparable valuations.
Meta’s AI Ad Engine Tips the Scale
The 24/7 Wall St. price target of $804.16 carries a buy rating and 90% confidence.
The bull case improves if ad pricing holds up and Muse cuts its computing costs on schedule. The bear case gains weight if dilution speeds up and free cash flow stays negative into 2027. At about 19x forward earnings, the valuation leaves room for upside if execution holds.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $682.52 |
| 2027 | $816.32 |
| 2028 | $934.53 |
| 2029 | $1,073.74 |
| 2030 | $1,144.99 |
Meta’s continued execution on its AI strategy supports these projections. Results could rise with Muse monetization, while litigation or capex overruns could drag them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.