The Next AI Stock to Break Out May Not Be on Most Investors’ Radar
Dell's AI server business is growing at a pace that surprises even seasoned analysts, but a collapsing cash flow figure and negative shareholders' equity are raising serious questions about whether the stock's rally has outrun the fundamentals.


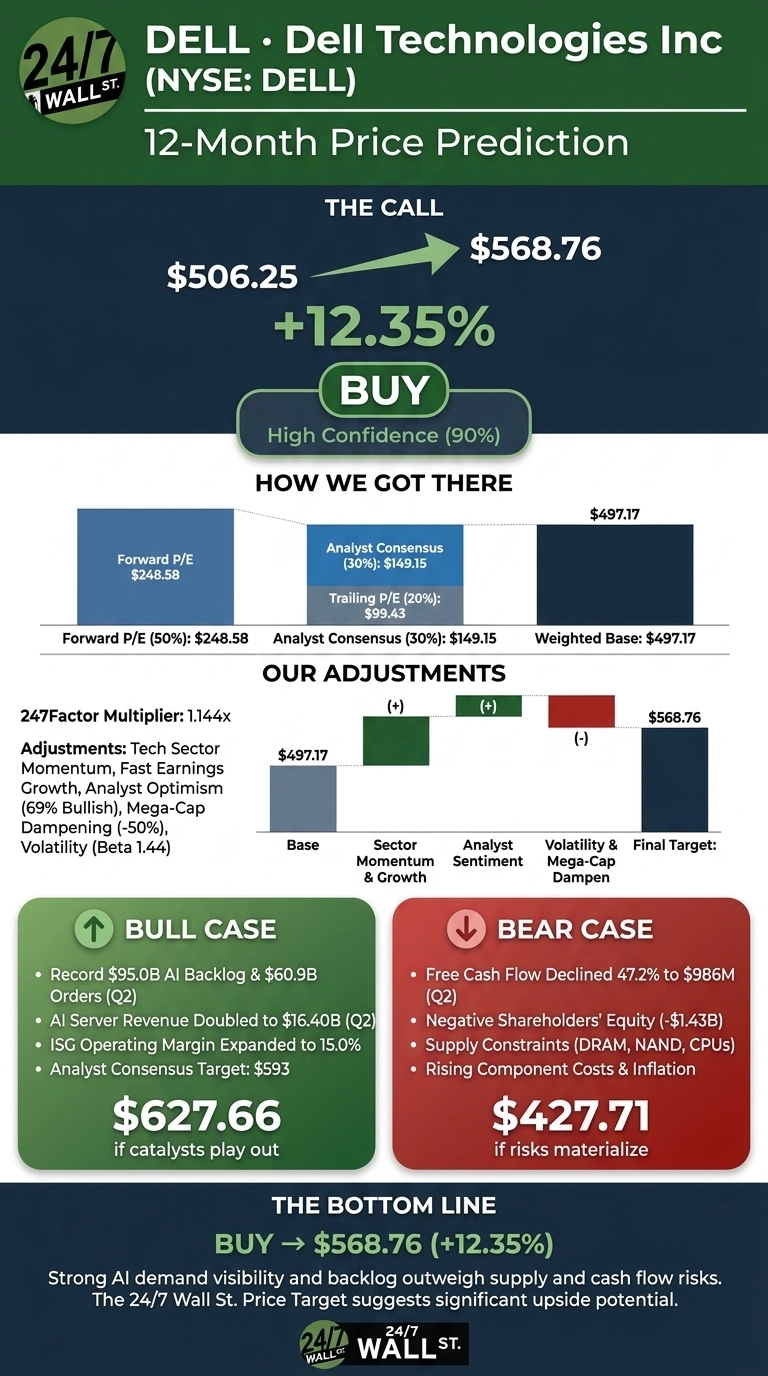
Dell Technologies (NYSE:DELL | DELL Price Prediction) trades at $506.25. The 24/7 Wall St. price target is $568.76 over the next 12 months. That means 12.35% upside and earns a buy rating with high confidence.
| Metric | Value |
|---|---|
| Current Price | $506.25 |
| 24/7 Wall St. Price Target | $568.76 |
| Upside/Downside | 12.35% |
| Recommendation | BUY |
| Confidence Level | 90% |

Dell has grown well beyond its PC beginnings. AI-optimized servers brought in $16.40 billion last quarter, and the AI backlog ended the quarter at a record $95 billion.
A 306% Rally Meets a Volatile October
Dell shares are up 306.45% year to date and 11.31% over the past week, including an 8.38% gain today. The stock is still down 9.94% over the past month and sits about 14.9% below its 52-week high of $594.69.
In fiscal Q2, reported September 1, revenue rose 57.8% to $46.97 billion, beating the $44.44 billion estimate. Non-GAAP EPS came in at $7.04, well above the $4.90 consensus. Management raised full-year revenue guidance to $192 billion and now expects non-GAAP EPS of $25.50.

Why Bulls See $627 Ahead
The bull case reaches $627.66. Dell booked $60.9 billion in AI orders last quarter and now has more than 6,500 AI customers. Management expects $74 billion in AI server revenue this fiscal year, and the expansion goes well beyond the chipmakers (we highlighted seven of the power, cooling, and networking names riding the same wave in a free report here).
Traditional servers grew 122%, and ISG operating margin expanded to 15% from 8.8%. Analysts have a consensus target of $593, with 20 Buy or Strong Buy ratings and no Sells. Price targets from individual firms were not available.

Cash Flow and Supply Limits Are the Risks to Watch
The bear case falls to $427.71. Free cash flow fell 47.2% to $986 million, and shareholders’ equity stands at -$1.43B. Management also noted shortages of DRAM, NAND and CPUs, and said rising component costs account for part of the growth in traditional servers.
There are offsets. Management reported adjusted free cash flow of $8.1 billion and a core leverage ratio of 0.8x. Negative equity also sits alongside large payouts to shareholders: a record $4.3B last quarter.
How Dell Compares to HPE and Super Micro
Hewlett Packard Enterprise (NYSE:HPE) is Dell’s closest rival in servers and storage. HPE’s non-GAAP operating margin of 16.2% beats Dell’s 12.6%. But HPE only expects 13%-17% revenue growth next fiscal year, which helps explain why Dell trades at a premium.
Super Micro Computer (NASDAQ:SMCI) is the pure-play AI server peer. It trades at 9 times earnings, compared with 25 for Dell. Super Micro also used $6.8 billion in operating cash in fiscal 2026 and faces a board review related to export controls. Against this peer group, our target looks reasonable.
| Company | Trailing P/E | Gross Margin |
|---|---|---|
| Dell | 25 | 20.0% |
| HPE | Not meaningful | 28.8% |
| Super Micro | 9 | 10.8% |
Dell Earns a Buy Rating at $506
The 24/7 Wall St. price target of $568.76 has a buy rating and 90% confidence. The backlog is the deciding factor.
Dell trades at about 19 times forward earnings. Bullish prospects strengthen if AI orders keep turning into revenue as supply eases. Bearish risks grow if free cash flow keeps falling further behind earnings. Right now, the evidence favors the bulls.
Below is where our model projects Dell could trade if current trends hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $533.14 |
| 2027 | $554.82 |
| 2028 | $613.76 |
| 2029 | $650.79 |
| 2030 | $713.50 |
These projections assume Dell keeps executing. Faster enterprise AI adoption could lift results above these levels. Long component shortages or a pullback in AI spending could drove them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.