Boeing vs Caterpillar: Which Is Better for a Retirement Portfolio Now?
Two industrial giants both reported earnings this week, and one beat estimates while the other missed, yet both stocks fell. Before you decide which belongs in a retirement portfolio, the balance sheets tell a story the headlines skipped.

Boeing (NYSE:BA | BA Price Prediction) or Caterpillar (NYSE:CAT): which one better fits a retirement-focused portfolio on the numbers? Both industrial giants reported third-quarter results this week. Boeing missed estimates on October 27, 2026. Caterpillar beat estimates on October 29, 2026, yet still sold off. In the premarket on October 30, 2026, Boeing traded at $171.15 and Caterpillar at $637.01. After comparing the two, Caterpillar screens stronger on the income and balance-sheet metrics retirement investors typically consider.
Execution and Business Quality: Caterpillar Takes the Round
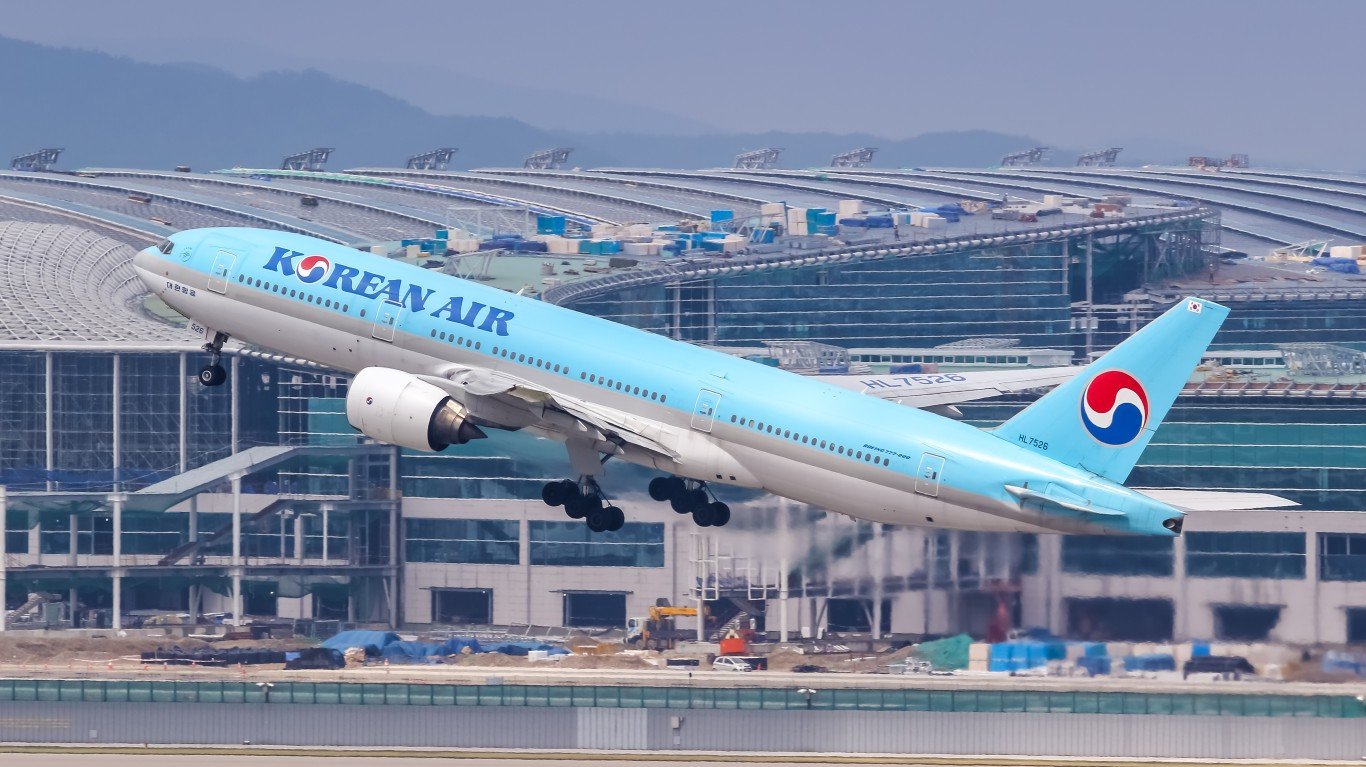
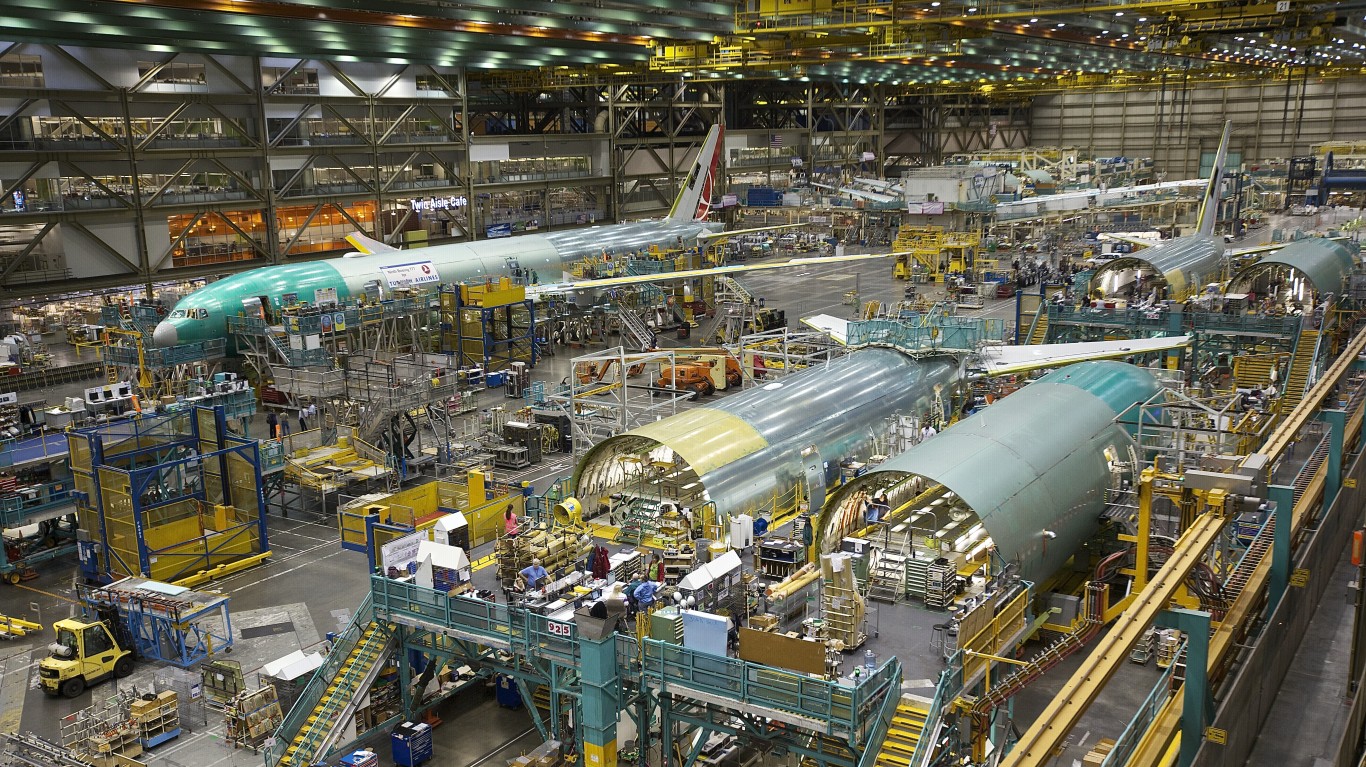
Boeing posted adjusted EPS of −$0.34, missing the −$0.20 consensus, on revenue of $24.19 billion, which also fell short of estimates. Commercial Airplanes ran a negative 6.5% operating margin. Defense, Space & Security revenue grew 15% to $7.93 billion, and the 737-7 and 737-10 both won FAA certification. On the goal of stabilizing 737 output at 47 per month, CEO Kelly Ortberg said, “I’m expecting it’ll take us into next year to get fully stable at this rate.” First 777X delivery is targeted for 2027.

Caterpillar delivered adjusted EPS of $7.20, beating the $7.04 consensus for a fifth consecutive beat, as revenue rose 17.26% to $20.68 billion. Power Generation revenue climbed 30% on data center demand, and management is taking turbine orders into 2030. One note: the quarter included $128 million of IEEPA tariff recoveries, which boosted reported operating profit. Net income still rose 42.9% to $3.29 billion.

Cash Flow and Shareholder Returns: Caterpillar Dominates
Cash returns carry the most weight for income-focused investors. Caterpillar generated $3.8 billion of MP&E free cash flow in the quarter and returned $2 billion to shareholders, including $1.2 billion of buybacks. Its quarterly dividend rose to $1.63 from $1.51. That is an annualized forward payout of $6.52, or about a 1% yield at the current price. The company is a Dividend Aristocrat with 30+ years of consecutive increases. (We ranked ten names with even longer streaks by valuation in a free Dividend Kings report.)
Boeing’s last common ex-dividend date was February 13, 2020. Its only dividend line now covers mandatory convertible preferred stock, at $87 million in Q3. Free cash flow turned positive at $464 million, but full-year 2025 free cash flow was negative $1.88 billion. Debt of $45.9 billion compares with $20.7 billion of cash and marketable securities and just $6.55 billion of shareholders’ equity, against Caterpillar’s $21.48 billion.
Risk and the Road Ahead: Caterpillar Carries Less Baggage
Caterpillar’s selloff came down to expectations, as our earlier coverage of the Caterpillar report detailed. The beat arrived without a raised outlook. Management forecast “moderate sales growth” for the fourth quarter, and fellow AI power names had raised guidance the day before. The stock had run hot at a trailing P/E of 31. It now trades 20.2% lower over one month, at a forward P/E of 22, supported by a record $78 billion backlog.
Boeing’s risks run deeper. Shares are down 24.2% year to date at a forward P/E of 44, and its $10 billion 2029 free cash flow target assumes 777X certification by mid-year 2027. Ortberg admitted that wings “are what have caused us the instability.” A record $745 billion backlog and the Navy sixth-generation fighter win add meaningful upside, yet all of it hinges on execution. Over ten years, Caterpillar shares rose 672% versus 21% for Boeing.
Verdict: Caterpillar Screens Stronger on Retirement Metrics
Caterpillar wins all three rounds. A retiree gets a rising dividend, steady buybacks, profitable growth, and a backlog tied to data center power. Furthermore, the October pullback has trimmed the valuation premium. Boeing’s profile is different: its case rests on a multi-year cash flow recovery that carries heavy leverage and no common dividend. Watch Caterpillar’s 2027 outlook in its next earnings report, plus Boeing’s 737 rate stability and 777X certification progress.


Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.