Satya Nadella Just Took a Shot at Oracle and CoreWeave
Satya Nadella described a business model he called no business at all, named no company, and watched a handful of AI cloud stocks drop after hours. The comment may have been positioning, but the numbers behind it are hard to…

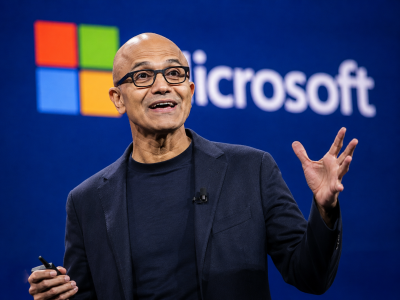
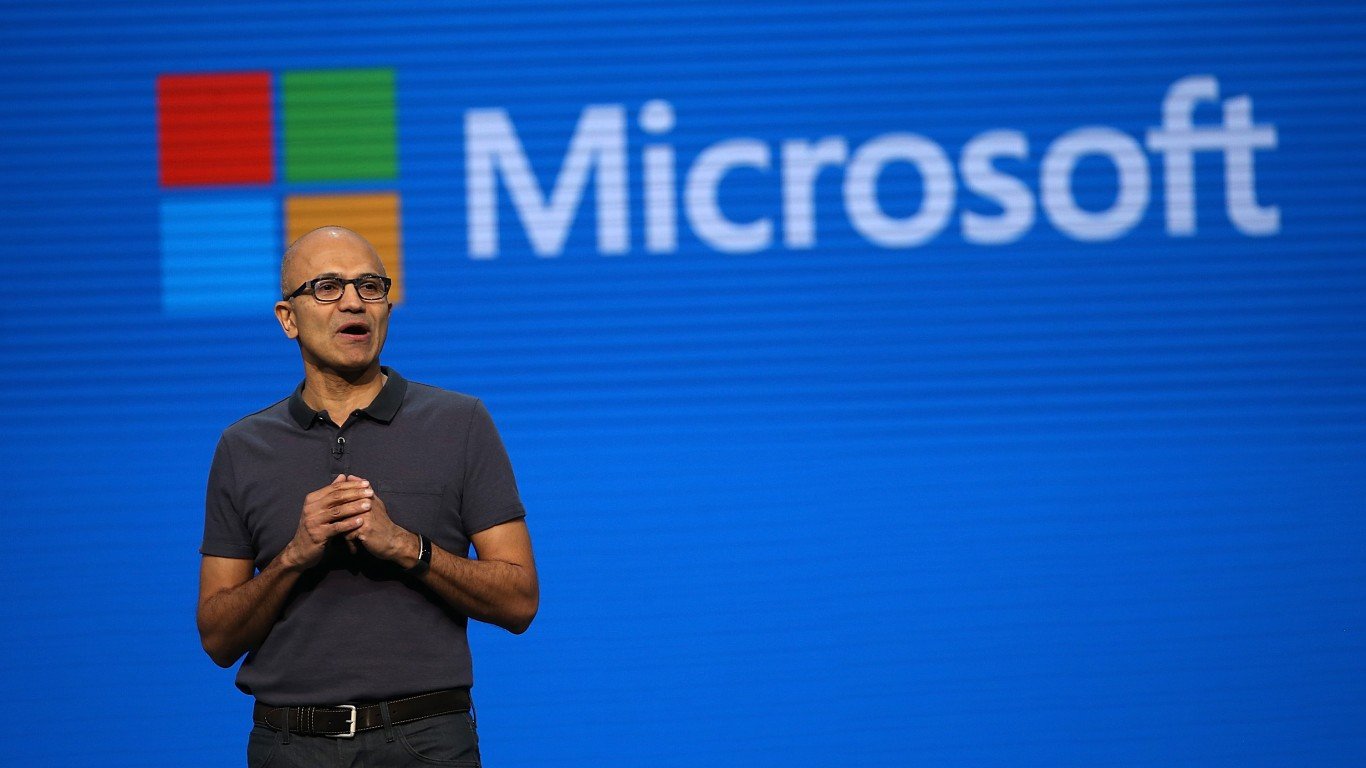
A Big Tech CEO just described a business model that looks a lot like the AI clouds Wall Street has been pricing as the next hyperscalers. The Oct. 28 fiscal Q1 2027 call saw Microsoft (NASDAQ:MSFT | MSFT Price Prediction) chief Satya Nadella dismiss growth built on “like 4 customers who buy a lot of capacity from you and you can show a few quarters of growth, and that’s not a business as far as I’m concerned.”
He named no one. After hours, CoreWeave (NASDAQ:CRWV) fell 4.43%, Nebius Group (NASDAQ:NBIS) dropped 5.12% and Microsoft rose 2.41%. CNBC tied the neocloud selloff to Microsoft CapEx coming in below expectations.
Nadella Would Rather Wait Than Chase Mega-Deals
Responding a Bernstein analyst on enterprise versus AI-native demand, Nadella laid out his terms: “We have large customers who want to buy from us, and we’re open for business with it. And as long as the pricing is right, we may sell them some. If not, we will be patient about building the breadth business.” He called enterprise adoption “a decade-long thing.” His examples: Unilever automating order taking and trade coupon disputes with agents, Rolls-Royce running jet engine maintenance on Foundry, and Austrian bank RBI running 20-plus business processes end to end.
The numbers fund that patience. Azure revenue grew 48%, revenue hit $92.28 billion, and non-GAAP EPS of $4.89 exceeded the $4.72 estimate.

Three AI Clouds That Fit the Description
- Nebius: Three customers made up 24%, 21%, and 14% of Q2 2026 revenue.
- CoreWeave: Its Q1 2026 backlog of $99.4 billion included a Meta Platforms (NASDAQ:META) deal, a $21 billion commitment from Meta, and it flags heavy reliance on a few hyperscalers.
- Oracle (NYSE:ORCL): Management calls demand “really broad-based” and reveals no concentration figure, yet its Abilene campus has handed 75% of total capacity to a single customer. Oracle also announced plans today to return to positive cash flow.
Microsoft Carries Its Own Concentration Risk
CFO Amy Hood said a large Azure commitment signed this quarter offset weaker bookings and caused a smaller-than-usual sequential decline in commercial remaining performance obligation, now $677 billion, up 73%. In July, that backlog grew 84% including OpenAI but only 25% excluding it. Goldman Sachs analyst Gabriela Borges stated in her question that OpenAI was 11% of Microsoft’s revenue in the quarter. Microsoft did not confirm that figure.

Real Warning or Positioning Line?
Both, and the warning still holds. Microsoft makes its case from a position of strength: operating cash flow of $58 billion. CoreWeave posted free cash flow of negative $5.743 billion and $640 million of quarterly interest expense. When one buyer walks, a leveraged specialist loses far more than a diversified hyperscaler does.
The factor to watch: Nebius’s top-three customer share and CoreWeave’s largest-customer disclosures in their next filings. If those shares shrink, the specialists are building breadth and Nadella’s line was mostly marketing. If they rise, his warning becomes harder to ignore.
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.