One Magnificent 7 Stock Could Have a Massive AI Opportunity by 2028
Google is pouring hundreds of billions into AI infrastructure while its stock barely budges, and a growing chorus of analysts thinks the market is badly mispricing what comes next. The gap between where shares trade today and where the math…

Google (NASDAQ:GOOG | GOOG Price Prediction | GOOG Price Prediction) is paying for one of the largest AI buildouts in corporate history, and so far the stock hasn’t priced in the return. Google Cloud revenue rose 82% to $24.77 billion last quarter.
Shares, meanwhile, are up just 2.42% year to date at $320.62. CEO Sundar Pichai told investors, “If anything, over the past year, we’ve gotten more bullish on the opportunities ahead.” So my question is this: can Google hit $750 by 2028?

What’s Holding Google Back Right Now
The cost is what worries investors. Alphabet raised its 2026 capex guidance to $195 billion to $205 billion, and second-quarter free cash flow came in at negative $5.86 billion. Long-term debt rose from $46.5 billion to $98.2 billion, and the buyback was suspended.
Shares are down 4.65% over the past week and 5.96% over the past month as traders prepare for the next earnings report (Investopedia). With a beta of 1.211, Google moves a bit more than the market does, and that works in both directions.
Wall Street Sees 31.7% Upside. Our Model Says 61%
The consensus target is $422.36, or 31.7% upside. Analysts have 13 Strong Buy, 44 Buy, 5 Hold and zero Sell ratings. We peg the base case at $516.10, or 60.97% upside, with a one-year range of $433.56 to $577.64. Confidence in the model is 0.9 out of 1, which is high.

The Street looks too conservative to me. Analysts are 92% bullish, and earnings growth adds 0.03 to our factor, which the model labels strong acceleration. The Cloud backlog stands at $514 billion, and just over 50% of it should turn into revenue within 24 months. A $422 target doesn’t account for that much visibility.
Here’s What It Takes for Google to Reach $750
A move to $750 from today’s price of $320.62 would take a gain of 133.9%. With forward EPS of $14.8986, a $750 share price implies a forward P/E of 50x. The $516.10 base case works out to about 35x on the same EPS, so the bold target needs roughly 16 more turns of multiple expansion.
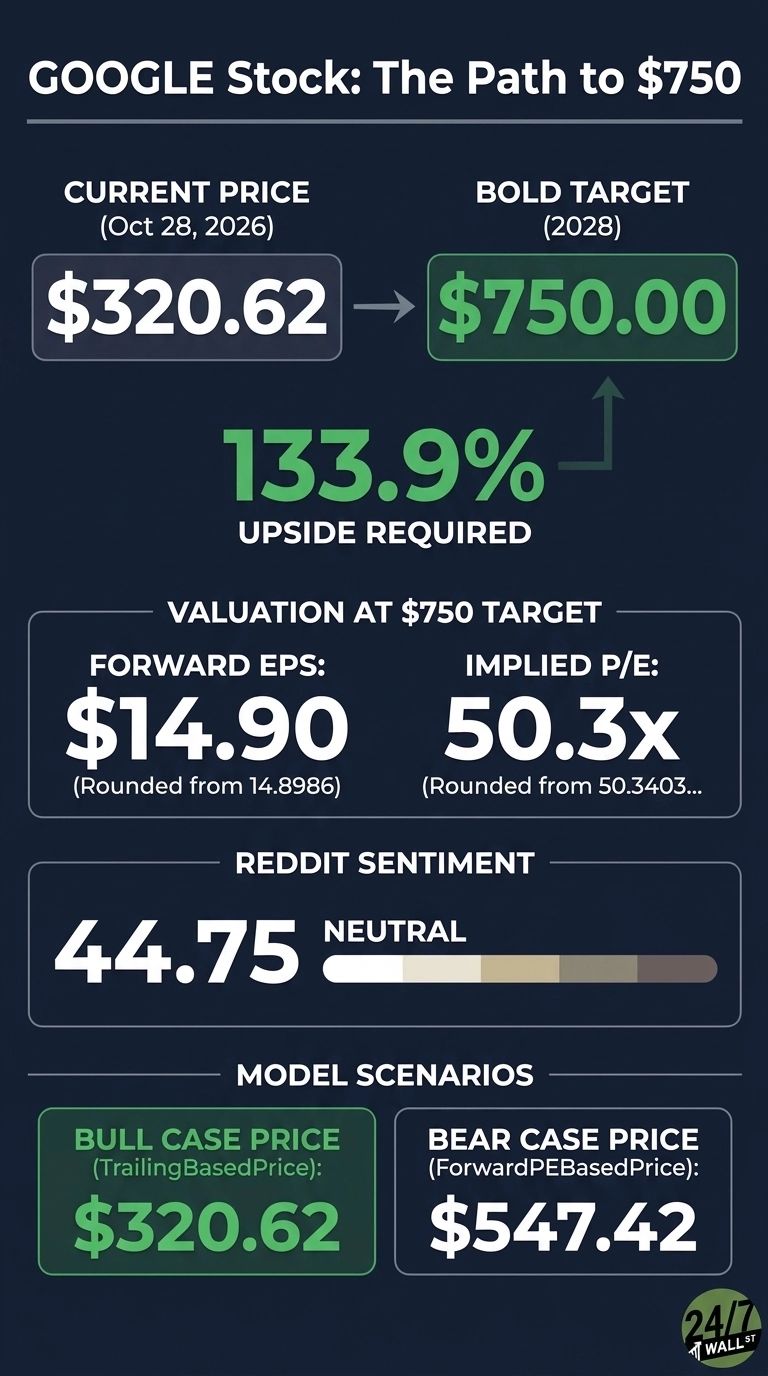
That gap narrows if earnings keep growing. At the consensus growth rate of 27.76%, forward EPS rises to about $19.03, and $750 falls to roughly 39x. Sector momentum and strong analyst support are already baked into the 1.111 adjustment factor.
On the catalyst side, most TPU system sales revenue is expected in 2027, AI Mode has passed 1 billion monthly users, and Google just upgraded the AI world model that hit video game stocks (Bloomberg). Pichai describes this as the “very early innings of what feels like a secular shift.”
The biggest worry is that capex, which management expects to rise significantly in 2027, fails to earn its expected return.
Where Google Trades Today vs. Its Earnings Power
On forward earnings, Google trades at about 22x. That looks cheap for a business with expected growth near 28%.
Shares sit between the 52-week low of $267.73 and the high of $403.96. Over the past decade, the stock has returned 714.25%. Today’s discounted multiple is the starting point for the bull case.
$750 Is a Stretch, But Here’s Why It’s Possible
Getting to $750 requires a 133.9% gain. I’d call that a stretch. Even so, our own 2028 base case of $704.66 isn’t far below it.
Three things have to go right: Cloud has to convert its backlog on schedule, AI features in Search have to keep monetizing, and free cash flow has to recover once spending tops. If AI returns fall short while debt keeps rose, this thesis breaks down.
Don’t expect gains like this every year, but we’ve outlined the plan for how Google could reach $750 in 2028.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.