I’m Betting That The Post-Midterm Flight to Quality Will Kick Microsoft Into Gear
Wall Street's fear gauge just posted one of its biggest jumps in decades, and investors are hunting for safe harbors. One tech giant has a backlog, margins, and a spending problem that could decide whether it earns that role.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Microsoft (NASDAQ:MSFT | MSFT Price Prediction) stands out as markets react to the midterm elections. The CBOE Volatility Index rose from 16.61 on November 4 to 28.18 on November 5. When fear rises like that, investors tend to favor companies built to weather political uncertainty, and Microsoft fits that profile.
What Keeps Pulling Me Back
Microsoft sells infrastructure that businesses cannot switch off: cloud capacity, productivity software, security and now AI agents. Customers sign multiyear contracts for it. Political uncertainty can push money toward companies with strong balance sheets and predictable earnings, and Microsoft fits that profile. The 10-year Treasury yield has also fallen to 4.84% from a 5.31% high on October 5. Lower long-term yields make it easier for investors to pay up for high-quality growth.
Three Data Points Behind My Conviction
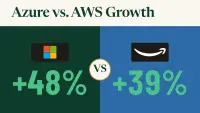
1. Growth is speeding up. Microsoft is a $3.94 trillion company, and growth is still getting faster. Fiscal first-quarter revenue reached $92.28 billion, up 18.8%. Microsoft Cloud revenue hit $63.90 billion, up 30%, and Azure grew 48%. CFO Amy Hood told analysts, “Customer demand continues to exceed available supply.”
2. Future revenue is already under contract. Commercial remaining performance obligations are revenue customers have signed for but Microsoft has not yet booked. That backlog rose 73% to $677.00 billion. Few companies have that much revenue committed in advance.
3. Earnings are steady and the balance sheet is strong. Non-GAAP EPS of $4.89 beat the $4.72 estimate. That made it the 6th consecutive quarter of beating consensus. Operating margin stands at 46.78%, debt-to-equity at 0.29 and interest coverage at 50.88x. Microsoft also returned $10.2 billion to shareholders in the quarter.
How Microsoft Stacks Up Against Amazon and Alphabet
AWS revenue at Amazon (NASDAQ:AMZN) grew 39%. But the stock trades at around 36 times earnings, compared with about 29 for Microsoft. Its trailing free cash flow was negative $42.4 billion.
Alphabet (NASDAQ:GOOGL) looks cheaper at about 13 times earnings, and Google Cloud grew 103%. Still, third-quarter free cash flow came in at negative $9.065 billion. Alphabet also sold shares through a stock offering program and has $27.6 billion of capacity left to sell more, which could dilute existing shareholders. Microsoft expects to remain free-cash-flow positive in FY 2027. That cash-generation gap is a key advantage for long-term investors.
Risk I Watch Every Quarter
My main concern is capital spending. Capital expenditures rose to $39.37 billion, up 102.99%. Fiscal 2026 free cash flow fell 6.46% to $66.99 billion. Third-party capacity that Microsoft expected has been delayed to into the second half of the fiscal year. If AI demand cools, Microsoft will have spent heavily on capacity it doesn’t need.
Two factors offset that risk. Operating cash flow rose 28.73% to $58.00 billion, so the business is generating plenty of cash to fund the expansion. And the $677 billion backlog shows much of that new capacity already has buyers. The capex story extends well beyond Microsoft, of course, and we rounded up seven companies providing the power, cooling and networking behind the AI expansion in a free report here.
Catalysts That Could Power Microsoft’s Next Quarter
For the current quarter, management expects Azure growth of 49% to 50% in constant currency and total revenue of $96 billion to $97.1 billion. Copilot daily users are up over 5x year-over-year. Of the analysts covering the stock, 40 rate it a buy, 12 a strong buy and zero a sell. Over the past decade, the shares returned 888.16%.
When markets get nervous, investors look for quality, and Microsoft’s backlog, margins and cash generation put it near the top of that list. Keep an eye on Azure growth and capital spending in the next earnings report.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.