CoreWeave Just Had Its Best Day Since June 2025 and Says It’s Sold Out Through 2027

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
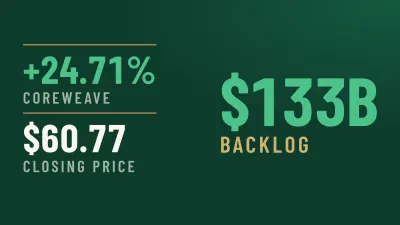
CoreWeave (NASDAQ:CRWV) closed at $60.77 on Wednesday, November 11, 2026. The stock gained $12.04, or 24.71%, which brought its market value to $33.52 billion.
It was the stock’s biggest gain since June 3, 2025 (25.19%) and the third-best day in its history. The only bigger gain came on April 1, 2025 (41.77%), days after the IPO. Wednesday’s move also beat December 19, 2025 (22.64%) and July 30, 2026 (21.51%).
Shares closed at $48.73 on November 10 and at $43.66 on November 5 during the AI selloff. Even with a 25.51% gain over one week, the stock is still down 24.28% over one month and 15.14% for the year. What comes next for the stock depends on how CoreWeave pays for its expansion and how much it relies on NVIDIA (NASDAQ:NVDA | NVDA Price Prediction).
Largely Sold Out Through 2027, Still Selling 2028
On the November 10 earnings call, a Goldman Sachs (NYSE:GS) analyst asked about demand. CEO Michael Intrator answered, “We are largely sold out through 2027.” He said every bit of 2028 capacity CoreWeave has offered so far has sold, with more still to offer, and demand for that year is several times the capacity available.
Third-quarter revenue was $3.7 billion. That was up 168% from a year earlier and more than $1 billion above the second quarter. Backlog, meaning revenue already under contract, grew 138% to about $133 billion. Active power passed 1.7 gigawatts, while contracted power reached 4.6 gigawatts.

Raised Guidance Still Comes With a Net Loss
CoreWeave raised its 2026 revenue outlook to $13.0 billion to $13.3 billion, above the $12.9 billion consensus. It also raised its adjusted operating income outlook to $1.275 billion to $1.375 billion. By year-end, it expects to bring in revenue of $20 billion to $21 billion.
Third-quarter adjusted operating income was $379 million, a 10% margin. Even so, the company posted a net loss of $709 million. Operating profit already covers heavy depreciation on new hardware, and $846 million of net interest expense exceeded what was left.
CoreWeave plans to spend $37 billion to $39 billion on capital projects this year, far more than its revenue. Borrowed money covers the difference.
Rising GPU Prices Support the Bull Case
Intrator said CoreWeave raised GPU prices about 25% in July and about 10% more later in the quarter. Prices kept rising into the fourth quarter.
CoreWeave prices its capacity per megawatt. That figure is the annual revenue from the servers that one megawatt of power can run. New four- and five-year contracts are moving to $20 million to $25 million per megawatt, and short-term capacity has sold for more than $40 million.
About 130,000 GPUs come off contract in 2027 and 170,000 in 2028. Renting them out again at current prices could add annual revenue approaching $10 billion without new capital spending, and that revenue is not counted in the backlog. CoreWeave also said it was the first cloud provider to bring NVIDIA’s Vera Rubin online for Cognition.
Cheaper Loan Report Meets an After-Hours Reversal
After the close, reports said CoreWeave is preparing an investment-grade loan led by Morgan Stanley and MUFG (NYSE:MS, NYSE:MUFG). Early yield talk is 7% to 7.5%, about half the yield on CoreWeave’s existing high-yield debt. Cheaper borrowing would reduce the interest bill.
The loan could launch the week of November 16, and its terms may change. CoreWeave did not comment.
The stock still fell 6.37% to $56.90 in after-hours trading as of 7:59 p.m. ET. One outlet linked the drop to reports that NVIDIA’s board could move to remove CEO Jensen Huang, which NVIDIA has not confirmed. The worry is that a leadership change could alter NVIDIA’s commitments to CoreWeave. NVIDIA owns about 10% of the company and has agreed to buy its unused capacity through April 2032.
Analyst Ratings and Catalysts CRWV Investors Can’t Ignore
Analysts rate CoreWeave a Moderate Buy. The split is 21 Buy, 7 Hold, and 3 Sell ratings, with an average price target of $107.96.
We remain cautious despite the rally. Demand looks durable, but the company still depends on heavy borrowing and still loses money. It also leans on NVIDIA as its supplier, a major owner and the buyer of its unused capacity (we highlighted seven of the companies quietly supporting the AI data-center expansion, from power to cooling, in a free report you can grab here).
NVIDIA reports earnings on November 17, the same week the loan could launch. If the loan prices as discussed and NVIDIA’s commitments hold, that would ease our caution. A close below Tuesday’s $48.73 would deepen it. CoreWeave has not yet set the date of its next earnings report.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.