This Magnificent Seven Stock Could Be Headed for a Major Breakout

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
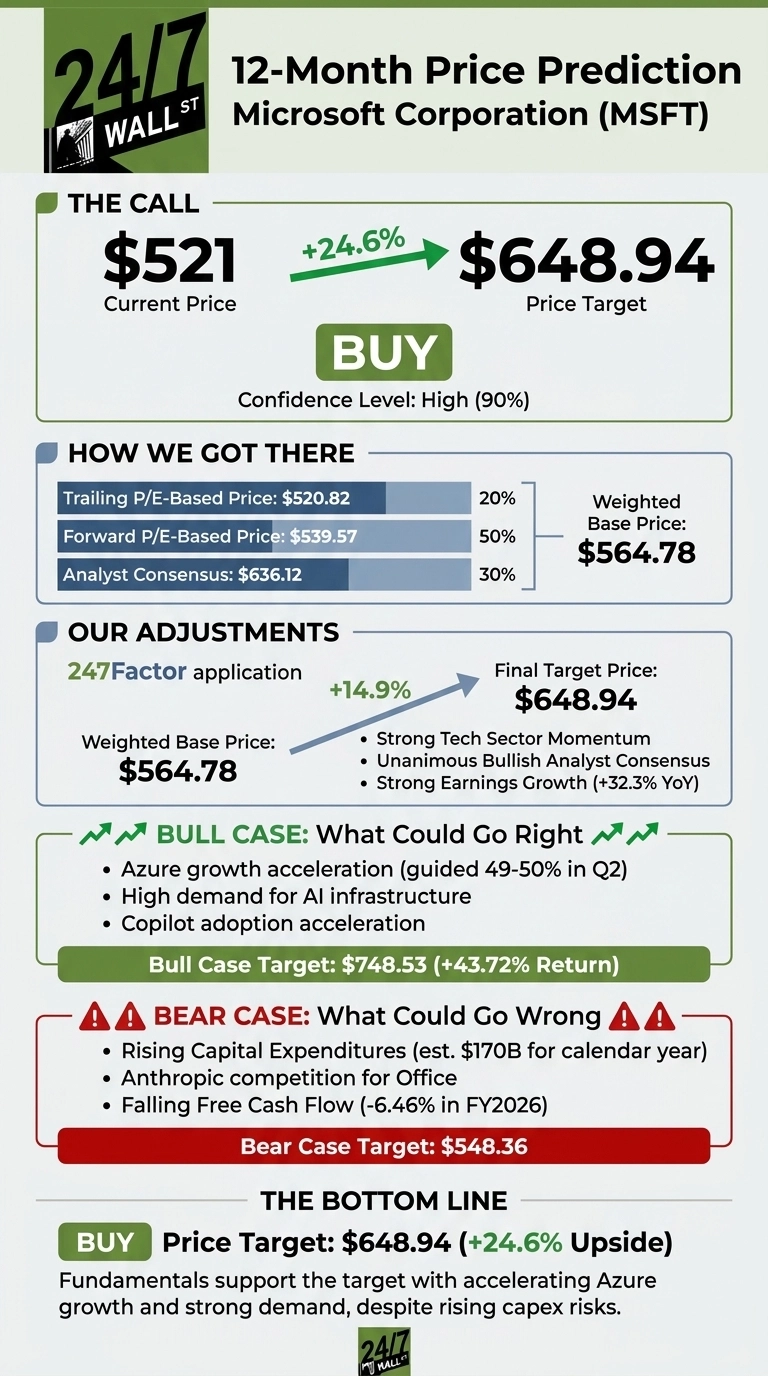
Our 24/7 Wall St. price target for Microsoft (NASDAQ:MSFT | MSFT Price Prediction) is $648.94. That implies 24.6% upside from the current $521. Our model rates the stock a buy, and our confidence is high.
| Metric | Value |
|---|---|
| Current Price | $521 |
| 24/7 Wall St. Price Target | $648.94 |
| Upside/Downside | 24.6% |
| Recommendation | BUY |
| Confidence Level | 90% |

The fundamentals back that view. Azure grew 48% last quarter, and commercial remaining performance obligations reached $677 billion. Wall Street is lopsided too, with 12 Strong Buy and 40 Buy ratings and zero sells. The recent pullback leaves the stock below our target.
Anthropic Headlines Pull Microsoft Off Its Highs
Shares have fallen 6.26% over the past week and 3.72% over the past month. Since October 1 they’re up 1.62%, and year to date they’re up 8.41%. The stock trades 6.8% below its $559.15 52-week high and 49.5% above its $348.54 low.
The latest selling followed Anthropic’s launch of tools that rival Office and Excel on November 10, and Microsoft weighed most heavily on the Dow the next day.
Fiscal Q1 2027 revenue came in at $92.28 billion, ahead of the $90.75 billion estimate. Non-GAAP EPS of $4.89 beat the $4.72 consensus.

Why Bulls See $748 Within Reach
Management guided Q2 Azure growth to 49% to 50% in constant currency, and CFO Amy Hood said “customer demand continues to exceed available supply.”
Foundry has more than 120,000 customers, and its revenue more than tripled. Daily Copilot users rose nearly 50% from the prior quarter. The bull case reaches $748.53, a 43.72% return.

Capex and AI Rivals Are the Risks Worth Watching
Q1 capital spending reached $45.2 billion, and management expects about $170 billion for the calendar year. Fiscal 2026 free cash flow fell 6.46%, and Windows OEM and Devices revenue dropped 22%. Anthropic’s Office push also threatens a core business.
Offsetting those concerns, operating cash flow rose 28.73%, and Hood argued that “each dollar of CapEx has the potential to support more revenue and higher returns over time.” Our bear case is $548.36.

How Microsoft Compares to Alphabet and Amazon
In AI and cloud, Alphabet (NASDAQ:GOOGL) competes directly. With Google Cloud up 103%, Alphabet trades at a P/E of 13. That multiple is inflated by large equity-security gains earlier in the year, though, and Q3 free cash flow came in at -$9.065 billion.
AWS, the largest rival to Azure, is run by Amazon (NASDAQ:AMZN). AWS grew 39%, and Amazon trades at a P/E of 37, with a much thinner operating margin.
| Company | P/E | Operating Margin |
|---|---|---|
| Microsoft | 29 | 46.78% |
| Alphabet | 13 | 32.0% |
| Amazon | 37 | 11.2% |
Microsoft has the highest margin of the three at a mid-range multiple. Against this peer group, the 24/7 Wall St. price target looks reasonable.
Microsoft Earns Its BUY Rating
I’m sticking with the 24/7 Wall St. price target of $648.94, a buy rating and 90% confidence. What tips the scale for me is Azure demand that still exceeds supply.
The thesis strengthens if Azure delivers the guided acceleration. It weakens if capex keeps going up while Copilot monetization stalls. For now, the fundamentals support the target.
Looking further out, here is where our model projects Microsoft could trade if current growth and market conditions remain.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $520.93 |
| 2027 | $648.94 |
| 2028 | $745.05 |
| 2029 | $853.82 |
| 2030 | $926.15 |
The projections rest on Microsoft continuing to execute on its AI infrastructure strategy. Faster Copilot adoption could push results higher, while capex returns that disappoint could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.