One Magnificent Seven Stock Looks Ready for Its Next Big Move

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
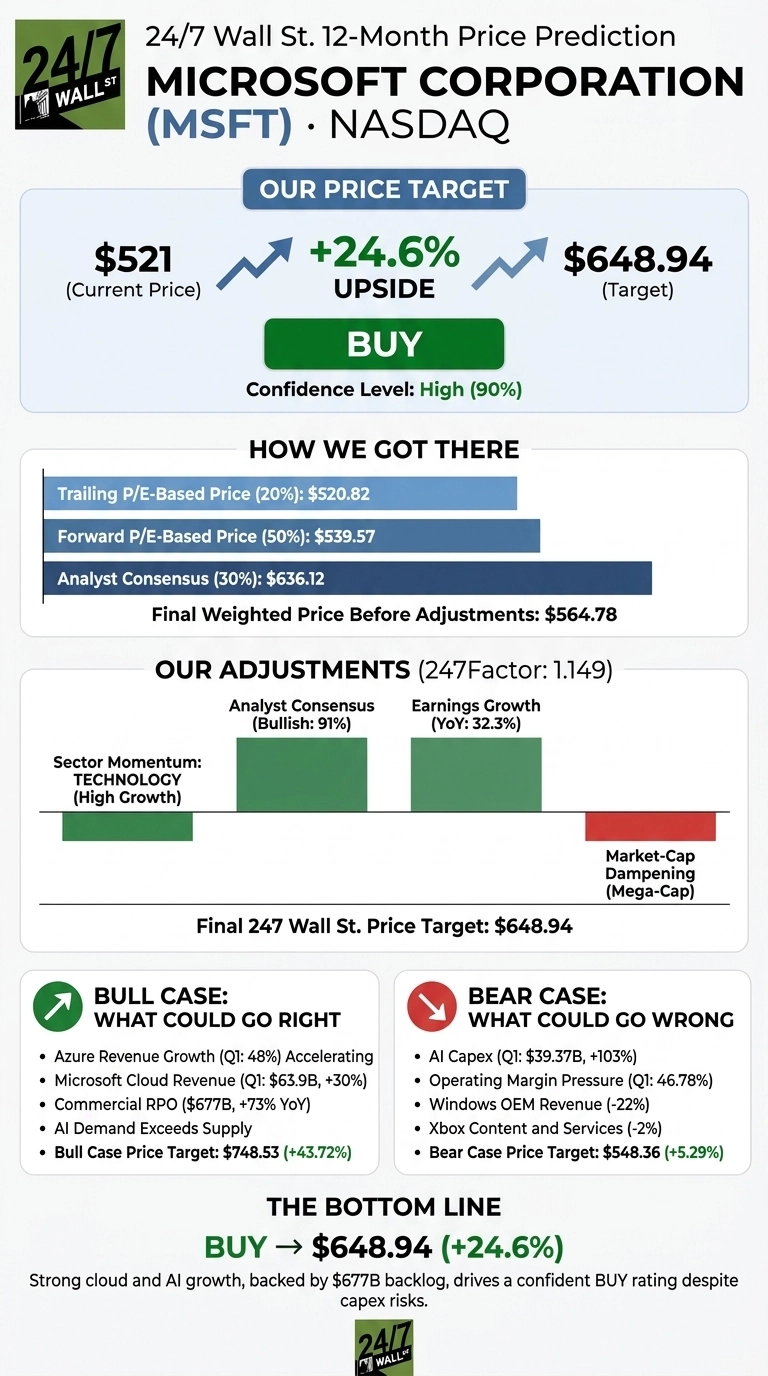
Shares of Microsoft (NASDAQ:MSFT | MSFT Price Prediction) trade near $521 after a rough week. The 24/7 Wall St. price target sits at $648.94, suggesting 24.6% upside over the next 12 months. The stock gets a buy rating from our model with high confidence.
| Metric | Value |
|---|---|
| Current Price | $521 |
| Price Target from 24/7 Wall St. | $648.94 |
| Upside/Downside | 24.6% |
| Recommendation | BUY |
| Confidence Level | 90% |

The setup looks good to me. Azure grew 48% last quarter, Microsoft Cloud growth sped up to 30%, and commercial remaining performance obligations hit $677 billion.
Even so, the stock trades below the $532.60 it reached when the October 28 earnings report came out. The market is reacting to competitive headlines while the signed backlog keeps growing.

Anthropic Headlines Pull Microsoft Off Its Highs
Shares fell 6.26% over the past week and 3.72% over the past month, though they remain up 8.41% year to date. Microsoft trades about 6.8% below its 52-week high of $559.15 and about 49.5% off its low of $348.54. Selling picked up after Anthropic revealed tools that compete with Office, including an Excel rival. MarketWatch then named Microsoft the biggest drag on the Dow.
The fundamentals point the other way. Fiscal Q1 2027 revenue came in at $92.279 billion, up 18.8% and ahead of the $90.75 billion estimate. Non-GAAP EPS of $4.89 beat the $4.72 consensus.
Why Bulls See $748 Within Reach
Management guided Azure growth to 49% to 50% in constant currency for fiscal Q2. CFO Amy Hood said “Customer demand continues to exceed available supply.”
Foundry revenue more than tripled, and daily Copilot users rose nearly 50% from the prior quarter. Wall Street agrees: 12 analysts rate the stock Strong Buy, 40 rate it Buy, and none rate it Sell. The bull case reaches $748.53, a 43.72% return.

Capex and AI Rivals Could Cap the Rally
Microsoft expects calendar-year capex of about $170 billion. Management also expects Microsoft Cloud gross margin of roughly 65% and operating margins slightly lower than a year ago. Windows OEM revenue is guided to decline in the mid-30s% range.
Operating cash flow rose 28.73% to $58 billion, and management expects free cash flow to stay positive this fiscal year. The bear case sits at $548.36, which still suggesting a gain.
How Microsoft Compares to Alphabet and Amazon
For AI infrastructure customers, Alphabet (NASDAQ:GOOGL) competes directly. Cloud revenue at Google grew 103%, but free cash flow was negative $9.065 billion last quarter. Its P/E of 13 is lowered by large equity gains.
AWS, the largest cloud rival, is run by Amazon (NASDAQ:AMZN). AWS grew 39%, while Amazon trades at a 37 P/E with much lower margins.
| Company | P/E | Cloud Growth | Operating Margin |
|---|---|---|---|
| Microsoft | 29 | 48% | 46.78% |
| Alphabet | 13 | 103% | 32.03% |
| Amazon | 37 | 39% | 11.16% |
Of the three, Microsoft posts the highest margins and trades below Amazon’s multiple, so I think our 24/7 Wall St. price target is reasonable.
Microsoft Earns a Buy Rating From Our Model
Our 24/7 Wall St. price target of $648.94 comes with a buy rating and 90% confidence. The key factor for me is backlog visibility.
The case gets firmer if Azure delivers on its 49% to 50% guidance. It undermines if capacity delays or Anthropic’s Office push slow Copilot monetization. On the current evidence, the long-term case remains intact.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $648.94 |
| 2027 | $658.34 |
| 2028 | $745.05 |
| 2029 | $853.82 |
| 2030 | $926.15 |
The projections rest on Microsoft continuing to execute its current strategy. Significant upside or downside could come from returns on AI capex or competitive pressure on Microsoft 365.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.