Microsoft Could Be Worth Far More as Its Cloud and AI Businesses Scale
Azure is accelerating, the commercial backlog just hit a staggering new record, and Wall Street is nearly unanimous on the stock. So why does free cash flow keep shrinking, and what does that mean for where Microsoft goes from here?


Shares of Microsoft (NASDAQ:MSFT | MSFT Price Prediction) trade at $534.55. The 24/7 Wall St. price target sits at $636.14, which implies 19% upside over 12 months. The stock gets a buy rating with high confidence.
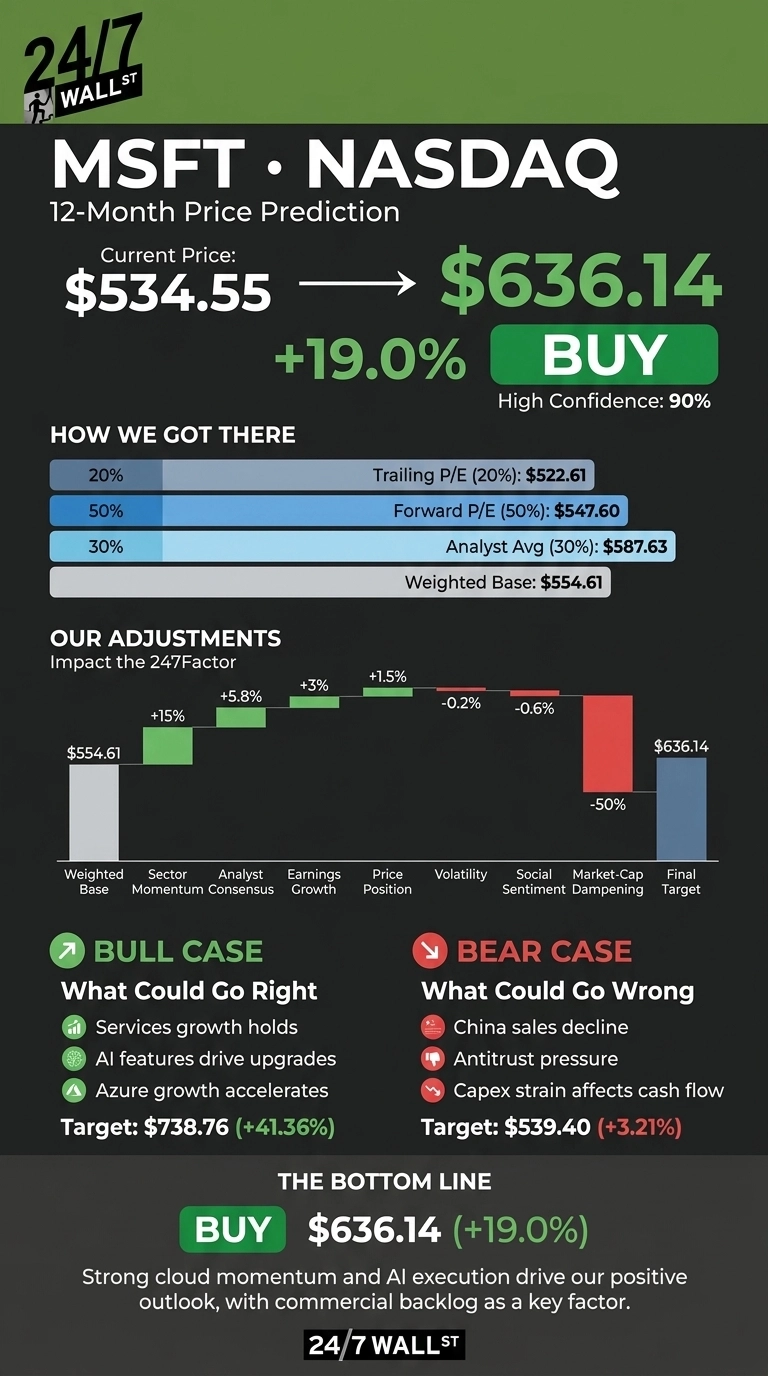
| Metric | Value |
|---|---|
| Current Price | $534.55 |
| Price Target from 24/7 Wall St. | $636.14 |
| Upside | 19.0% |
| Recommendation | BUY |
| Confidence Level | 90% |

Azure Acceleration Pushes Shares Toward Highs
Microsoft is up 4.24% this week, 8.22% over the past month and 11.23% year to date. It sits 2.7% below its 52-week high of $549.20.
Fiscal Q4 revenue reached $90.01 billion, exceeding the $87.63 billion estimate, and EPS of $4.74 beat the $4.24 consensus. Azure grew 43%, and commercial backlog rose 84% to $678 billion.

Why Bulls See $738 and Beyond
Management guided Q1 Azure growth to about 45% and said “demand continues to exceed available supply.” Microsoft 365 Copilot has passed 30 million paid seats.
Wall Street’s consensus target is $587.63, with 14 Strong Buy and 39 Buy ratings. Our bull scenario reaches $738.76.

Capex Strain Is the Risk to Track
Fiscal 2026 capex rose 79.62% to $115.95 billion, and free cash flow fell 6.46%. Microsoft Cloud gross margin also slid to 65%.
On the other side, operating cash flow grew 34.35%, and much of the spending goes to short-lived chips that can be restricted (we featured seven suppliers supporting this kind of expansion, from power to cooling, in a free AI infrastructure report). The bear case sits at $539.40.

Is Microsoft Pricier Than Alphabet and Amazon?
Google parent Alphabet (NASDAQ:GOOGL) competes directly through Google Cloud.
Amazon (NASDAQ:AMZN) runs AWS, the largest rival hyperscaler. Both trade at lower forward multiples than Microsoft. Microsoft’s higher margin helps explain its modest premium, which makes our target look reasonable.
| Company | Forward P/E | Operating Margin |
|---|---|---|
| Microsoft | 25x | 45.1% |
| Alphabet | 23x | 34% |
| Amazon | 24x | 13.7% |
Cloud Momentum Earns a BUY Rating
A 24/7 Wall St. price target of $636.14 comes with a buy rating and 90% confidence. The commercial backlog is the deciding factor. Keep an eye on whether Azure growth keeps speeding up and whether free cash flow keeps falling without margin recovery.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $636.14 |
| 2027 | $702.42 |
| 2028 | $775.60 |
| 2029 | $856.41 |
| 2030 | $945.64 |
The projections rest on Microsoft continuing to execute its current strategy. Faster Copilot adoption or a decline in AI demand could shift them sharply.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.