Fastenal Raised Its Dividend Twice in 2026. Why Wall Street Still Isn’t Sold on This Dividend Aristocrat.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Fastenal (NASDAQ:FAST | FAST Price Prediction) joined the S&P 500 Dividend Aristocrats, the group of index members with at least 25 straight years of dividend increases, in January 2024, Barron’s reported. The distributor raised its quarterly payout twice this year. It increased from $0.22 to $0.24 in January and then to $0.26 in July. Analysts still aren’t convinced. Their consensus target of $51.15 is below Wednesday’s open at $54.26.


Fastenal had a two-for-one stock split in May 2025, so the 2025 drop from $0.44 to $0.22 reflected the split, not a dividend cut.
Contract Customers Are Paying for the Raises
Third-quarter revenue rose 15.5% to $2.4633 billion[1]. Per-share earnings of $0.35[1] topped the $0.34 consensus estimate. Contract customers made up 76.5% of revenue, up from 73.8%[1], and sites spending $50,000 or more a month grew to 3,288 from 2,771. These are the accounts where Fastenal stocks inventory on the customer’s own floor. Jeffery Watts, president and chief executive, said: “The quarter was driven mainly by market share gains through our key account strategy and new contract wins.”[2]

Cash flow covers the payout. Operating cash flow came to about $422 million, or 105% of net income[2], and the company paid $298.2 million[1] in dividends.
How Earlier Bullish Calls on Fastenal Have Held Up
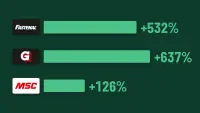
Our October 2025 piece, Fastenal: An Overlooked Industrial Gem to Unlock Decades of Steady Income, made four points: a growing dividend, customer commitment driven by on-site inventory tools, strong cash flow, and growth with contract customers. Since that article was published, the stock has gained 35.1%. Three of the four points still hold. FASTBin and FASTVend sales grew 17.6%[1]. Cash flow has weakened somewhat: capex guidance rose to $310 million to $330 million[1] from $230.6 million. That piece also noted a rich valuation, and the stock is more expensive now.
A May 2026 follow-up, Fastenal (FAST): The Quiet Compounder Nobody Talks About Is a Buy-and-Hold-Forever Stock, made the long-term case.
Valuation and Margins Keep Analysts Cautious
Fastenal trades at 45 times trailing earnings and 39 times forward earnings. The P/E ratio is the share price divided by earnings per share. The stock yields only 1.9%, and in 2025 dividends took up 79.8% of net income[3]. That share is the payout ratio. Gross margin lost about 50 basis points to customer mix[1], and price increases are adding less to growth. Watts said, “As we anniversary some of that pricing, our reported growth is going to naturally have less help from price.”
Peers make the premium harder to justify. W.W. Grainger (NYSE:GWW) raised its quarterly dividend 10%, and it raised its full-year guidance after third-quarter revenue grew 11.3%. Grainger’s CEO D.G. Macpherson cited “an improving demand environment.” MSC Industrial Direct (NYSE:MSM) reported core customer growth of about 10%. Fastenal still leads on profitability. Its 21.5%[1] operating margin is well above Grainger’s 16.0% and MSC’s 10.9% adjusted margins.
Verdict: Earned Skepticism, Durable Dividend
The skepticism about the stock price is justified. At 39 times forward earnings, a 1.9% yield gives buyers little room for error. The dividend itself looks secure. Contract growth, on-site inventory tools, and strong cash conversion all support more increases.
The main risk to that view is gross margin. CFO Max Tunnicliff expects a 50- to 60-basis-point[2] drag from the shift toward larger customers. If the hit grows beyond that while the pricing boost fades, a payout ratio near 80% would leave little room for future increases.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.