Between IREN and CoreWeave Here’s Who Has the Cleaner Path to a Sustained 30% Rebound

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
CoreWeave (NASDAQ:CRWV) and IREN (NASDAQ:IREN) both grew their AI cloud businesses quickly last quarter. Both stocks then fell after NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) signaled caution on financing. CoreWeave trades at $44.91, down 27.72% in a month. IREN sits at $14.41, off 45.87%. Customers want compute from both, but the two pay for growth in very different ways.
Price Hikes Lift CoreWeave as IREN Sheds Its Mining Past
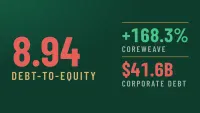
CoreWeave’s Q3 revenue reached $3.66B, up 168.3%[1] year over year. CEO Michael Intrator called it “a breakout quarter”[1] and said adjusted operating margins hit double digits “a quarter ahead of plan.” Pricing power drove much of that. Management raised prices across its product lines by 25% in July and another 10%[2] later in the quarter. Debt weighs on results, as interest expense of $846M[1] pushed the company to a $709M net loss and GAAP EPS of -$1.27.
IREN’s quarter was all about the shift away from mining. AI Cloud revenue hit $200M[3], while Bitcoin (CRYPTO:BTC) mining revenue fell to $28M from $67M. An AI Cloud gross margin of 86%[3] shows the model makes money once GPUs go live. Horizon 1 also entered service[3] for Microsoft (NASDAQ:MSFT). Still, the $263M[3] net loss shows IREN isn’t yet big enough to cover its costs.
| Business Driver | CoreWeave | IREN |
|---|---|---|
| Revenue Backlog | ~$132.5B[1] | $20.3B[3] |
| Core Model | GPU cloud plus Forge software | Owns its land, power and data centers |
| Next Milestone | $20B to $21B[1] annualized revenue run rate exiting 2026 | More than $4B[3] ARR (annual recurring revenue) in service by January |
One Rents Scale, One Owns the Dirt
CoreWeave says it has 10 times[2] as much qualified demand as available capacity through 2027. It also expects about $9 billion[1] in customer prepayments and deposits over the next three months. With lenders turning cautious, that cash means less dependence on capital markets (the same AI buildout tailwind we broke down across power, cooling and networking suppliers in a free report, here). More than 130,000 GPUs[2] come off contract in 2027, which lets CoreWeave reprice hardware that is already paid off.
IREN owns every layer of its business. “We own the land, the power and the data centers under all of it,”[3] co-CEO Daniel Roberts said. That control is expensive: IREN plans roughly $15B[3] of remaining FY27 capex, and $6B of it still needs funding. Net debt rose to $4.43B from $216M[3], so IREN now carries far more financial risk.
January Will Decide Whether IREN Earns Trust
I will be watching IREN’s ARR milestone. A design change requested by a customer and supplier delays pushed it to January, possibly the end of February[3]. Another delay would hurt its credibility with big investors. For CoreWeave, keep an eye on Q4 interest expense, guided at $1.05B to $1.15B[1]. That number will show whether higher prices keep outrunning financing costs.
Why I Lean Toward CoreWeave for a Durable Rebound
For a sustained 30% rebound, I prefer CoreWeave. I would be counting on execution at a business already running at real scale, with $9B in incoming customer prepayments. The leverage still worries me. An at-the-market share sale program for up to 35M shares[1] could also limit gains.
IREN offers more upside and more all-or-nothing risk. Its 61.85% drop this year reflects deep doubt. Even so, a new five-year contract at about $22M per IT-MW[3] (annual revenue per megawatt of computing power) with 90% of GPU capex prepaid shows customers value its sites. Until IREN closes the $6B funding gap and the ARR goes live, I see it as a turnaround story for investors who can handle sharp swings.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.