Bill Ackman Opened About $2 Billion in New Positions in Alcon and Intercontinental Exchange

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
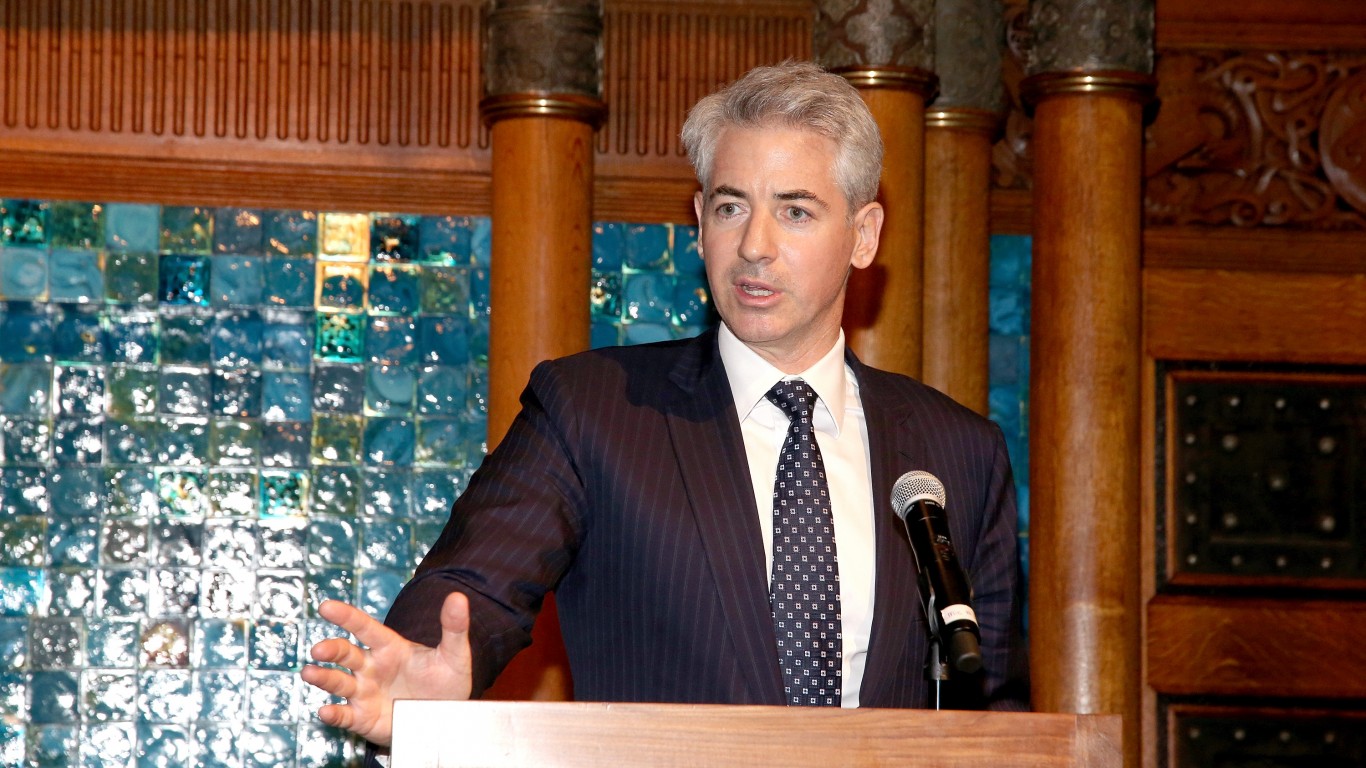
Bill Ackman’s Pershing Square Capital Management opened two new positions in the third quarter. Its latest 13F shows a stake in Intercontinental Exchange (NYSE:ICE | ICE Price Prediction) worth $1.01 billion and a stake in Alcon (NYSE:ALC) worth $954 million, both measured as of September 30, 2026. The filing was submitted in mid-November and records what Pershing owned at quarter-end.
Pershing runs a concentrated book built around a small number of large, durable businesses that generate a lot of cash. Each new name therefore takes up a meaningful share of the fund.
The same filing shows Pershing’s Microsoft (NASDAQ:MSFT) stake fell to 4,064,779 shares from 6,206,730, though Bill Ackman said on X that the fund bought two million deep-in-the-money over-the-counter Microsoft options in July, with a strike price of about $310 and a term of two and a half years, and that he remains bullish (Bill Ackman Says His Microsoft ‘Sale’ Was Really a Swap Into Options).
ICE Turns Market Turbulence Into Recurring Cash
ICE runs exchanges, including the New York Stock Exchange, along with clearing houses and mortgage technology. In the third quarter, it posted adjusted EPS of $2.02[1], ahead of the $1.97 estimate. Net revenue climbed 20.7%[1] to $2.765 billion. Recurring revenue rose 7%[1], and the adjusted operating margin expanded to 61% from 59%. Year-to-date adjusted free cash flow hit a record $3.7 billion[2].
The CFO summed up the model himself: “steady compounding at the core and upside operating leverage when our markets are active.”[2] At $170.10, the stock trades at 20x forward earnings. The main thing to watch is $23.3 billion[1] of debt ahead of the MarketAxess (NASDAQ:MKTX) deal, which is expected to close in Q1 2027.


Alcon Offers Margin Expansion at a Discount
Alcon makes surgical equipment for eye procedures and vision care products such as contact lenses and dry-eye drops. Third-quarter adjusted EPS of $0.91[3] beat the $0.89 consensus. Revenue of $2.717 billion[3] missed expectations. Gross margin rose to 59.7%[3] from 56.3%, and free cash flow for the first nine months exceeded $1.3 billion[4]. Part of the margin gain came from $58 million[3] in one-time duty refunds. Implantables fell 2%[3] as competitors pressed into U.S. lens implants.
CEO David Endicott said the company remains “on track for our 2026 objectives with year-to-date sales growth of six percent and double-digit core EPS growth.”[3] Shares sit at $74.31, down 4.61% year-to-date and below the 52-week high of $87.22. The stock trades at 19x forward earnings. The trailing multiple of 54x reflects a $402 million lens-program impairment taken in the second quarter.


What Retirement Investors Should Weigh in Ackman’s Picks
Both stocks are lower-volatility holdings, with betas of 0.844 for ICE and 0.716 for Alcon. Each also returns cash through buybacks. Note that 13F data runs weeks behind, and Pershing’s current position sizes are unknown.
This pair is worth following as a research lead, provided you understand the thesis behind each name. ICE is the cleaner cash-flow story: its recurring data and clearing revenue tends to hold up whether markets are calm or volatile.
Alcon is a margin-recovery story. It will need new lens establishments to win back share in U.S. implants before the discount to its highs closes. Retirement investors who want durable compounders can use Ackman’s picks as a starting point. Run your own check on debt, competitive pressure, and valuation.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.