Suze Orman Warns Retirees About Claiming Benefits at 62

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

If you really want to retire at 62 and collect Social Security, go for it.
You’ve worked hard enough. You’ve paid your dues. Now it’s your time to relax and collect what’s rightfully yours, right?
Finance expert Suze Orman has a clear answer: not so fast. Claiming benefits early is, in her view, one of the costliest mistakes a retiree can make. Her consistent advice is to wait until you reach your Full Retirement Age (FRA) before filing, and ideally delay all the way to age 70 if your health and finances allow. For most workers born in 1960 or later, the FRA is 67.
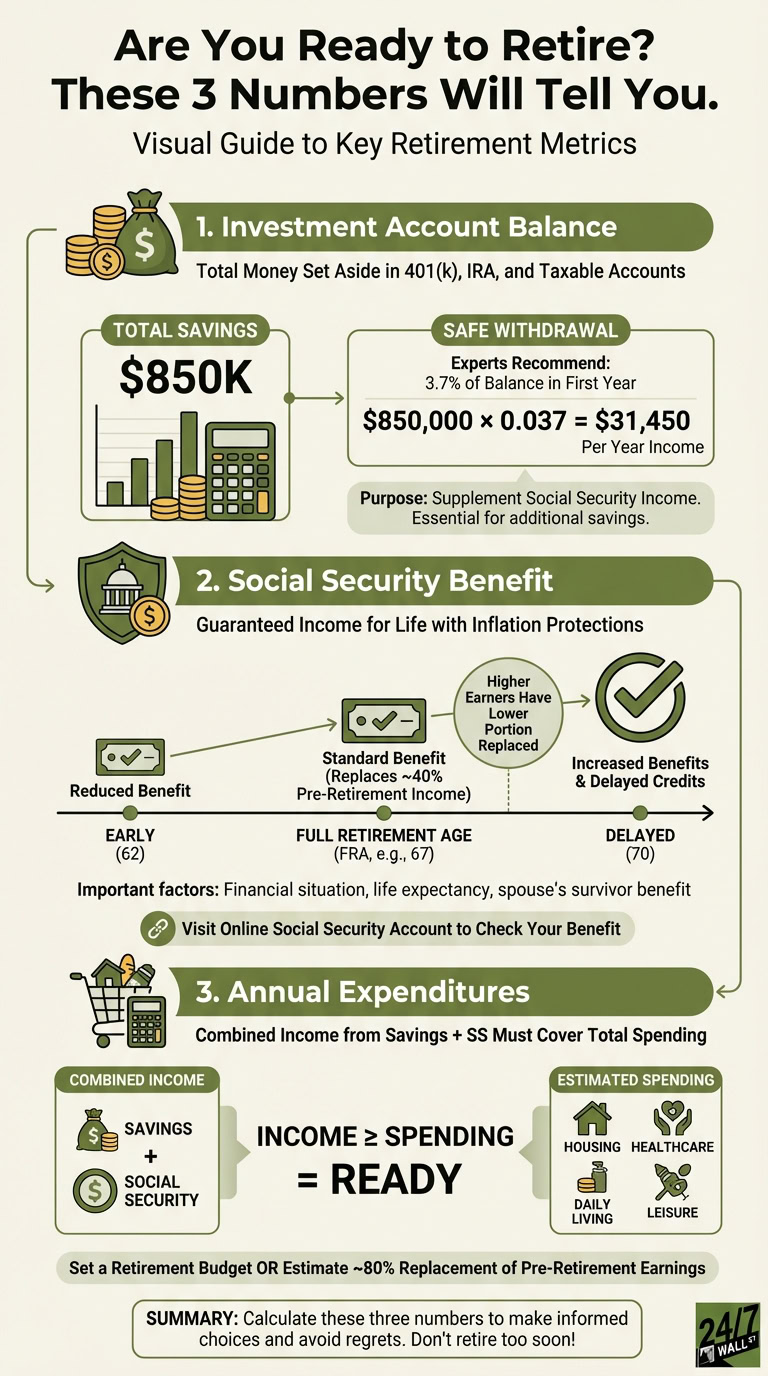
The numbers behind Orman’s warning are hard to dismiss. Claiming at 62 permanently reduces your monthly benefit by 30% compared to what you would receive at FRA. Wait until 70, and your payment grows by 8% for every year you delay past FRA. Orman has stated the difference plainly: the benefit at 70 is more than 75% higher than the benefit at 62.
Trending Now: How Many Americans Have Managed to Save $5 Million for Retirement?
The dollar amounts make the stakes concrete. A worker entitled to $2,000 a month at 67 collects only $1,400 by filing at 62, and $2,480 by waiting until 70. That larger payment continues for life, and across a 25- or 30-year retirement the cumulative difference can run into the hundreds of thousands of dollars. In a June 2026 post, Orman described the early check as “the smallest check you will ever cash, locked in for life.”
Why Waiting Often Makes Sense
Americans are living longer, and a check that feels adequate at 62 can become a genuine financial strain two or three decades later. Delaying Social Security locks in a higher base income, strengthens the buffer against outliving your savings, and compounds more powerfully through annual cost-of-living adjustments (COLAs). The 2026 COLA came in at 2.8%, and every percentage point of that raise applies to a larger base the longer you wait to claim.
The confirmed 2027 COLA adds fresh weight to that logic. The Social Security Administration announced on October 14, 2026 that benefits will rise 3.6% in January 2027, the largest adjustment since the 8.7% jump in 2023 and a full percentage point above the 2026 figure. For the average retired worker, that translates to roughly $75 more per month. Every dollar of base benefit built through delayed claiming benefits from that raise, which is why a larger starting check compounds meaningfully over a long retirement.
The core math still favors patience for people with longevity on their side. Delaying from 67 to 70 increases monthly benefits by 24%, with the break-even point typically arriving in the late seventies to early eighties. For the worker entitled to $2,000 per month at FRA, the move to 70 produces $2,480 instead, an extra $5,760 per year for life.
Orman has also emphasized the stakes for married couples. Her position is that the highest earner should always wait until 70, because the surviving spouse inherits whichever benefit is larger. Maximizing that number is one of the most durable financial protections a couple can build.
If you’ve done the math and still want to retire at 62, the next step is a serious conversation with a financial advisor. Before pulling the trigger, make sure you:
- Have little to no high-interest debt
- Have sufficient retirement savings to last 30 or more years
- Can cover healthcare costs until Medicare begins at 65
- Have factored in inflation and taxes
- Have budgeted for lifestyle expenses like travel or hobbies
Consider This: Dave Ramsey: “You Make $140K. Stay Out of Restaurants, Don’t Go on Vacation, And Get Rid of the Ferrari Bike”
Most people underestimate how much retirement actually costs and overestimate how well-prepared they already are. A realistic retirement budget has to account for vacations, home maintenance, family support, and the unpredictable emergency expenses that arrive without warning. Getting those numbers right before filing prevents real financial stress later.
The core of Orman’s argument is straightforward: retiring at 62 is not impossible, but claiming Social Security at that age imposes a permanent cost that compounds over decades.
One More Thing: Here’s What Bill Gates Can Collect from Social Security
You’ll Also Want a Plan B in Place
The long-term finances of Social Security make a strong case for building personal retirement wealth alongside whatever you expect to collect from the government. The 2026 Social Security Trustees Report, released on June 9, 2026, projects that the Old-Age and Survivors Insurance (OASI) Trust Fund will be depleted in the fourth quarter of 2032, one quarter earlier than the prior estimate. Three forces drove that shift: lower fertility rate assumptions, reduced immigration projections, and the 2025 “One Big Beautiful Bill Act,” which expanded income tax deductions for seniors and reduced the tax revenues flowing back into the trust fund. Demographic changes were the largest contributors, but the OBBBA’s effect was significant enough to register clearly in the trustees’ projections.
If depletion arrives on schedule without congressional action, the program will be able to pay only 78% of scheduled benefits, an automatic 22% cut for every recipient. According to the SSA’s September 2026 Monthly Statistical Snapshot, the average retirement benefit stands at approximately $2,035 a month. A depletion-era reduction at that level would translate to roughly $448 less per month for the typical retiree, and a married couple made up of two average beneficiaries could see their combined annual income fall by more than $10,700.
Orman has pushed back on the popular argument that claiming at 62 is a smart hedge against future trust fund cuts. Her position: even in a worst case where Congress does nothing, benefits would drop to roughly 78% of scheduled amounts. Filing early simply means absorbing that reduction from a smaller starting point, making the early-claim strategy counterproductive as a hedge.
None of this means Social Security will vanish. The program has never missed a payment, and Congress carries a strong political incentive to act well before any deadline. Social Security navigated a similar funding crisis in the early 1980s without forcing beneficiaries to absorb the full cost, and a bipartisan solvency commission modeled on that 1983 panel has already been proposed in the current Congress. The uncertainty is real enough, though, to justify treating Social Security as one piece of a larger retirement plan rather than its entire foundation. Building personal savings, diversifying income sources, and keeping expenses flexible all become more important the closer the 2032 window gets.
Editor’s note: This pass updated the 2027 COLA from pre-announcement estimates to the confirmed 3.6% figure announced by the SSA on October 14, 2026, and refreshed the average retirement benefit figure to approximately $2,035 per month based on the SSA’s September 2026 Monthly Statistical Snapshot.
Contact [email protected] for any questions or corrections.
Ian Cooper is a veteran market analyst and investment strategist with more than 20 years of experience covering stocks, commodities, and macro trends. Since 1999, he has helped investors identify market opportunities using a blend of technical analysis, fundamental research, and market sentiment.
He is the creator of the ADD News Flow Strategy, which focuses on trading market reactions to major news events and investor psychology. Cooper was also among the analysts who warned about the 2008 financial crisis and major financial institution collapses ahead of the broader market.
Before joining 247 Wall St., Cooper wrote extensively for InvestorPlace and other financial publications, covering market trends, trading strategies, and investment opportunities.