Joe Kennedy Put the Family Money Into Trusts in 1926, Before Any of His Kids Could Vote. A Century and Five Generations Later, the Kennedys Still Live on Them, and the Trust He Used Is the One Any Estate Lawyer Drafts Today
Joseph Kennedy funded irrevocable trusts for his children before any of them could vote, and five generations of heirs still live on them today. The instrument he used is the same one any estate attorney drafts for ordinary families, but…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
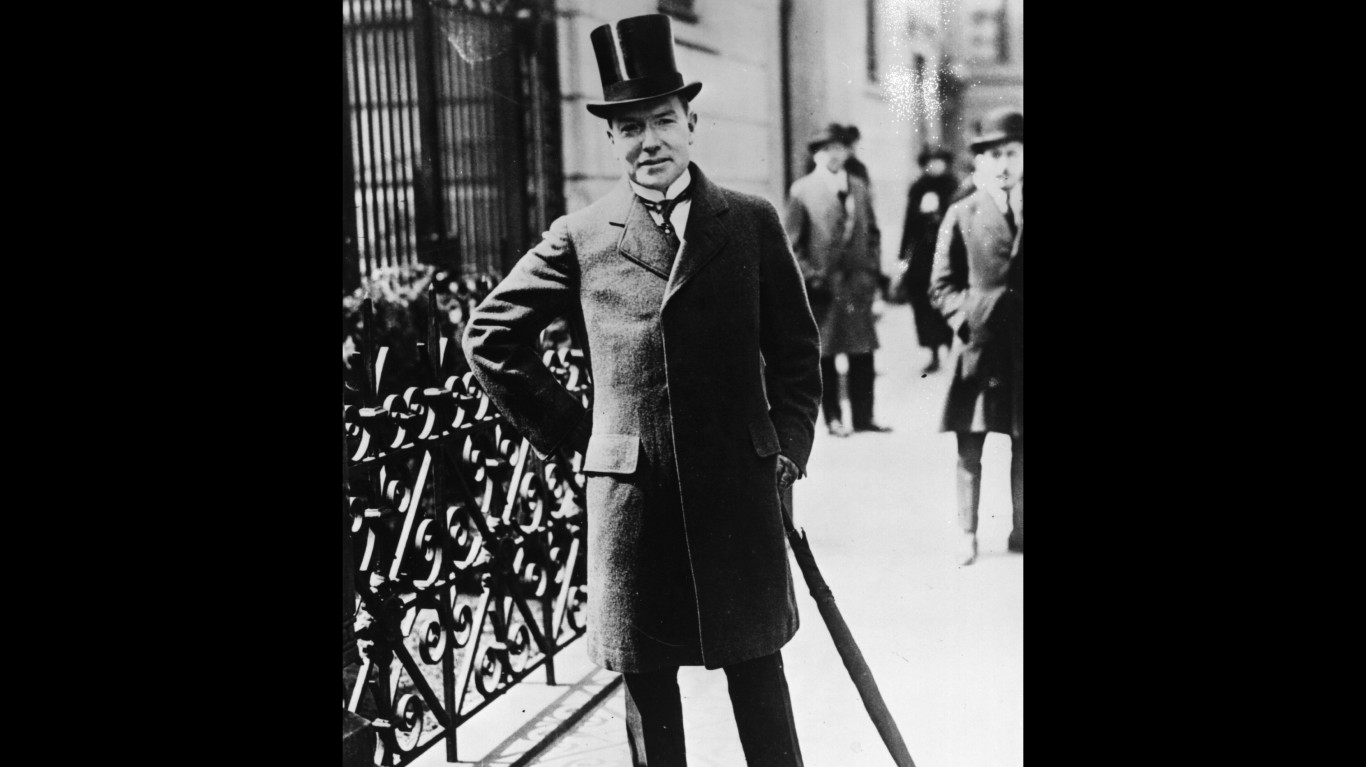
If you have kids and a house, you already own the same estate planning instrument the Kennedys used to move fortunes across five generations. It is an irrevocable trust, and according to the family’s own biographers and public estate records, Joseph P. Kennedy Sr. began funding family trusts for his children around 1926, with additional structures reportedly added in 1936 and 1949. Those dates are as commonly repeated as they are hard to independently document, so treat them as the traditional account rather than gospel. What is not in dispute is the vehicle. It was, and still is, a garden-variety irrevocable trust, the same document your local estate attorney drafts every week.
Why Giving It Away Is the Whole Point
The word that does the work here is irrevocable. When the grantor signs, ownership and control of the assets are gone. You cannot amend the trust to claw them back. You cannot fire the trustee because you disagree with a distribution. In exchange for that surrender, the assets leave your taxable estate and are generally out of reach of future creditors. It is a trade, not a loophole. Families who want the tax and creditor benefits without actually letting go are the same families who watch the IRS or a divorce court unwind the structure years later.
Four Features That Made It Last a Century
Kennedy’s trusts survived scandals, divorces, lawsuits, and political enemies for a specific reason: they combined four ordinary drafting features that are still standard today.
The first is the spendthrift provision beneficiary cannot pledge, sell, or assign their interest, and most creditors, including a divorcing spouse, cannot force distributions. That is why one heir’s bankruptcy does not drain the family pool. The second is the split between income and principal. A beneficiary can be supported for life from what the trust earns, while the corpus, the actual pile of assets, is never handed over. You keep the goose and pass out the eggs.
The third is trustee discretion, which applies when distributions are discretionary rather than mandatory, and a creditor generally cannot compel payment because the beneficiary does not have a fixed right to any specific dollar. Mandatory distributions gut this protection. The fourth is successive interests. Assets pass from one generation to the next under the trust’s terms, not through any beneficiary’s will, so they never enter a child’s or grandchild’s taxable estate.
What Changed After Kennedy: The GST Tax
Kennedy’s original arrangements predated the modern generation-skipping transfer tax. Congress enacted the GST regime specifically to stop the multi-generation skip his trusts pulled off. Today, transfers that skip a generation are taxed at the top estate rate unless covered by the GST exemption under IRC §2631, which by statute equals the basic estate and gift tax exclusion amount. For 2026, that exclusion is $15,000,000 per person, up from $13,990,000 in 2025, and the One Big Beautiful Bill made the higher amount permanent rather than letting it sunset. The annual gift exclusion for 2026 is $19,000 per recipient. Those exemptions are what make a version of the Kennedy structure available to ordinary families now.
Scaling It Down to a Normal Family
At ordinary wealth levels, an irrevocable trust does three real things. It shields assets from a beneficiary’s creditors and divorce. It lets you control the timing and conditions of distributions rather than dropping a lump sum on a 21-year-old. And, subject to Medicaid lookback rules that vary by state and must be verified with counsel, it can figure into long-term care planning.
The costs are also real. Expect legal fees to draft and ongoing trustee administration. Trust income taxation is heavily compressed, reaching the top 37% federal bracket at just a few thousand dollars of retained income, so undistributed income gets punished fast [VERIFY 2026 §1(e) trust bracket threshold]. Assets moved into an irrevocable trust generally lose the step-up in cost basis at death, which can create a bigger capital gains bill than the estate tax you avoided. And the decision is permanent.
One Sentence Most Articles Skip
If your net worth is below the $15,000,000 federal exemption, an irrevocable trust is solving a tax problem you do not have, and it usually costs you the step-up in basis to do it. For an ordinary family, the better reasons are creditor protection, distribution control, and care planning rather than estate tax avoidance. Most estate messes trace back to a missed beneficiary form or an untitled account, not to the absence of a Kennedy-grade trust, and we put the full cleanup checklist in a free estate guide here. Before you call an estate planning attorney- and you do need one for this- answer the one question that decides everything: what problem are you actually trying to solve?
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.