Plenty of Retirees Tour The Villages and Never Buy. One Reason Comes Up Every Time

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
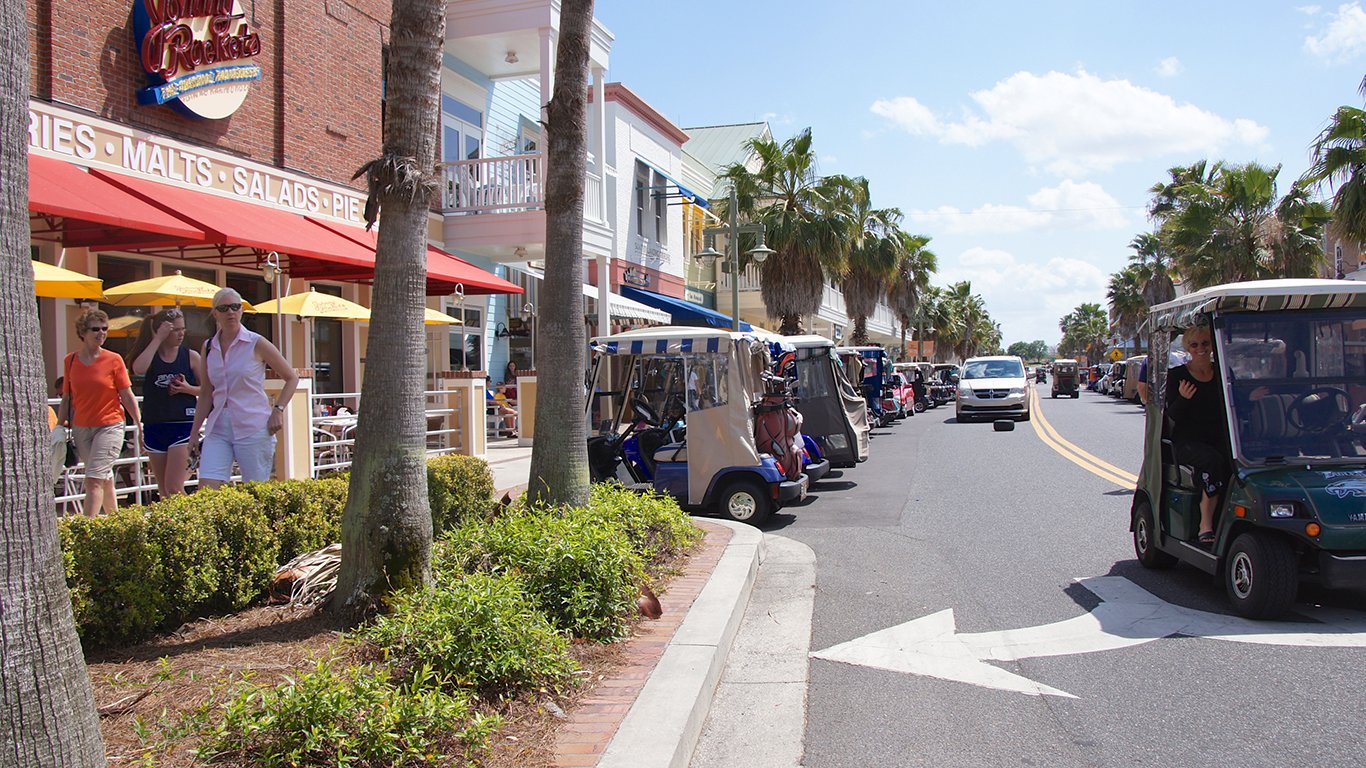
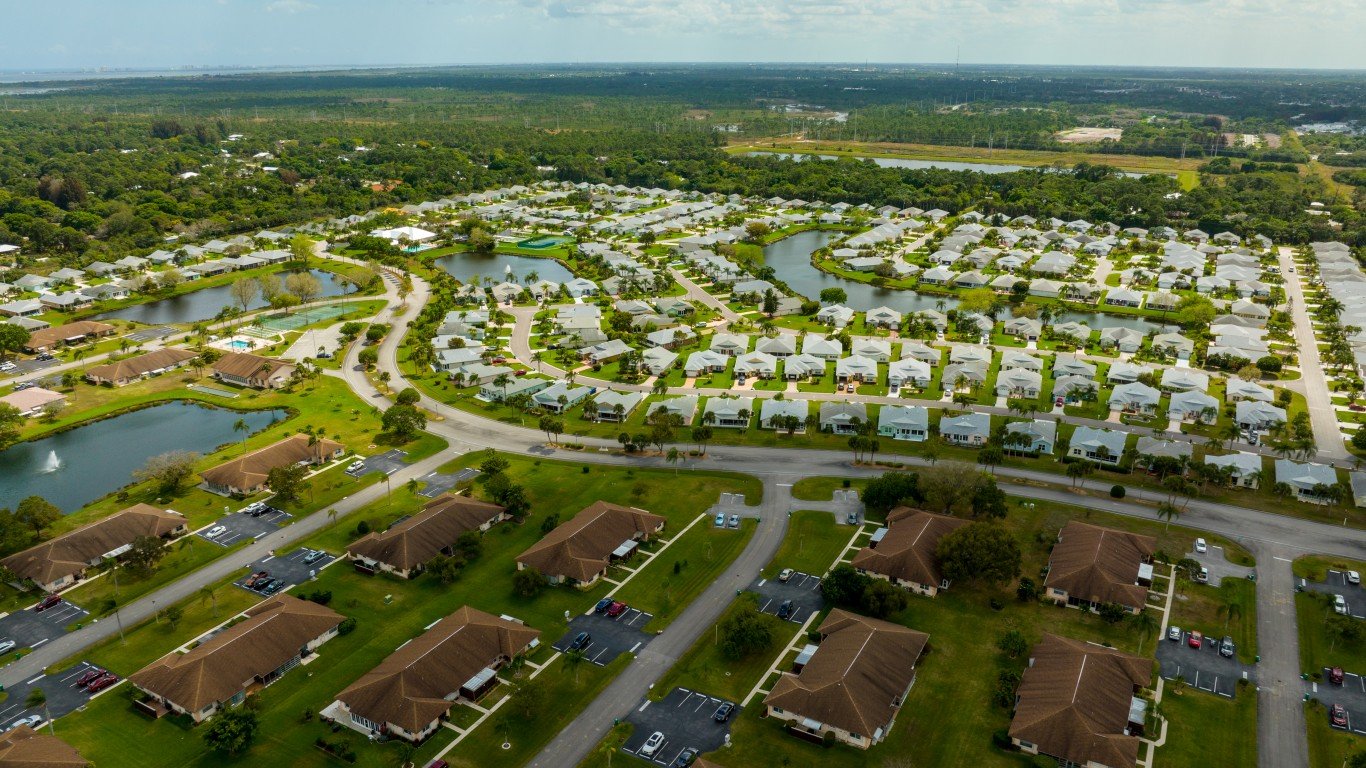
Thousands of couples in their late fifties and sixties visit The Villages each week for a lifestyle preview. Many return home and decide not to buy, and when pressed on why, the answer is consistent: the money. Specifically, it is the layered carrying-cost structure that the sales presentation glosses over and the brochure never totals into a single number.
The community delivers genuine amenities that are hard to replicate elsewhere. It also runs on a fee architecture unlike almost any other retirement destination, and that architecture is what sends visitors home without a contract.
One Reason That Keeps Surfacing: The Stacked Carrying Costs
The Villages operates through Community Development Districts, not a traditional homeowners association. A new-home buyer assumes three distinct recurring obligations: the bond (the buyer’s share of infrastructure financing, paid annually on the tax bill over roughly thirty years or as a lump sum), the annual CDD maintenance assessment (funding street, pond, and common-area upkeep), and the monthly amenity fee (covering golf, pools, pickleball, town squares, and recreation centers).
Each obligation carries its own escalator. The amenity fee for new buyers reached $204 per month in 2026, crossing the $200 threshold for the first time and rising from $199 in 2025. It is contractually tied to the CPI and steps up with inflation for the life of ownership. The CDD maintenance assessment, running roughly $400 to $800 per year, is set annually by the district board and moves with actual maintenance costs. The bond carries interest for its full term if not paid off. Newer homes in areas such as Eastport can carry original balances of $25,000 to over $50,000, with annual bond assessments commonly ranging from $800 to over $4,000 depending on home age and location.
The cumulative effect is what deters buyers, more than any single line item in isolation. A retiree on fixed income can model mortgage, property tax, and insurance, then be caught off-guard by a fourth and fifth recurring line, each with its own inflation mechanic. Projected across a twenty-five or thirty-year retirement, the total obligation is materially larger than the house price itself. The 2027 Social Security COLA was officially set at 3.6% by the Social Security Administration on October 14, 2026, the largest increase in four years. If income rises at that pace while the amenity fee adjusts by a similar margin, the fee never gets cheaper in real terms while healthcare costs continue to accelerate faster still.
What The Sales Tour Does Not Total For You
The preview focuses on lifestyle, not ledger. Visitors leave able to describe the squares and golf cart paths but unable to state in a single number what the home will cost to hold each month once bond payment, CDD assessment, amenity fee, property tax, insurance, and utilities are combined. That gap is where walk-away decisions get made.
The broader housing market compounds the challenge for anyone counting on home equity to fund a move. Existing home sales ran at a 3.99 million annualized pace in September 2026, according to the National Association of Realtors, with both August and September coming in below the 4 million threshold. The national median existing-home price was $417,500 in September, up just 1.3% from a year earlier. The S&P Cotality Case-Shiller National Home Price Index posted a 1.5% annual gain for June 2026, but Sunbelt markets showed notable softening with several metros recording year-over-year price declines. A retiree whose relocation depends on unlocking equity from a slower resale market is simultaneously buying into a fixed-cost stack in Florida, and those two uncertainties compound each other. The University of Michigan Consumer Sentiment Index remained well below its long-run historical average through mid-2026, reflecting the cautious environment in which these decisions are being made.
What The Community Genuinely Delivers
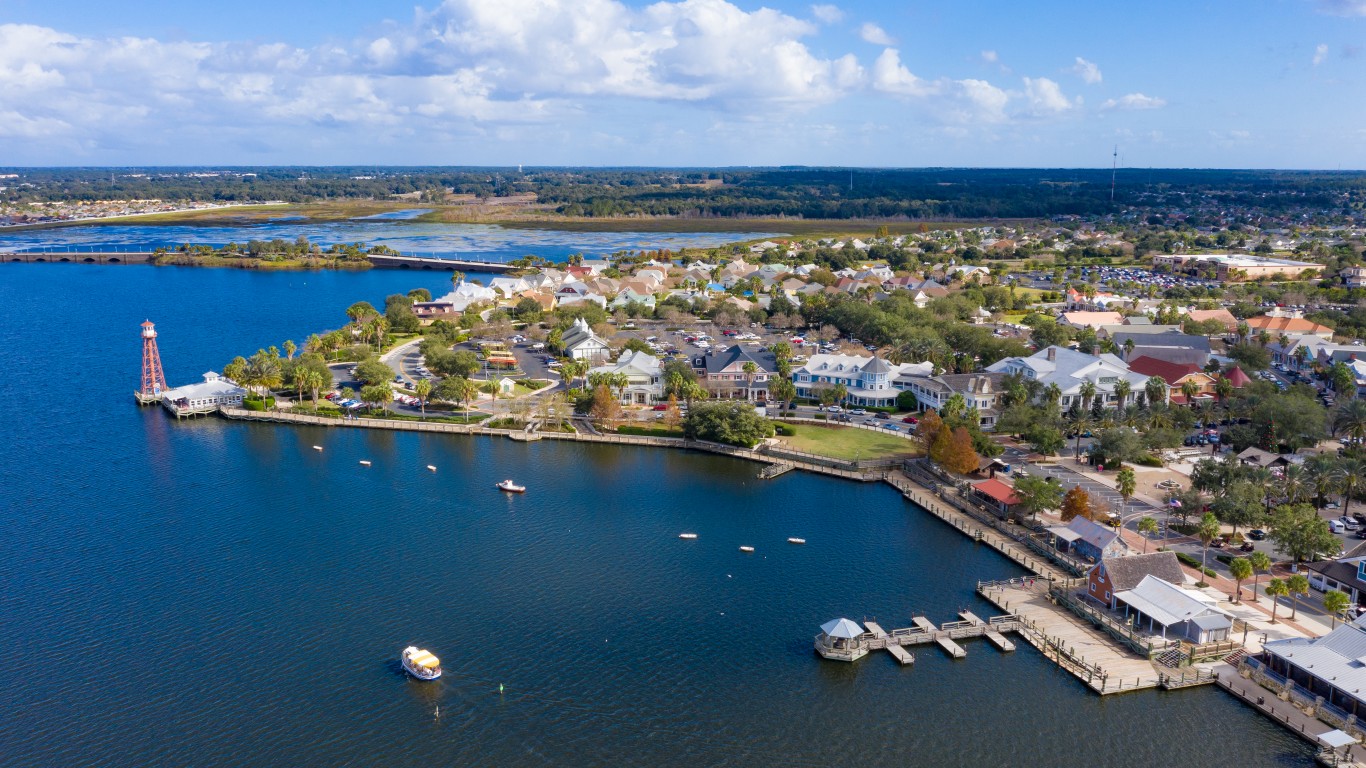
Buyers are pricing something walk-aways consistently undervalue. Building a social life from scratch in your late sixties is genuinely hard, and The Villages has solved it at scale across a community with a median resident age of 74.1 years. The club infrastructure, nightly town square entertainment, and the continuity of community after a spouse’s death all carry real, lasting value. The golf-cart-first street grid extends the years a household can stay independent, which in turn delays the costs of healthcare facilities.
For a buyer who uses amenities most days, the monthly fee is reasonable relative to private-club access. The objection is structural: fees are fixed regardless of use, so a household that plays golf twice a month and rarely visits the pool ends up paying resort pricing for what becomes suburban use.
Documents To Request Before You Book
The most useful step is to request in writing the specific bond balance and amortization schedule for the exact home, the current annual CDD maintenance assessment for that district, and the current monthly amenity fee with its escalation clause. Add property tax and homeowners insurance for that address. Total those into one annual carrying number, hold it against Social Security and portfolio income, and decide before the flight whether the math clears with room for healthcare inflation and aging infrastructure reserves.
Walk-aways consistently say they wish they had run these numbers at the kitchen table first. The answer is knowable before you board the plane. The Preview sells the lifestyle. The carrying-cost stack determines whether that lifestyle remains affordable across a twenty-five-year retirement, and once totaled, it tends to make the decision for you.
Editor’s note: This pass corrects the 2027 Social Security COLA from “approximately 3.5%” to 3.6%, reflecting the official SSA announcement on October 14, 2026. Housing market data has been updated to September 2026 figures from the National Association of Realtors, showing a 3.99 million annualized sales pace and a national median existing-home price of $417,500, up 1.3% year over year.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.