Nobody Wants to Inherit a Villages Home. Here’s What It Costs the Kids When They Do
Leaving a Villages home to your kids sounds like a gift, but the legal restrictions, tax resets, and monthly carrying costs can turn an inheritance into a financial burden they never asked for.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
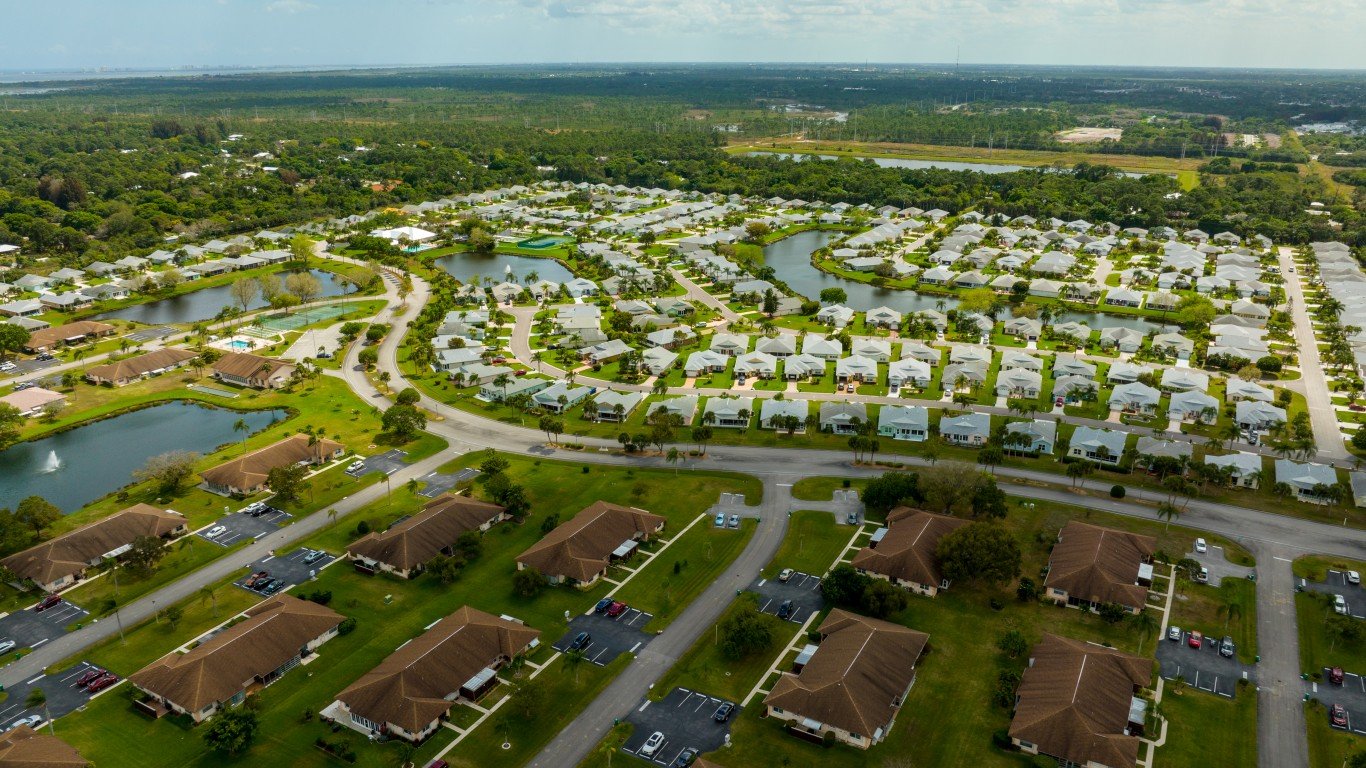
Most conversations about a home in The Villages end at the closing table, when the retiree buys in and starts pricing golf carts. The lifestyle is genuinely appealing, and for a lot of buyers that is the whole story. The question that rarely gets asked out loud is what happens after you are gone, and the house passes to your kids in Denver, Boston, or Seattle, none of whom can use it. Current and future owners need to look at this with clear eyes: what your children will actually face, and what you can still do about it while you have time.
Why Your Adult Kids Cannot Just Move In
The Villages qualifies as age-restricted housing under the federal Housing for Older Persons Act. At least one occupant of each home must be 55 or older, at least 80% of homes must house someone 55-plus, and no one under 19 may live there permanently. If your adult child is under 55, they legally cannot occupy the house they just inherited. Their choices collapse to two: sell it, or rent it under the community’s rules. Rentals require a minimum 30-day lease, tenants must meet the age requirement, and the district requires rental registration. The asset they received is one they are structurally barred from using as a home.
The Property Tax Reset Nobody Budgets For
Here is the biggest hidden number. Under Florida’s Save Our Homes provision, a homesteaded owner’s assessed value can rise no more than 3% per year, or the rate of inflation, whichever is lower. Over fifteen or twenty years, the assessed value drifts far below market. When the owner dies and the home transfers to a non-spouse heir, the homestead exemption ends and the Save Our Homes cap is stripped. The property assessor resets to full market value on the next tax roll. Your children are budgeting from your last tax bill. Theirs can easily be two or three times that figure, on a house nobody is living in.
Every Month the House Sits Empty, the Meter Runs
Property taxes at the new uncapped assessment continue accruing from day one. So does the amenity fee, which runs roughly $189 to $195 per month in 2026, is contractually tied to the deed, and adjusts with inflation. So does the bond assessment attached to the lot, the infrastructure debt that funded the district. Unpaid bond balances in newer sections often exceed $20,000 in principal, and the annual payment runs a few thousand dollars until retired.
Homeowner’s insurance is a separate problem. Standard HO-3 policies exclude most losses once a home has been vacant 30 or 60 days, so heirs must buy a vacant-dwelling policy that typically costs materially more. Florida’s homeowners insurance market already runs roughly three times the national average on a per-policy basis, so the vacant-dwelling premium on top of that is a real shock to families who inherit from out of state. Utilities stay on for showings. Lawn service, pressure washing, and pest control continue because the deed restrictions require them. Kids in Seattle pay someone to coordinate all of it from 2,800 miles away.
A Narrow Buyer Pool in a Soft Resale Market
Every buyer must meet the age rule, and most first tour the developer’s new construction before looking at resale. A dated home in an older village competes with a model home the buyer walked through that morning. The Villages median resale price stood at roughly $360,000 in early 2026, down about 1.7% year over year, one of Florida’s more resilient retirement-market performances but still a sign that pricing power has limits.
National conditions do not help. The S&P Cotality Case-Shiller National Home Price Index reached 337.3 in July 2026, up just under 2% from a year earlier, reflecting a market where price gains have cooled sharply from the pandemic-era pace. Existing home sales came in at a 3.99 million annualized rate in September 2026, the second consecutive month below the 4 million mark and 2.2% below the prior year’s pace. Florida’s statewide cost of living runs modestly above the national baseline, keeping carrying costs elevated while a listing waits.
A Piece of Good News for Heirs
Federal law gives inherited property a basis adjustment to fair market value at the date of death under IRC Section 1014. Heirs who sell promptly usually owe little or no capital gains tax, even on a home their parent bought decades earlier. That is genuinely valuable and offsets a real slice of the pain above.
Complications That Make It Worse
Florida formal probate typically runs six to twelve months, and heirs cannot close a sale until letters of administration issue. The estate pays carrying costs throughout, or the kids do. If the parent received Medicaid long-term care benefits, a Medicaid estate recovery claim can attach to the home in probate. If three siblings inherit jointly and one wants to hold and rent while two want to sell, that standoff alone can cost a year of carrying charges before anyone files a partition action.
A Conversation to Have This Year
Ask your children plainly whether any of them wants the house. If the answer is no, price the sale-now option against the leave-it option, weighing the lost stepped-up basis against a year of empty-house costs your estate will absorb. Make sure the estate holds enough liquid cash to fund roughly a year of taxes, amenity fees, insurance, and maintenance. Name a local person, whether an attorney, a realtor, or even a trusted neighbor, who can act the week after you die. The full checklist of beneficiary forms, titling, and trust language that keeps a house like this out of a family fight lives in our free estate guide, here. The house becomes the inheritance you think it is only if you set it up that way.
Editor’s note: This article updates the Case-Shiller National Home Price Index figure to 337.3 (July 2026, per FRED), refreshes the existing home sales pace to 3.99 million annualized (September 2026, NAR), replaces the stale Florida cost-of-living index of 103.414 with the current MERIC composite of approximately 100.7, and adds current Villages amenity fee figures and the March 2026 median resale price of roughly $360,000.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.