What a $5,100 a Month Union Pension Will Actually Buy a Retired Teamster in The Villages After Tax
A $5,100 union pension looks like a comfortable retirement in The Villages until you run it through federal tax, Florida's rising amenity fees, and the one survivor election that could cut the household income in half overnight.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
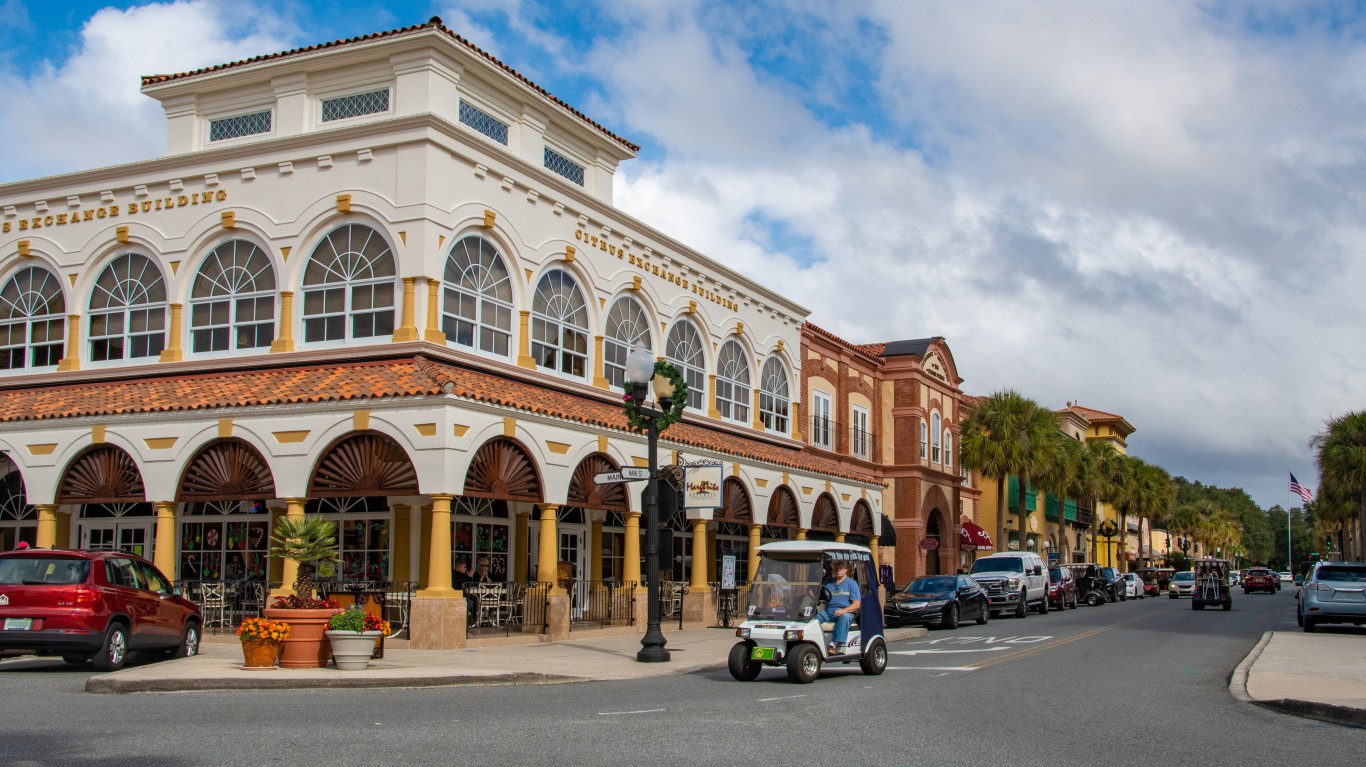
Picture a retired Teamster collecting a $5,100-a-month union pension. Readers keep asking us the same question: can this one check carry a couple through a long retirement in The Villages, Florida’s giant retirement community? Here’s what that check actually buys after tax, what’s left after fixed bills are paid, and the two features of a union pension that will decide whether the plan still holds up 20 years from now.
Why a Union Pension Behaves Differently Than a Corporate Check
A multiemployer plan is a pension a union negotiates with a group of employers, usually in one industry. Collective bargaining contracts set employer contributions, and union and employer-chosen trustees run the plan. Spreading the plan across many employers spreads the risk. The catch is that when trucking companies close or pull out, fewer active workers end up supporting more retirees.
If a plan runs out of money, benefits fall to whatever the Pension Benefit Guaranty Corporation (PBGC), the federal pension insurance company, guarantees. For multiemployer plans, the guarantee is figured per year of service. The maximum guaranteed accrual is $35.75 per year of service. For a 30-year Teamster, that works out to $1,072.50 a month. That’s a small fraction of a $5,100 check, and everything above it is uninsured.
Washington did close that gap for some retirees. The American Rescue Plan Act of 2021 created Special Financial Assistance to keep troubled plans solvent until 2051. Plans that took the money had to retroactively reinstate suspended benefits, and applications were open only through December 31, 2025. If your plan didn’t get that money, its own funding is the only thing behind the check. On top of that, this pension is a fixed amount with no automatic COLA, so its buying power shrinks every year.
What $5,100 Becomes After Federal Tax
Because Florida has no state individual income tax, the only income tax on the pension is federal, where it counts as ordinary income. The estimate assumes a married couple, both 65 or older, filing jointly, with no other taxable income. The 2026 standard deduction for a married couple filing jointly is $32,200. The new senior deduction adds $6,000 per person, up to $150,000 of modified adjusted gross income.
To keep the estimate conservative, it excludes the separate standard deduction for people 65 and older. Everything that’s left to tax falls in the 10% bracket, which runs up to $24,800 for joint filers. Federal tax comes to about $1,700 a year, which leaves roughly $4,958 a month to spend.
Adding Social Security to the pension changes the tax math. To decide how much of your benefit is taxable, the IRS takes half your benefits, adds all your other income, and compares the total to a base amount. Those base amounts have never been indexed to inflation. Stacked on a pension this size, a share of a couple’s benefits is likely to be taxed.
Fixed Costs in The Villages Before Anyone Tees Off
Homes in ZIP code 32162 sold for a median of $344K over the three months ending in August. On top of the purchase price, the amenity fee is $204 a month today and will rise to $211.77. Sumter County homeowners pay an average of $1,826 a year for insurance, and Medicare Part B costs $202.90 a month per spouse.
Those items add up to about $762 a month, which leaves roughly $4,196. That money still has to cover property taxes, the Community Development District assessment, any infrastructure bond attached to the house, summer air conditioning, Medigap and Part D, food, a car, a golf cart, and championship golf, which is paid per round. Florida’s homestead protection caps assessed value increases at 3% a year. A buyer’s assessment resets at purchase, though, so the seller’s low tax bill doesn’t carry over to you.
If they own the house outright, the pension covers the fixed costs listed above with room left over. Adding a mortgage on a $344K house leaves much less room in the monthly budget. Social Security on top is what turns a workable budget into a comfortable one.
Two Risks That Decide Year 20
Assuming 3% inflation a year for 20 years, today’s $4,958 will buy about what $2,745 buys now. Meanwhile, the amenity fee rises each year under a contractual CPI-linked formula. Social Security’s 2027 COLA is tracking toward 3.3%. The pension gets no increase.
The second risk is the survivor election. With a 50% joint-and-survivor option, a widowed spouse would keep $2,550 a month. That payment counts as gross income and is taxed under a single filer’s standard deduction of $16,100, while fixed housing costs stay the same. A single-life election pays the biggest check, and it ends completely when the retiree dies. The Social Security survivor benefit sits alongside this decision and follows its own timeline, and we worked through how to sequence the two in a free guide here. A single-life election pays the biggest check, and it ends completely when the retiree dies.
What Makes This Retirement Work
The budget holds up best with a house bought for cash, fixed costs held near $800 a month plus property taxes and assessments, Social Security claimed alongside the pension, and a survivor election of at least 50%. A separate inflation reserve would also help make up the buying power the pension loses each year. Two documents are useful to review before a purchase. The first is the plan’s annual funding notice, which shows how well funded it is and whether it received federal assistance. The second is the fee and assessment history for the specific property, including the amenity fee schedule, the district assessment and the bond payoff balance.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.