Green Bay Winters Are Long, and Its Retirees Know It. What a Retirement There Costs, Season by Season
Heating bills, a stubborn property tax rate, and a Medicare deadline that lands mid-football season all hit Green Bay retirees at different times. One tax timing trick at age 67 could change how much of your nest egg the state…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
For anyone considering the yearly cost of retiring in Green Bay, Wisconsin, here’s a season-by-season look at what you can expect. People who grew up here and those who just love the Packers often ask the same thing: can a normal retirement work in a city with long winters and a property tax bill that never gets lower? The good news is it can. You just have to plan for each season’s bills, so here’s the year in order.
Winter Heat and Snow Removal Set the Tone
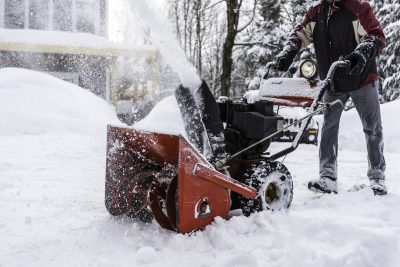
Heating is the bill that swings the most. Last winter, Wisconsin Public Service forecast that a typical residential bill would run about $13 a month higher. That’s $13 more per month during the heating season, driven by colder weather, infrastructure upgrades, and higher natural gas prices. One local reporter found his own bill up more than $40 from the year before. Snow removal adds to it. In Green Bay, a single job typically runs $50 to $415, depending on the driveway, and contractors also sell flat-rate seasonal deals. If shoveling your own driveway is something you’ll age out of, put a seasonal contract in the budget now.
Spring Brings the Property Tax Reckoning
Home prices in Green Bay are relatively affordable. Zillow Group (NASDAQ:Z | Z Price Prediction) puts the typical Green Bay value at $285,670. Property taxes are the higher cost. Green Bay’s median effective rate is 1.50%. That’s above the state’s 1.43% and the national 1.02%. On a typical home, that’s roughly $4,285 a year. Which part of town you buy in matters too, with rates ranging from 1.30% in 54313 to 1.60% in 54229. Wisconsin’s homestead credit won’t help most retirees with savings because household income must be under $24,680. That cap has barely budged since 2000.
Summer on the Bay, and a Tax Break Worth Planning Around
Summer is a practical time to sort out your taxes. Wisconsin fully exempts Social Security. It taxes pensions and IRA withdrawals as ordinary income at 3.5% to 7.65%. Under the 2025 Wisconsin Act 15, residents 67 or older can subtract up to $24,000 for single filers or $ 48,000 for married filers (both 67+) of retirement income, with no income limit. Overall prices help, too. The state’s cost-of-living index is 94.095, with 100 marking the U.S. average. Homeowners insurance in Green Bay typically runs $1,650 a year.
Fall Football Season Is Medicare Season
Your Medicare choices come due in the fall, right in the middle of football season. Part B costs $202.90 a month in 2026, and the income surcharge doesn’t start until joint income tops $218,000. Here are the bills you can’t skip:
| Line item | Single | Couple |
|---|---|---|
| Property tax | $4,285 | $4,285 |
| Homeowners insurance | $1,650 | $1,650 |
| Medicare Part B | $2,435 | $4,870 |
| Fixed floor | $8,370 | $10,805 |
A single retiree pays the same housing costs as a couple. Only Medicare gets cut in half.
The average US household spends $81,095, according to the BLS. Adjusting that figure to Wisconsin gives roughly $77,000, but that’s a broad estimate rather than a retirement-specific budget. Take out the fixed floor, and you’re left with roughly $66,000 for food, heat, electricity, cars, supplemental insurance, Packers tickets, and reserves.
What the Portfolio Has to Cover
A retired couple’s typical Social Security check will be $3,355 a month after the 2027 raise, or $40,260 a year. Using the estimated $77,000 budget, the gap comes to about $36,800. Divided by a 4% withdrawal rate, you need roughly $920,000, although the actual savings target depends on the couple’s spending. At a more conservative 3.5%, it’s about $1.05 million. A single retiree whose Social Security averages $26,040 carries nearly the same house costs on one check. (The 4% figure itself is older than most of the retirees relying on it, and we made the full case for an income-first alternative in a free report.)
Once both spouses reach that age, a $36,800 IRA withdrawal fits under the $48,000 exclusion. With Social Security exempt too, the couple owes little or no Wisconsin income tax. Retire at 63, though, and those same withdrawals get taxed by the state for four years. One approach some retirees research is drawing from a regular brokerage account or a Roth first, then switching to IRA withdrawals at 67. On the federal side, a 2026 federal deduction of $32,200 keeps the bill low.
Retiring in Green Bay involves trade-offs: winters run long, property taxes stay high, and you may need to connect through another hub to get where you’re going. In return, you get affordable houses and summer access to the bay.
Spread the Heating Bill Over Twelve Months
In short, plan on roughly $920,000 at a 4% withdrawal rate. That assumes typical Social Security benefits and holding off on IRA withdrawals until 67. The bill to plan for first is heat. WPS offers Budget Billing, which evens out your energy bills across the year. Sign up and set aside a fixed monthly amount, so January’s cold doesn’t hit you all at once.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.