Can a Couple Retire in Providence, Rhode Island, at 65 on $900,000? Here’s the Math

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
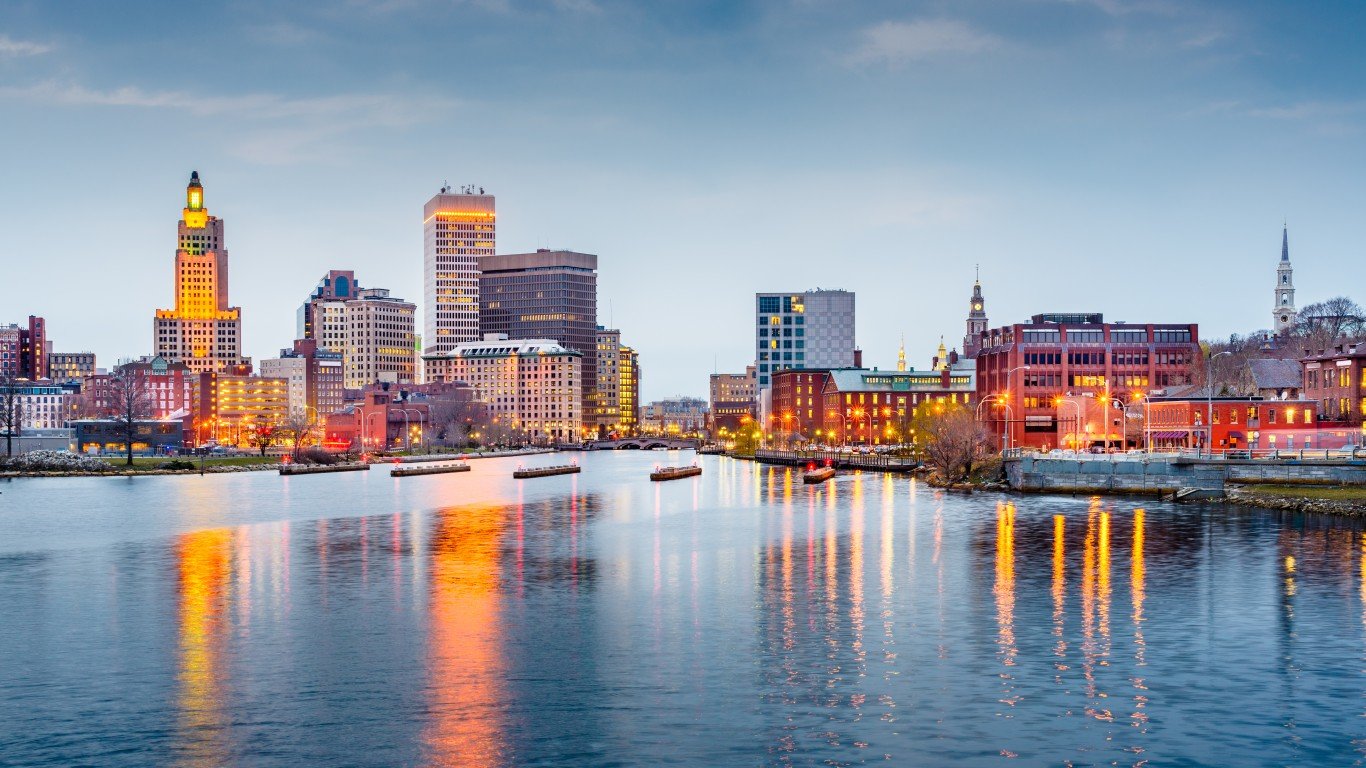
Can a married couple at 65 afford to retire in Providence, Rhode Island? With $900,000 saved, they can, though only with a small buffer, and only if the house is already paid off.
What a Providence Retirement Costs Each Month
Rhode Island costs a bit more than the national average. The BEA’s regional price index puts the state at 102.28, compared with 105.757 for Massachusetts. The biggest change comes from housing. Providence’s median sale price is around $565,000, and FHFA data shows metro prices up 4.7% over the past year and 51.94% over five years.
We assume the couple sold a house elsewhere and paid cash for a median Providence home, so the $900,000 stays untouched. Here’s the monthly budget in today’s dollars; uncited lines are our estimates.
| Expense | Monthly |
|---|---|
| Property tax | $706 |
| Homeowners insurance | $175 |
| Home maintenance reserve | $470 |
| Heating oil | $225 |
| Electricity | $175 |
| Water, internet, phones | $200 |
| Medicare Part B, two people | $406 |
| Medigap and Part D, two people | $600 |
| Dental, vision, copays | $200 |
| Groceries | $900 |
| Dining out and arts | $300 |
| Car costs | $450 |
| Car replacement fund | $250 |
| Travel, gifts, personal | $450 |
| Emergency reserve | $150 |
| Income taxes | $150 |
| Total | $5,807 |
Property tax uses Providence County’s median effective rate of 1.50%. That rate varies widely by town, from 1.20% in Cumberland to 2.08% in Foster. Heating assumes an older house burning about 700 gallons of oil a year at $3.88 a gallon. Part B runs $202.90 a month per person, and this couple’s income sits well below the $218,000 joint threshold where IRMAA surcharges begin. Maintenance is set at 1% of the home’s value each year. Older houses need roofs, boilers, and windows replaced periodically.
Turning Savings and Social Security Into a Paycheck
An average senior couple where both spouses collect Social Security gets $3,355 a month after the 3.6% COLA for 2027, but claiming at 65 reduces benefits by approximately 13.3% compared with claiming at 67, so the couple should use their own estimated benefits.
A 4% withdrawal from $900,000 adds $3,000. That brings in $6,355 against $5,807 in spending, which leaves about $548 a month to spare. Meeting the budget exactly would require drawing down only 3.27%. That rate sits below the 4% withdrawal level used in this plan. Federal tax stays light, too, with a $32,200 standard deduction for joint filers before the extra amounts for age 65.
Two-Year State Tax Gap Most Plans Miss
Rhode Island exempts Social Security only for residents who have reached full retirement age and stay under an income limit. Its pension and annuity break, which has grown to $50,000, or $100,000 for joint filers, uses the same age test. Full retirement age is 67 for anyone born in 1960 or later. That means a couple retiring at 65 gets neither break for two years. During that time, federally taxable benefits and IRA withdrawals are taxed at state rates, starting at 3.75% on income up to $82,050.
One way around it is to hold off on Social Security until 67 and live on the portfolio for those two years, at roughly $69,700 a year. That locks in larger lifetime benefits, and the first check comes already eligible for the exemption. The price is a heavy draw early on, so the plan assumes two years of spending held in a Treasury ladder or CDs before retiring.
What Providence Gives Back, and What It Asks
In exchange, the couple gets a strong restaurant scene, Brown and RISD, major teaching hospitals, Narragansett Bay close by, and Amtrak service to Boston and New York. The costs are long winters, heating bills, older houses, and property taxes that depend heavily on the town. The state’s elderly property tax credit requires household income of $40,730 or less, which puts this couple out of reach. Rhode Island’s estate tax applies above $1,838,056, and both a home owned outright and savings count toward that threshold.
Verdict Rests on One Budget Line
The deciding factor in this plan is housing: if the couple pays for the median house out of the $900,000, the remaining savings support only about $1,117 a month at 4%, and the plan falls short by roughly $1,335 a month. To make Providence work, they need to come in with the house fully paid from other equity, keep withdrawals between 3.3% and 4%, push Social Security to 67 to skip the state tax gap, and hold two years of spending in safe assets.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.