Price Prediction and Forecast: Oracle Trades 29% Below Its Peak. Here Is Our 12 Month Target

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Oracle (NYSE:ORCL | ORCL Price Prediction) has whipsawed investors over the past year, rising from below $160 to a peak above $300 last October before retreating. With the stock consolidating around $186 and a $553 billion AI backlog on the books, the risk/reward has shifted to the long side.

Our 24/7 Wall St. Price Target for Oracle
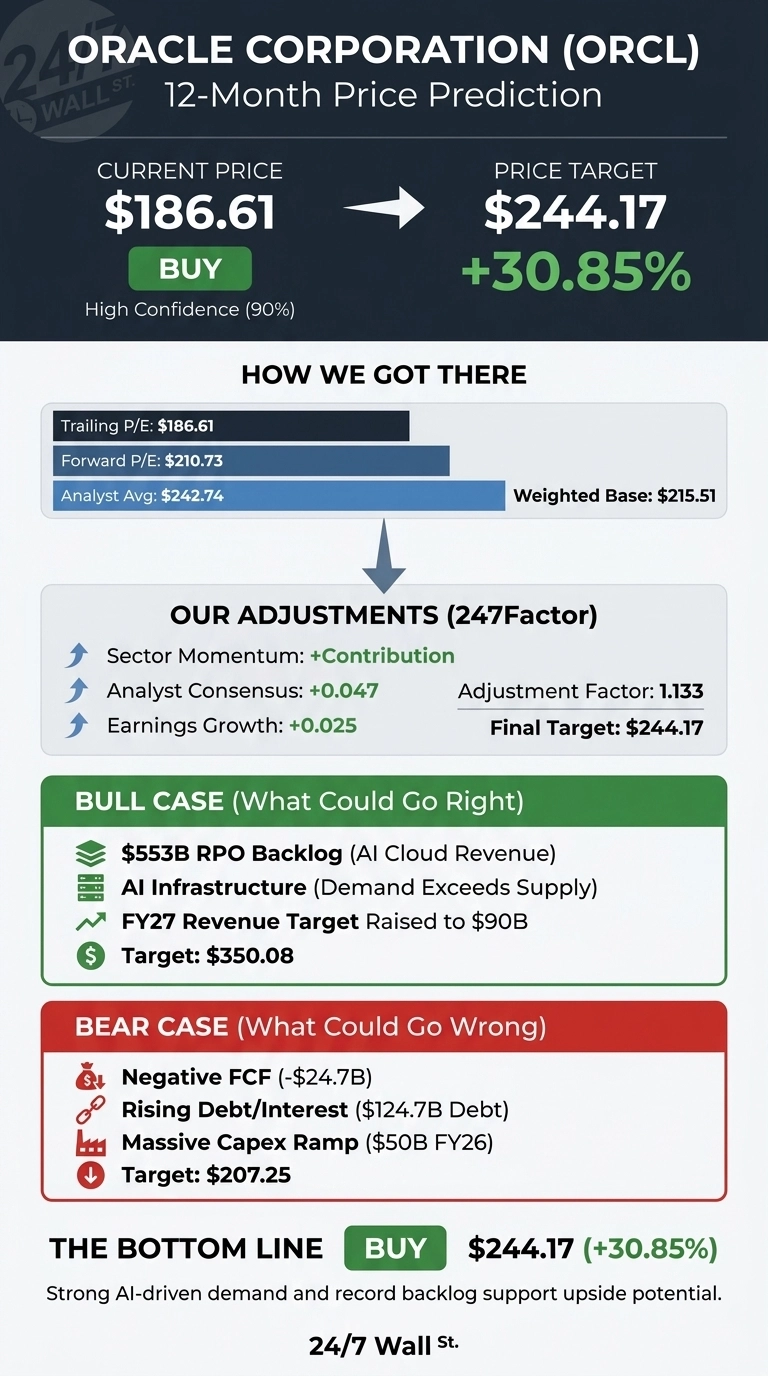
ORCL stock trades at $186.61 as of the May 18, 2026 close. Our 24/7 Wall St. price target is $244.17, implying 30.85% upside over the next twelve months. The recommendation is buy with a 90% confidence score.
| Metric | Value |
|---|---|
| Current Price | $186.61 |
| 24/7 Wall St. Price Target | $244.17 |
| Upside | 30.85% |
| Recommendation | BUY |
| Confidence Level | 90% |
From a $343 Peak to a Mid-Range Reset
Oracle is 29% below its 52-week high of $343.01 and well off the February low of $153.97. Shares are down 3.67% YTD but up 17.44% over the trailing year and up 6.6% over the past month.
The reset came after Q2 FY26 in December, when revenue missed by 5% and shares fell 13% despite a 32.43% EPS beat. Q3 FY26, reported March 10, reset the narrative. Revenue hit $17.19 billion, EPS came in at $1.79, and Cloud Infrastructure grew 84% to $4.89 billion. Remaining performance obligations jumped 325% to $553 billion, and management raised the FY27 revenue target to $90 billion.
The Case for $300+
The bull case starts with the backlog. CFO Safra Catz outlined a path for Oracle Cloud Infrastructure to grow from $18 billion in FY26 to $32 billion, $73 billion, $114 billion, and $144 billion over four years, with “Most of the revenue in this 5-year forecast is already booked in our reported RPO.” Multicloud database revenue is growing 531%, and co-CEO Mike Sicilia noted “All of the top five AI Models are in the Oracle Cloud.”

Wall Street agrees. The analyst tally shows 7 Strong Buy, 28 Buy, 8 Hold, 1 Sell with a consensus target of $242.74. Our internal bull case projects $350.08 within twelve months, an 87.6% return if capacity delivery accelerates and AI demand outpaces supply.
What Could Go Wrong
The bear case centers on capital intensity. Trailing free cash flow is negative $24.74 billion, capex runs at a $50 billion FY26 pace, non-current debt has climbed to $124.7 billion, and interest expense is up 32%. Customer concentration in hyperscale AI buyers is real, and concerns about OpenAI missing revenue and user targets pose a pipeline risk.
The counter is that capex is contracted revenue waiting to happen. Co-CEO Clay Magouyrk told analysts “A combination of bring-your-own-hardware and upfront customer payments enables us to continue expanding without any negative cash flow from Oracle Corporation” on new contracts. Our bear scenario still lands at $207.25, an 11.06% gain from here.
Our Take at Current Levels

The 24/7 Wall St. price target of $244.17 and buy rating reflect 90% confidence on a stock trading at a reasonable 26x forward earnings against a backlog growing triple digits.
The bull thesis holds if Oracle converts even half its $553 billion RPO on schedule. The bear thesis takes over if hyperscale AI capex rolls over in 2027. Insider activity skews toward buying and trailing 30-day sentiment is up 17.67 points, favoring the bulls.
Oracle Price Prediction 2026-2030
Our model projects Oracle could trade as follows, assuming current growth trajectories and the OCI ramp hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $244 |
| 2027 | $285 |
| 2028 | $334 |
| 2029 | $388 |
| 2030 | $403 |
Significant upside or downside could come from faster-than-expected datacenter delivery, GPU supply normalization, or a slowdown in hyperscale AI spending.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.