This Stock Will Dominate The Second Half of 2026

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Alphabet (NASDAQ:GOOGL | GOOGL Price Prediction) has been one of the loudest AI winners of the past 12 months, but a sharp June pullback has reset the setup heading into the second half of 2026.
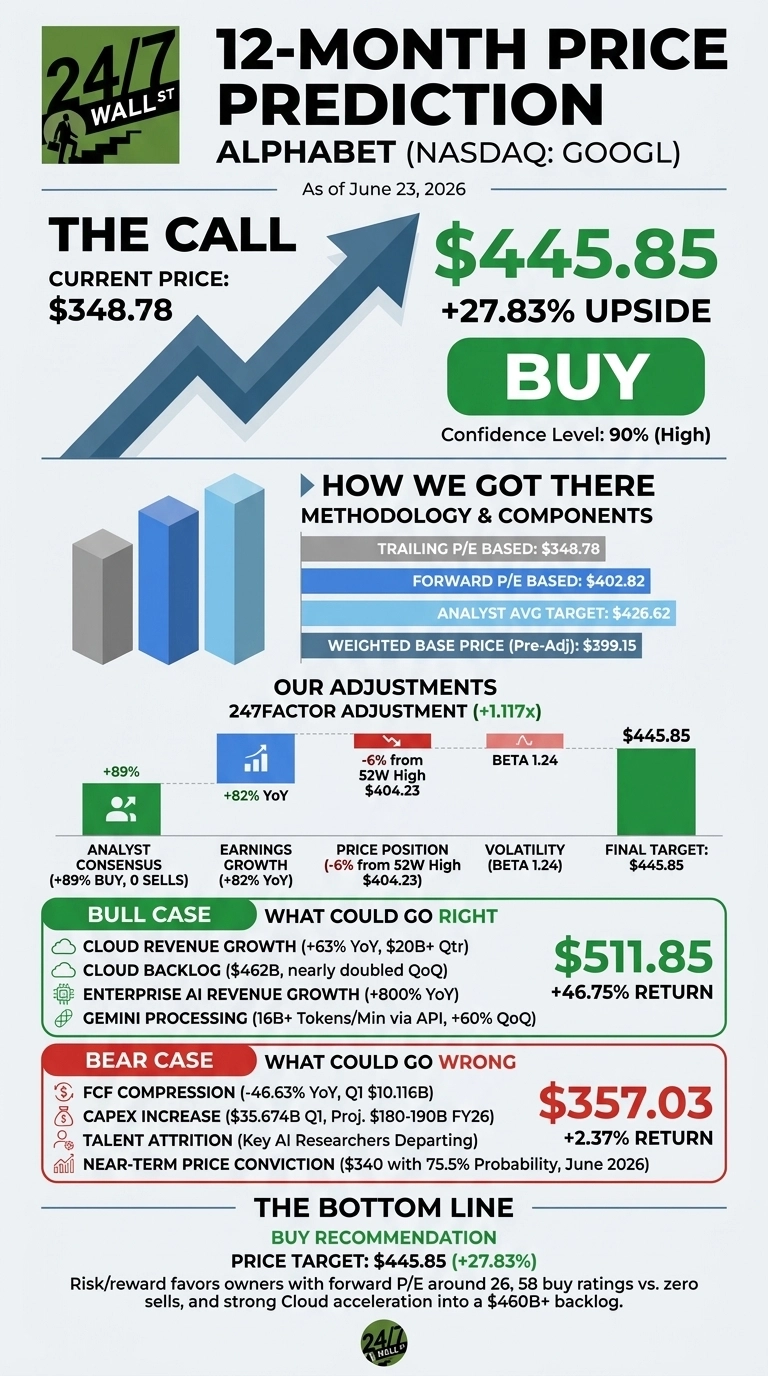
Our 24/7 Wall St. price target for Alphabet is $445.85, implying 27.83% upside from the current $348.78. Confidence is high at 90%, and the recommendation is buy.
| Metric | Value |
|---|---|
| Current Price | $348.78 |
| 24/7 Wall St. Price Target | $445.85 |
| Upside | 27.83% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Pullback Inside a Massive Rally
Alphabet is down 4.99% over the past week and 8.01% over the past month, but the stock is still up 11.29% year to date and 108.54% over the past year.
The recent slide is tied to news that two senior Gemini researchers, including co-lead Noam Shazeer, are leaving for OpenAI and Anthropic, a story that dominated r/stocks over the weekend before retail sentiment rebounded to 62 (bullish) on Monday.
The fundamentals behind the rally are intact. Q1 FY26 delivered EPS of $5.11 against a $2.632 estimate, a 94.1% beat, on revenue of $109.89 billion, up 21.79% YoY. Google Cloud crossed $20 billion in quarterly revenue for the first time, growing 63% with backlog nearly doubling sequentially to $462 billion.
Why Bulls See a Breakout Ahead
The bull case rests on AI monetization compounding faster than expected. Gemini is now processing more than 16 billion tokens per minute via direct API, a 60% sequential jump.
Cloud operating income tripled YoY to $6.6 billion at a 32.9% margin, and enterprise AI revenue grew 800% YoY. Sundar Pichai noted that “our cloud revenue would have been higher if you were able to meet the demand,” a constraint that resolves as 2026 CapEx of $180-190 billion hits the ground.
Search is also expanding monetizable surface area. More than 30% of search advertisers now use AI MAX or Performance Max, and Philipp Schindler argued “there is upside in that coverage number” beyond the historical 20%. If the 247Factor’s bull scenario plays out, the stock reaches $511.85, a 46.75% return.
The Risks Worth Watching
Free cash flow fell 46.63% YoY in Q1 as CapEx more than doubled to $35.674 billion, and management has signaled 2027 spending will “significantly increase”. Bulls would argue this is exactly the kind of build-out that delivered the $462 billion Cloud backlog, but the FCF compression is real.
Add talent attrition at Gemini, ongoing EU competition fines, and Polymarket’s near-term clustering at $340 (75.5% probability) for end-of-June, and the path higher will be choppy. The bear scenario lands at $357.03, essentially flat from here.
Alphabet Price Prediction 2026-2030
The 24/7 Wall St. price target is $445.85, the recommendation is buy, and confidence is 90%. With a forward P/E around 26, 58 buy ratings versus zero sells, and Cloud accelerating into a $460B+ backlog, the risk/reward favors owners.
The bull thesis holds for investors comfortable sitting through CapEx-driven FCF noise. The bear thesis gains traction if the Gemini talent exits signal a deeper competitive crack rather than a normal mega-cap shuffle.
Looking further ahead, here is where our model projects Alphabet could trade, assuming current growth and AI monetization hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $445.85 |
| 2027 | $515 |
| 2028 | $590 |
| 2029 | $650 |
| 2030 | $711.11 |
These projections assume Alphabet continues converting its AI lead into Cloud and Search revenue. Significant upside could come from TPU hardware sales scaling in 2027, while a regulatory forced breakup remains the largest single downside risk.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.